


EN
How Investors Are Reacting To AT&T (T) Satellite Phone Handoff
- AT&T reported that in October 2026 it completed what it believes is the first successful handoff between a ground cellular network and a direct to device satellite network with AST SpaceMobile, Ericsson and Nokia, aiming to extend coverage to remote US locations using standard smartphones.
- The collaboration highlights how AT&T is working to fuse terrestrial and space based connectivity, which could influence future network investment priorities, operating costs and service reliability in sparsely served areas.
- We will now assess how AT&T’s direct to device satellite handoff milestone could reshape the existing investment narrative around its network strategy.
Scan beyond AT&T and spot other connectivity plays that are pushing into harder to reach coverage areas with a curated short list of 42 power grid technology and infrastructure stocks.
AT&T Investment Narrative Recap
To stay on board as a shareholder in AT&T, you need to believe that heavy spending on 5G, fiber and network convergence can translate into steadier recurring service revenue and higher earnings over time. The analyst consensus Narrative on Simply Wall St leans on that thesis, while still flagging execution on copper retirement and cost take out as a key test.
In the short term, the direct to device satellite handoff and broader rural coverage push may not move the main needle. The primary focus is still network economics and free cash flow. The larger near term swing factor remains whether AT&T can take out roughly US$6b of legacy copper costs while keeping device subsidies from eroding margins.
The satellite handoff milestone aligns with AT&T’s broader push toward network convergence that the analyst consensus Narrative on Simply Wall St highlights as a core catalyst. If everyday smartphones can move between fiber backed terrestrial coverage and satellite service without noticeable interruption, that supports the story of more resilient connectivity for high value accounts.
The expanded collaboration with Smart Meter around Global SIM Advanced is closely related. It shows AT&T trying to turn better reach into stickier enterprise and healthcare relationships, which can be important if consumer equipment promotions weigh on profitability. Execution risk is real, because the operator still carries high debt and lower current profit margins than a year ago.
AT&T's narrative projects US$135.6b revenue and US$18.8b earnings by 2029. This is based on 1.7% yearly revenue growth and an earnings increase of about US$5.7b from US$13.1b today.
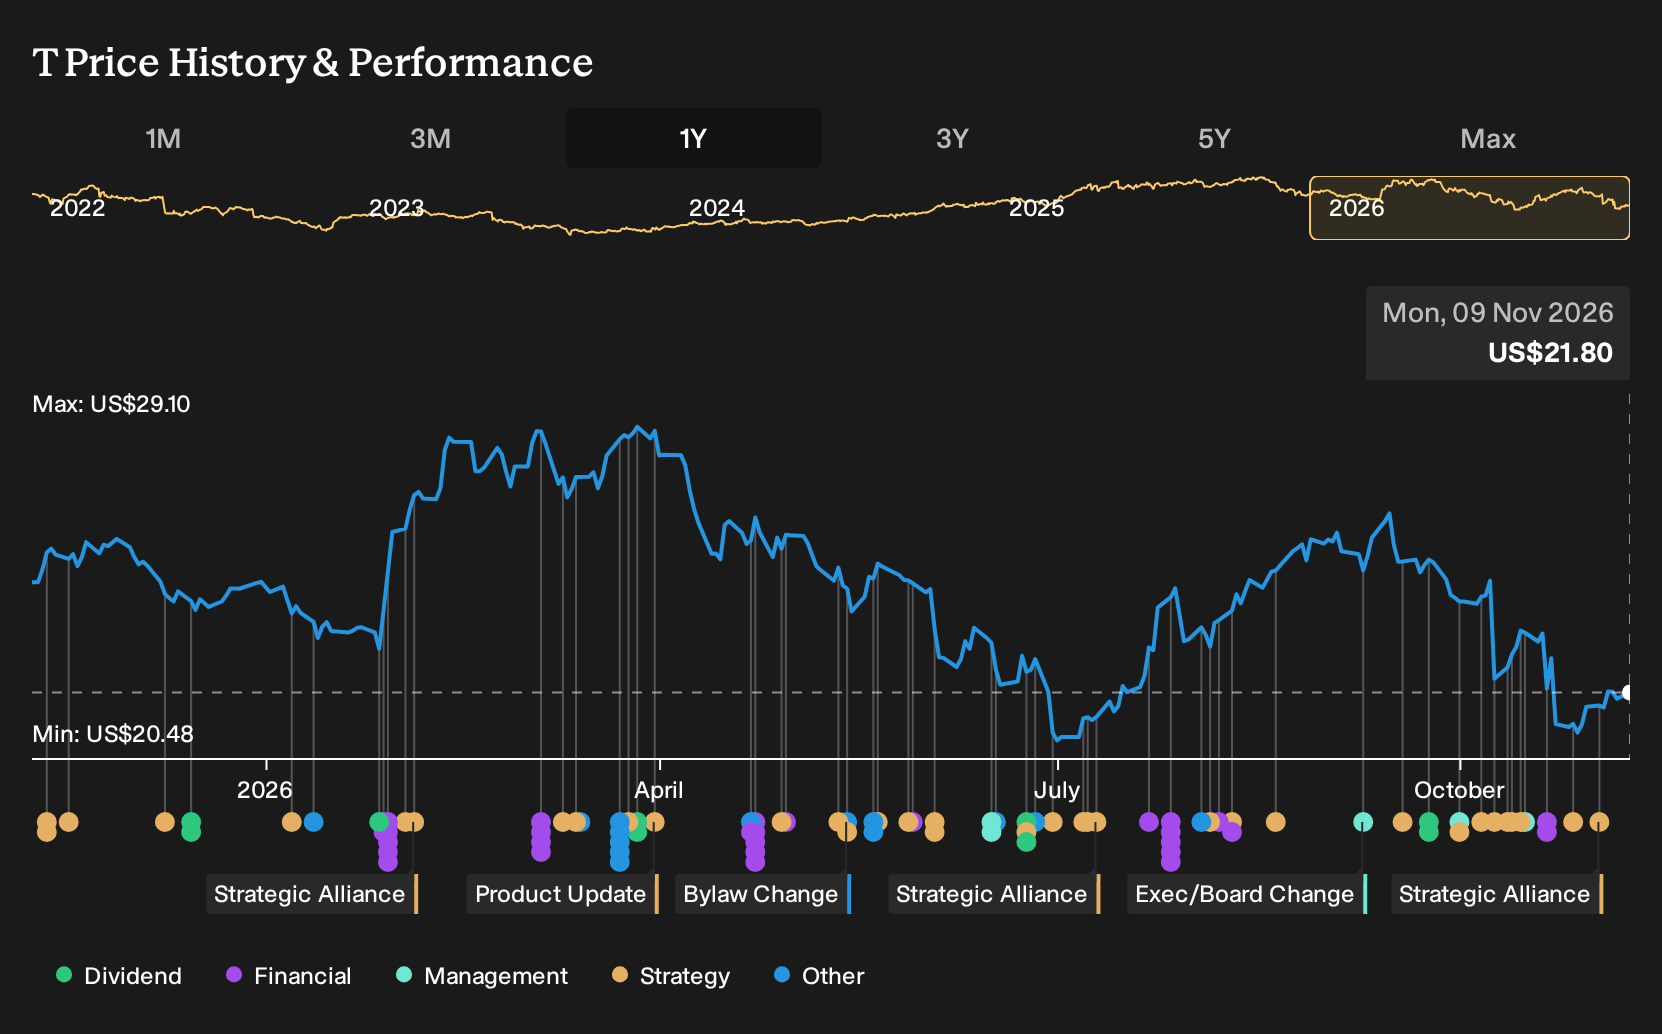
Uncover how AT&T's fair value indicates a 27% potential upside to its current price before the market fully prices in AT&T's network bets.
Exploring Other Perspectives
One point bearish analysts worry about is whether AT&T can squeeze real earnings from all this convergence work. Before this satellite news, the lowest forecasts were for roughly flat revenue near US$130.2b by 2029 and earnings of about US$18.3b. That is a much more cautious story. Use it as a prompt to compare several viewpoints and decide where you sit.
Explore 6 other AT&T fair value estimates, including one that suggests it could be worth just $24.54.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your AT&T research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for AT&T. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AT&T's overall financial health at a glance.
Looking For More Ideas Beyond AT&T?
If AT&T's network story has you thinking about how to position the rest of your portfolio, it can help to line it up against other opportunities using the Simply Wall St Screener.
- For investors who want potential mispricing on their side, use our curated set of 33 high quality undervalued stocks that pair quality fundamentals with appealing valuations.
- If capital preservation ranks high on your list, review a 30 resilient stocks with low risk scores that score well on financial stability and business risk.
- For those hunting for underfollowed opportunities, scan a focused group of 19 high quality undiscovered gems that combine solid metrics with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com