


EN
Ocular Therapeutix (OCUL) Missed Q3 Estimates As AXPAXLI Progressed, Is The Upside Already Priced In?
Ocular Therapeutix (OCUL) is in focus after third quarter results showed revenue of US$12.87 million and a net loss of US$94.78 million, along with updates on AXPAXLI's regulatory path.
Recent trading reflects that mixed message. Ocular Therapeutix shares are up 3.87% on a 1-day share price return and 1.78% over 7 days, yet the 30-day share price return is down 9.15% and the year-to-date share price return is down 42.05%, while the 3-year total shareholder return of about 3x suggests that long-term holders have still seen strong gains despite this year’s weaker momentum.
Compare Ocular Therapeutix's setback and long-term rebound with other high potential healthcare names by scanning our hand picked 36 healthcare AI stocks that are also trying to turn clinical progress into shareholder returns.
After a year where Ocular Therapeutix has given back a large chunk of its earlier surge, the puzzle now is simple. Has the stock already banked most of AXPAXLI's promise, or is meaningful upside still in front of it on valuation grounds?
Most Popular Narrative: 73% Undervalued
On the analyst consensus Narrative on Simply Wall St, Ocular Therapeutix screens as heavily discounted, with a fair value of $25.45 against a last close of $6.85. That view leans on AXPAXLI, the cash runway and a detailed earnings path built into the model.
The planned AXPAXLI NDA submission for wet AMD in Q4 2026 using a single, superiority SOL-1 trial under a 505(b)(2) pathway, supported by confirmatory evidence and interim safety data, could bring Ocular Therapeutix to its first major retinal drug approval window and start to shift revenue from a largely pre-commercial base.
The HELIOS-3 Phase 3 once yearly AXPAXLI program in diabetic retinal disease, using an FDA endorsed ordinal DRSS endpoint and covering both diabetic retinopathy and non center involved diabetic macular edema, targets a market described as several times larger than wet AMD and gives Ocular Therapeutix a second potential growth leg for future revenue diversification.
See why 12 investors see Ocular Therapeutix as 73% undervalued.
Result: Fair Value of $25.45 (UNDERVALUED)
Still, the Ocular Therapeutix story leans heavily on AXPAXLI, so any delay to the single trial NDA or slower physician uptake could quickly challenge that 73% undervalued narrative.
Find out about the key risks to this Ocular Therapeutix narrative.
Another View on Ocular Therapeutix Valuation
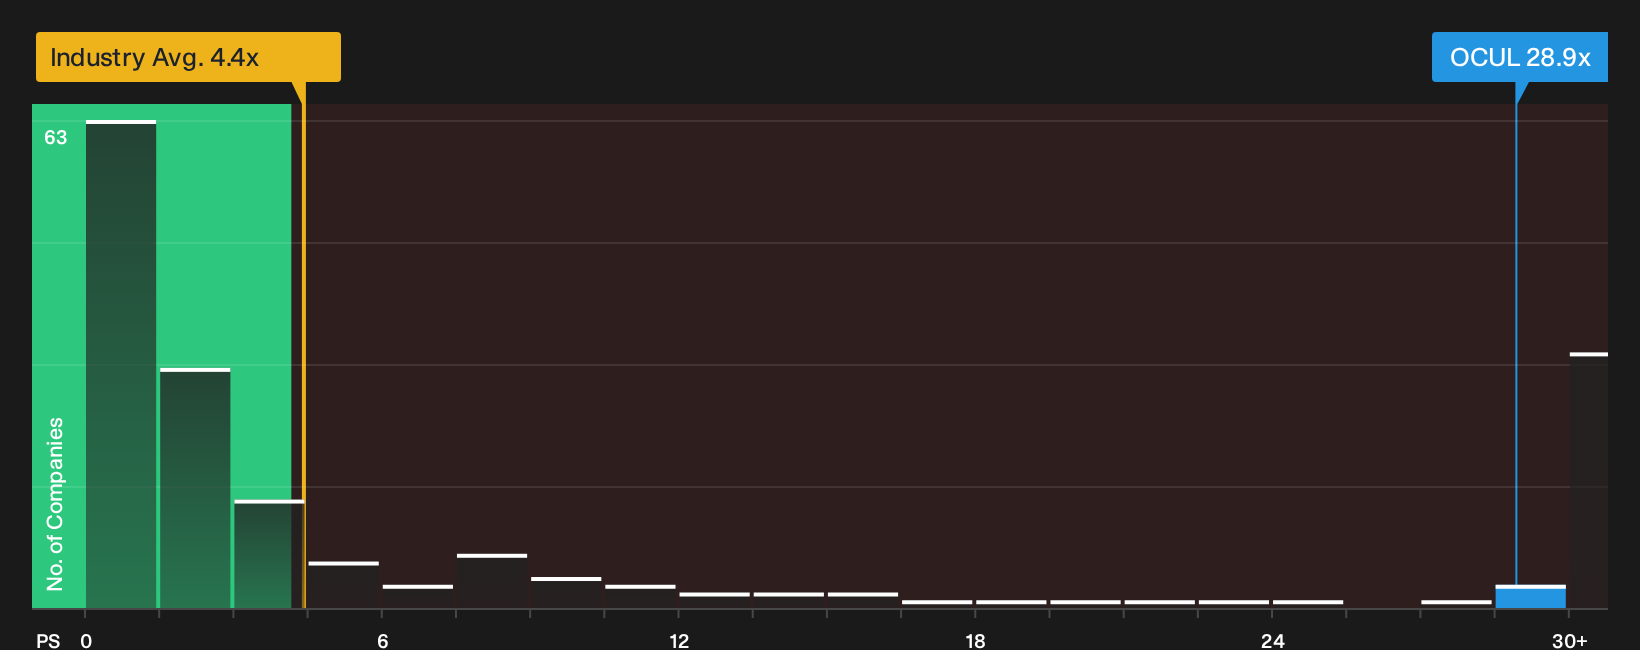
The first narrative paints Ocular Therapeutix as heavily undervalued. The P/S picture tells a very different story. At roughly 28.9x sales against a US pharmaceuticals average of 4.2x, and a fair ratio of just 0.2x, the stock screens extremely expensive on this metric. Is the market overpaying for a single asset story, or is the multiple simply reflecting how binary AXPAXLI has become for this ticker?
For investors who prefer to lean on comparative ratios rather than detailed cash flow models, the valuation gap and its risks are broken down in more depth in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or a clear setup for Ocular Therapeutix? Take a closer look at the full picture yourself, weigh both sides of the story, and stress test your thesis against the 2 key rewards and 3 important warning signs.
Want more investment ideas beyond Ocular Therapeutix?
You have seen how one stock can split opinion. Do not stop there. Use targeted screeners to hunt for setups that better match your own playbook.
- Target potential mispricing by reviewing companies that look cheaply valued on both quality and fundamentals using the 33 high quality undervalued stocks.
- Prioritise resilience by checking the list of solid balance sheet and fundamentals (25 results) so you focus on businesses with stronger financial footing when conditions turn tougher.
- Get ahead of the crowd by scanning the 19 high quality undiscovered gems before attention and liquidity start to follow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com