


EN
How Mixed Earnings At Capital Southwest (CSWC) Has Changed Its Investment Story
- Capital Southwest reported second quarter 2026 results with revenue of US$67.16 million and net income of US$21.44 million, with basic and diluted EPS from continuing operations of US$0.33.
- The business reported higher revenue for both the quarter and the first half of fiscal 2026 compared with a year earlier, while net income and earnings per share declined, indicating pressure on profitability even as the earning asset base increased.
- The next step is to consider how Capital Southwest's investment narrative aligns with this combination of higher revenue and softer earnings.
Scan how Capital Southwest's latest earnings profile compares with a curated 6 dividend fortresses. This may appeal if you are weighing income potential against recent profit pressure.
Capital Southwest Investment Narrative Recap
For a shareholder in Capital Southwest, the core belief is that the lending platform can keep growing income producing assets while keeping credit quality under control. The latest quarter reflects that balance clearly. Revenue of US$67.16 million and net income of US$21.44 million show a business that is still writing loans, but facing some profit pressure.
The analyst consensus narrative on Simply Wall St focuses on catalysts such as first lien emphasis, sponsor deal flow and extra funding capacity to support earnings. The recent step down in EPS to US$0.33 per share highlights the near term swing factor. The key short term risk remains spread compression and funding costs outpacing the added income from new loans.
The most relevant update is the same second quarter release because it ties directly back to those earlier catalysts around portfolio expansion and funding. Management reported six month revenue of US$128.21 million and net income of US$46.17 million, which shows higher top line against softer profitability compared with the prior year period.
For you, the practical question is whether Capital Southwest can use tools flagged in that earlier narrative, such as the larger credit facilities and SBIC leverage, without eroding returns through higher interest expense or added equity issuance. Execution around credit quality, nonaccruals and fee income from areas such as the CapTrin joint venture will matter for how quickly earnings per share track any further growth in assets.
Capital Southwest's narrative projects US$357.6 million revenue and US$219.3 million earnings by 2029. This assumes 14.7% yearly revenue growth and roughly a doubling in earnings from about US$109.5 million today to the 2029 consensus level.
Uncover why Capital Southwest's fair value indicates an 8% potential upside to its current price that could narrow quickly.
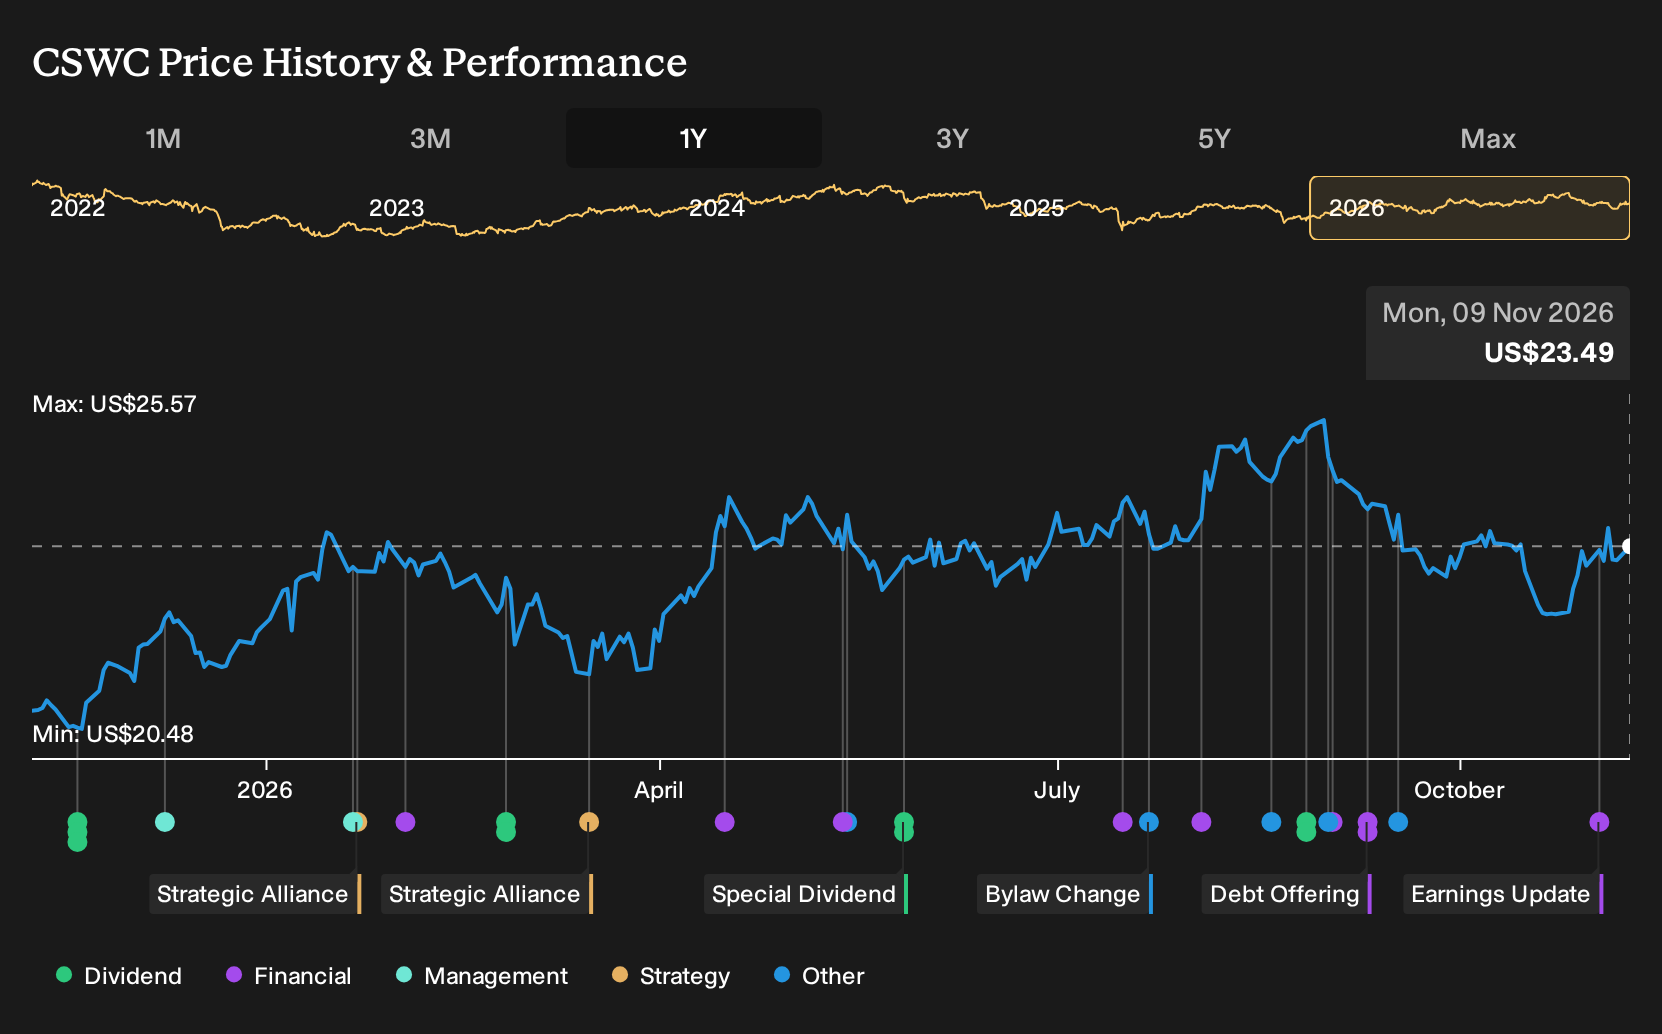
Exploring Other Perspectives
Across 2 fair value estimates from the Simply Wall St Community, Capital Southwest carries a tight band between about US$25.30 and just under US$29.91, showing retail investors clustering rather than spreading out. Those views were set before the latest earnings, so you should weigh them against ongoing spread pressure, potential share issuance and credit cycle risk. Then explore several alternative viewpoints before deciding how this lender fits your portfolio goals.
Explore another Capital Southwest fair value estimate, including one that suggests as much as 27% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Capital Southwest research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Capital Southwest. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Capital Southwest's overall financial health at a glance.
Looking for more investment ideas beyond Capital Southwest?
Once you have formed a view on Capital Southwest, it can help to compare it with a wider field of listed businesses that offer different mixes of income, quality and risk.
- If you want income with an emphasis on resilience, scan a curated 6 dividend fortresses that focus on payout strength and consistency.
- For investors hunting for quality at a reasonable price, weigh Capital Southwest against a 33 high quality undervalued stocks that combine solid fundamentals with compressed valuations.
- When capital preservation sits near the top of your priorities, review a 30 resilient stocks with low risk scores that screen for sturdier balance sheets and milder risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com