


EN
United Therapeutics (UTHR) Stock Still Looks Like A Bargain As Its 184% Run Continues
United Therapeutics has seen its stock climb sharply over recent years, and that kind of run naturally raises a simple question for investors who care about fundamentals: Is the current share price still in step with the earnings the company is generating today?
- United Therapeutics has returned about 184.1% over the past 5 years, which puts real pressure on the question of whether its current earnings profile can carry that kind of re-rating.
- Recent updates around higher research and development spending, pipeline progress and a new share repurchase program can all influence how durable profit levels look and how much of those earnings ultimately flow to each share.
- The analysts covering United Therapeutics have run their own numbers. See what analysts think United Therapeutics's shares could be worth.
The issue now is whether United Therapeutics' current market price is adequately supported by the earnings investors can reasonably link to the business today.
If you want to see how the earnings story of United Therapeutics compares with other high-performing opportunities, you can compare it with companies in the 33 high quality undervalued stocks.
Does United Therapeutics Look Undervalued on Earnings?
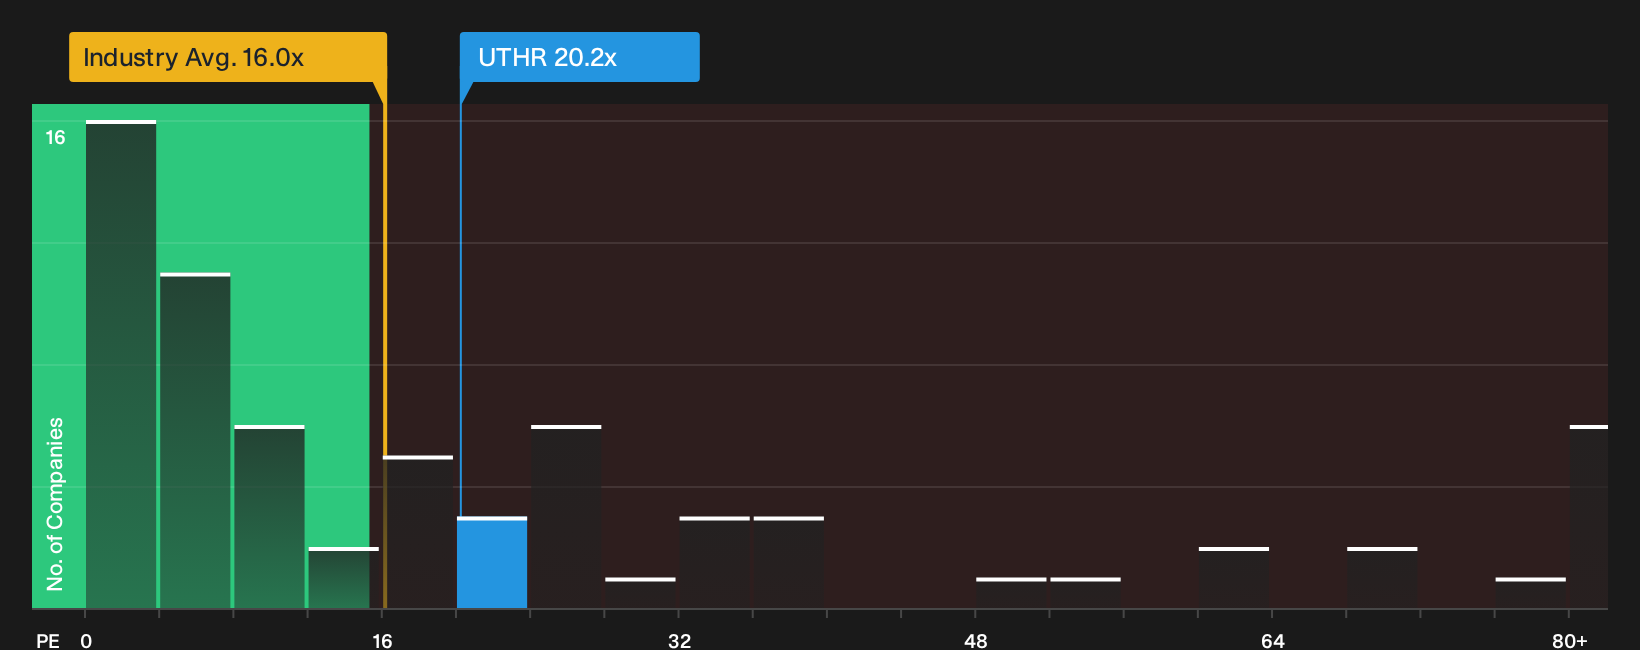
The P/E ratio fits United Therapeutics because earnings still sit at the center of how investors frame this business. On this yardstick, the stock trades on roughly 20.2x earnings, below both the biotech industry average of about 16.0x and a much higher peer group average of around 53.5x. Because the recent share price is also lower than the multiple suggested by a tailored fair-value model that accounts for United Therapeutics' growth profile, profitability and risk, the shares screen as undervalued on this measure.
Because higher research and development spending is weighing on near term earnings, the current P/E may not fully capture how investors are treating the pipeline and product portfolio after the Q3 2026 update. For anyone weighing the stock, the key question is whether that lower P/E relative to the fair ratio reflects an overly cautious read on future profitability or a realistic adjustment for execution and regulatory risk in the pipeline. Explore the numbers behind United Therapeutics's P/E valuation.
The United Therapeutics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for United Therapeutics pick up where the valuation work leaves off. They spell out which assumptions on United Therapeutics' growth, margins and earnings would need to hold for the shares to trade at meaningfully different levels from today. Each one treats fair value as a thesis you can track over time rather than a single frozen estimate.
Bulls and bears on United Therapeutics are looking at the same pipeline and organ platform and reaching very different conclusions on what the stock is pricing in.
Bull case: 31% undervalued
This view, from the bullish analyst Narrative on Simply Wall St, leans heavily on pulmonary fibrosis and organ manufacturing as the next leg of the story.
"The wave of differentiated treprostinil and ralinepag delivery platforms, including Tyvaso DPI, soft mist Trezmi and TreSMI, and once daily RAL DPI and Jenraldi, creates room for mix shift toward higher convenience and potentially longer duration therapy, which could support pricing power, patient adherence and a more resilient revenue and earnings profile across pulmonary indications…"
Discover why this Narrative puts United Therapeutics at 31% undervalued.
Bear case: 28% overvalued
The bearish analyst Narrative on Simply Wall St argues that a pressured pulmonary hypertension base and heavy spending could still keep a lid on the equity story.
"Despite a sequenced delivery platform strategy for treprostinil and ralinepag that aims to support revenue into the 2040s, the recent pattern of quarterly and multi year declines in revenue and EPS, together with Tyvaso results that fell short of expectations, indicates that newer formulations may at best offset competitive and pricing headwinds rather than expand earnings…"
Explore why this Narrative puts United Therapeutics at 28% overvalued.
The share price is only one clue to the United Therapeutics puzzle
Valuation tells you what the market is paying today, but the missing piece is how professional analysts currently see United Therapeutics a few years from now and how that lines up with your own expectations. Explore where analysts expect United Therapeutics to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com