


EN
3 British Dividend Stocks Returning Over 3% Yield
With the Bank of England warning that young people are getting squeezed by a low gear UK economy, dependable income from established British dividend payers looks increasingly appealing. Reliable cash returns can feel more tangible than hoping for the next hot growth story. This article walks through three high yielding UK stocks from a screen that looks for dividends above 3% that appear well covered, growing and relatively steady.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher yielding dividend payers with income that aims to be well covered, growing and relatively steady. However, if you want the absolute best, these 6 dividend aristocrats stocks are the cream of the crop.
RHI Magnesita (LSE:RHIM)
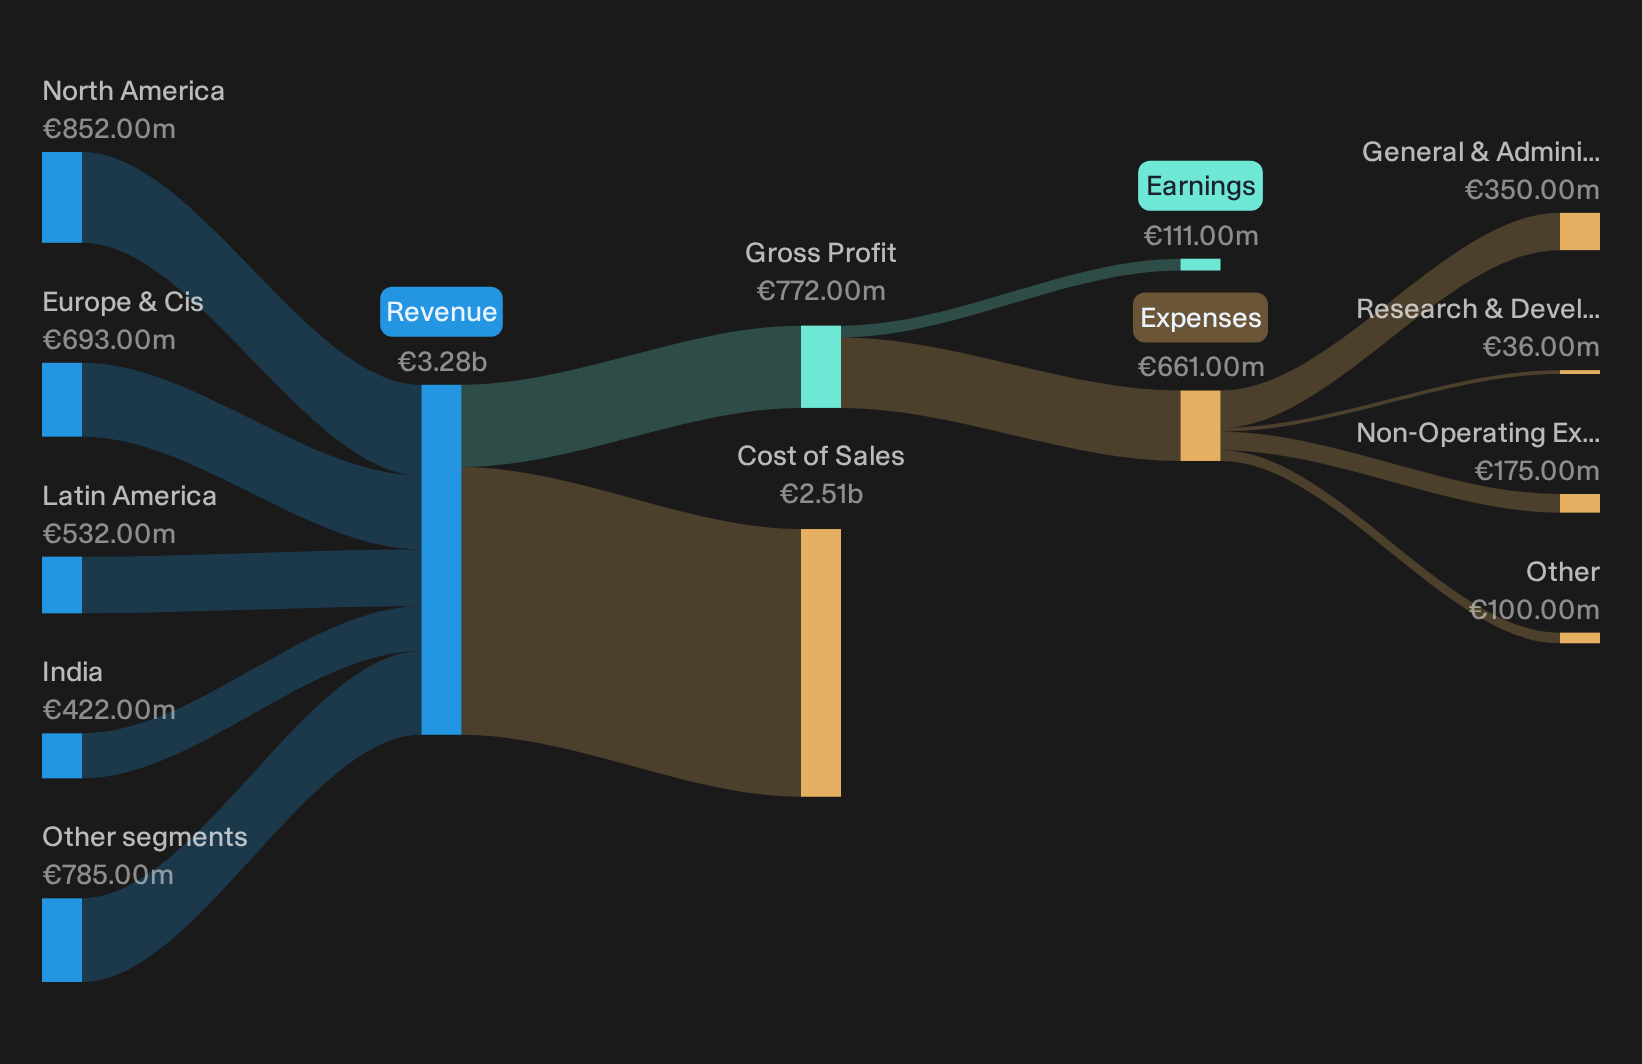
RHI Magnesita is a €2.9b high temperature specialist, selling refractory bricks, linings and lifecycle services that keep steel and other heavy industry plants running. Revenue is spread across India (€422 million), Europe & CIS (€693 million), Latin America (€532 million) and North America (€852 million). The group’s market cap is about £1.3b.
For income hunters, RHI Magnesita matters because its steel focused refractory products and services can create recurring cash flows. The analyst consensus Narrative on Simply Wall St frames those cash flows as the bedrock for a higher, well covered dividend profile.
"The company's leadership in developing circular economy solutions via new recycling infrastructure is still intended to attract more ESG focused customers and reduce raw material cost exposure. This can support both sales volumes and gross margins as recycling usage increases."
The real swing factor for RHI Magnesita’s dividend appeal now is how one pressure point in its cost base ultimately filters through to margins.
That cost pressure is exactly what the full narrative for RHI Magnesita unpacks in detail, showing where pricing power, recycling economics and capital discipline could still reshape the income story.
Rathbones Group (LSE:RAT)
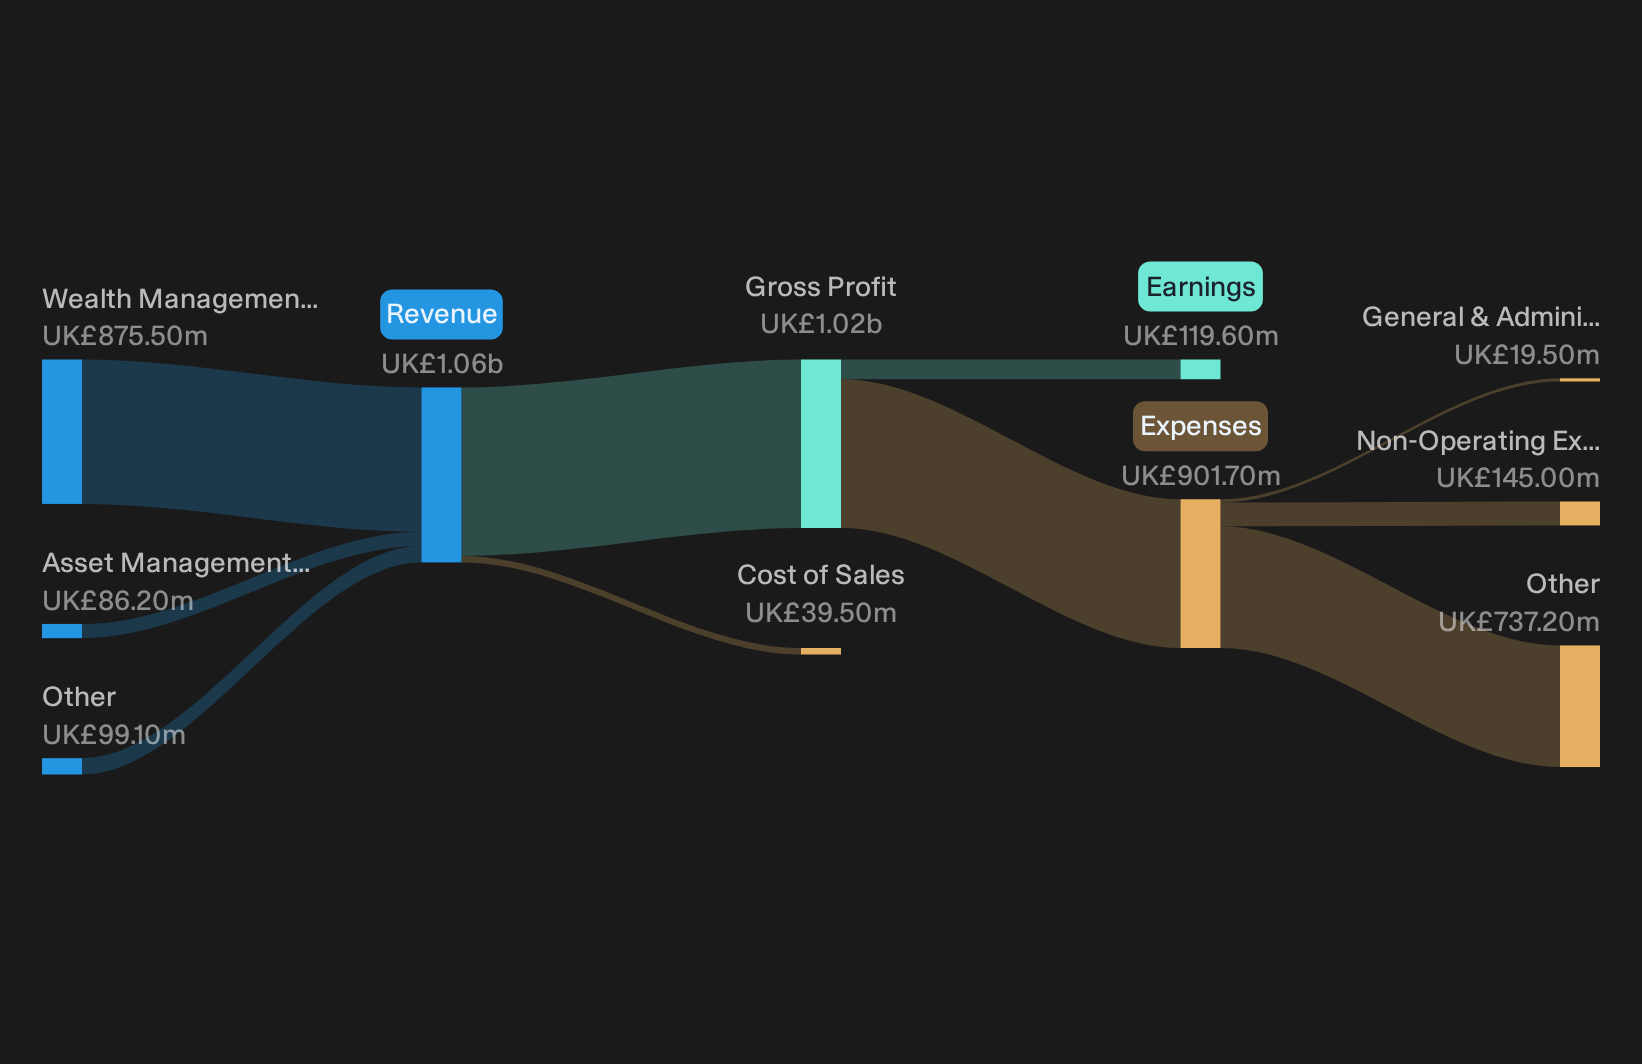
Rathbones Group is a long running wealth manager that leans on fee based discretionary investment and financial planning work to support a 3%+ income stream. Wealth management contributes around £876 million of revenue versus £86 million from asset management, and the group is valued at roughly £1.8b.
For income focused investors, Rathbones Group matters because its wealth management arm generates recurring fees that can underpin a higher yield, and the analyst consensus Narrative on Simply Wall St states that recent integration work has quietly shifted the economics of that engine.
"The completion of the Investec Wealth & Investment integration, with £76m of annualised run rate synergies already identified ahead of the original timetable, leaves Rathbones Group with further room to convert scale and streamlined systems into higher operating margins and earnings."
How those margins evolve if one still unresolved cost line refuses to fall in line will be crucial for long term dividend comfort.
If that cost line keeps dragging, full narrative for Rathbones Group shows how accelerating synergies, capital discipline and fee trends could still reshape the income story.
Man Group (LSE:EMG)
Man Group is a global investment manager running quantitative, long only and alternative funds that earn fee income on client assets, which in turn underpins its 3%+ dividend profile. The investment management business generates about $1.7b of revenue, and the group is valued at roughly £3.4b.
The appeal of Man Group for an income focused screen lies in how its fee based investment platform supports regular cash generation. Analyst consensus Narrative on Simply Wall St notes that this fee pool is being reshaped by a deeper push into credit and private credit.
"Continued build out of the credit and private credit platform, including over $60b of credit AUM and $17.6b in private credit by mid 2026 plus $4.9b of uncalled committed capital, gives scope for further deployment that can support fee revenue and diversify profit drivers."
What happens to that dividend comfort will come down to how one evolving source of client demand and fee momentum actually behaves across a tougher cycle.
That is exactly what the full narrative for Man Group lays out in full, tracing where fee momentum, credit build out and capital returns could still accelerate the Man Group story.

Seeking Alternatives Before The Crowd
Fresh opportunities do not stay under the radar for long. By the time momentum is flying, the ideal entry can be gone. Scan these ideas now and review them while they may still be overlooked.
- Target resilient cash generators before they are re-rated by institutions with a curated set of 16 high quality undervalued stocks while the valuations still look beaten down and underappreciated.
- Hunt for potential future infrastructure linchpins with a focused group of 42 power grid technology and infrastructure stocks before grid upgrades and electrification themes are fully reflected in these tickers.
- Consider positioning ahead of the next automation wave by reviewing carefully filtered 91 robotics and automation stocks that may benefit as factories and warehouses continue upgrading their systems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com