


EN
Clearway Energy (CWEN) Sales Rose As Profit Fell, Is It Still Below Fair Value?
Clearway Energy (CWEN) just posted third quarter 2026 results that paired higher sales with sharply lower profit, a mix that gives investors fresh numbers to reassess this clean power producer.
Clearway Energy's latest earnings release comes as the share price trades near US$34.70, with a 1 month share price return of 14.9% that signals momentum building after softer moves earlier in the year. At the same time, a 3 year total shareholder return of 93.4% points to a much stronger longer run story than the recent 1 year total shareholder return of 3.5% might suggest.
Scan how Clearway Energy's latest earnings reset compares with other utilities shifting their revenue mix by reviewing the hand picked 42 power grid technology and infrastructure stocks.So after a 14.9% one month jump and earnings that lifted sales while squeezing profit, does Clearway Energy still offer enough upside to justify the hit to earnings quality, or has the easy part of the rerating already played out?
Most Popular Narrative: 14% Undervalued
Clearway Energy's analyst consensus Narrative on Simply Wall St points to a fair value of about $40.43 per share compared with the latest close at $34.70. This frames the recent rally against a still implied discount and sets up a closer look at what is driving that view.
Rising long-term power demand from data centers and large technology customers, including multi decade PPAs with hyperscalers and Google, supports a larger contracted asset base that can increase revenue visibility and support future earnings growth.
Expansion of late stage wind, solar and storage projects, with 100% of 2026 and 2027 vintages already commercialized and a 2028 to 2029 pipeline larger than what is needed for internal CAFD targets, gives the company multiple ways to add contracted capacity that can lift CAFD and support dividend coverage.
See why 14 investors see Clearway Energy as 14% undervalued.
Result: Fair Value of $40.43 (UNDERVALUED)
Still, the Clearway Energy narrative can unravel if data center demand for long term power contracts disappoints or if policy and permitting delays slow its project build out.
Find out about the key risks to this Clearway Energy narrative.
Another View on Clearway Energy’s Valuation
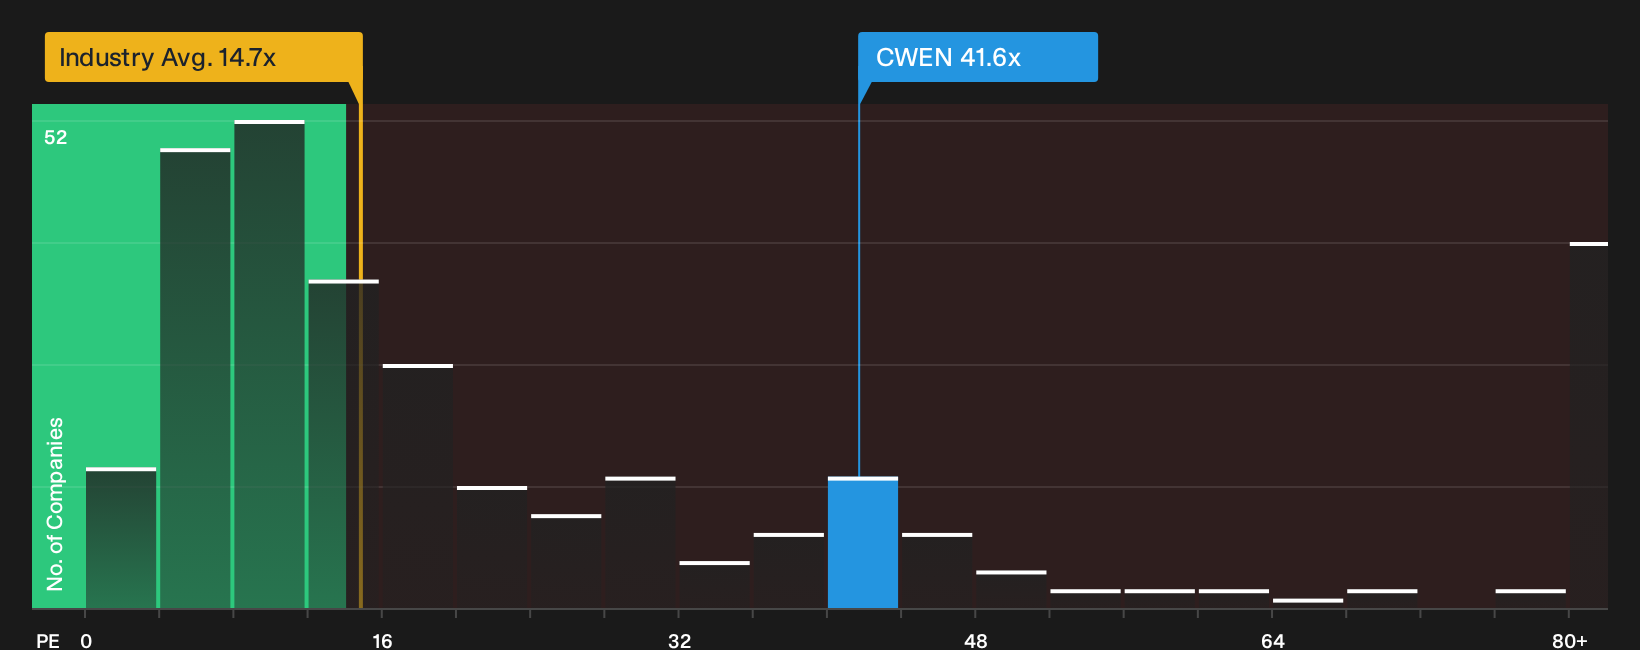
That 14% implied discount from the narrative sits uncomfortably next to Clearway Energy’s current P/E of 41.6x, which is far richer than both the peer average at 29.2x and the global renewable energy group at 14.5x. The fair ratio of 26.7x suggests the market could migrate toward a lower multiple, which would pressure the share price rather than support upside. So is the story here a bargain or just a high bar for future execution?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Clearway Energy so far, right, which is exactly why you should move quickly, test the numbers yourself, and weigh both sides of the story. To shortcut that process a little, start by reviewing the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Clearway Energy?
If Clearway Energy has sharpened your focus on where capital works hardest, do not stop here. The next move you make could matter even more.
- Target higher quality potential upside by scanning a 33 high quality undervalued stocks that lines up solid fundamentals with prices that still look modest.
- Strengthen your income engine by reviewing a 6 dividend fortresses that focuses on companies pairing elevated yields with firm underlying cash flows.
- Dial down portfolio stress by checking a 30 resilient stocks with low risk scores that highlights businesses with sturdier financial profiles and fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com