


EN
Enpro (NPO) Raised Guidance, Is The Upside Already Priced In?
What Enpro’s latest earnings signal for investors
Enpro (NPO) is back in focus after reporting third quarter 2026 results, with higher year over year sales and net income and an updated full year revenue outlook that points to improved operational traction.
The industrial technology specialist posted third quarter sales of US$350.8 million compared with US$286.6 million a year earlier, while net income was US$40.3 million versus US$21.6 million. Earnings per share from continuing operations also came in higher on both a basic and diluted basis.
Enpro’s latest update landed alongside a sharp 6.9% 1 day share price return to US$276.12. This comes even though the 30 day share price return is down 11.34% and the 90 day move is down 17.94%. At the same time, a 29.27% 1 year total shareholder return and a very large 3 year total shareholder return of 127.54% point to longer term momentum that recent earnings and higher guidance appear to have brought back into focus.
Spot similar industrial and semiconductor suppliers showing strong recent results and guidance shifts by scanning our curated 19 high quality undiscovered gems alongside Enpro’s latest move.After a sharp single day jump and a strong multi year track record, Enpro now sits in a tougher spot. Is meaningful upside still ahead, or has most of the move already played out on the current valuation?
Most Popular Narrative: 29% Undervalued
The analyst consensus Narrative on Simply Wall St places Enpro’s fair value at $389.50, well above the last close of $276.12. This frames the latest earnings jump against a valuation that already bakes in ambitious growth and margin goals.
“Capacity expansions in Enpro’s Advanced Surface Technologies business, including higher 2026 capital expenditure directed toward facilities in Arizona, Milpitas and Taiwan, are aligned with customer build plans that currently provide visibility through 2027 and are expected to influence future revenue and segment margins as this semiconductor and AI investment cycle plays out.
Sustained momentum in semiconductor related demand, with AST segment sales rising 21.8% year over year in Q2 2026 and management targeting about 20% revenue growth and adjusted EBITDA margins approaching 25% in the second half of 2026, positions Enpro to convert its existing backlog into higher earnings power.”
See why 2 investors see Enpro as 29% undervalued.
Result: Fair Value of $389.50 (UNDERVALUED)
Still, Enpro’s story can change quickly if semiconductor and AI investment cools, or if environmental liabilities require more cash than is currently reserved.
Find out about the key risks to this Enpro narrative.
Another view on Enpro’s valuation
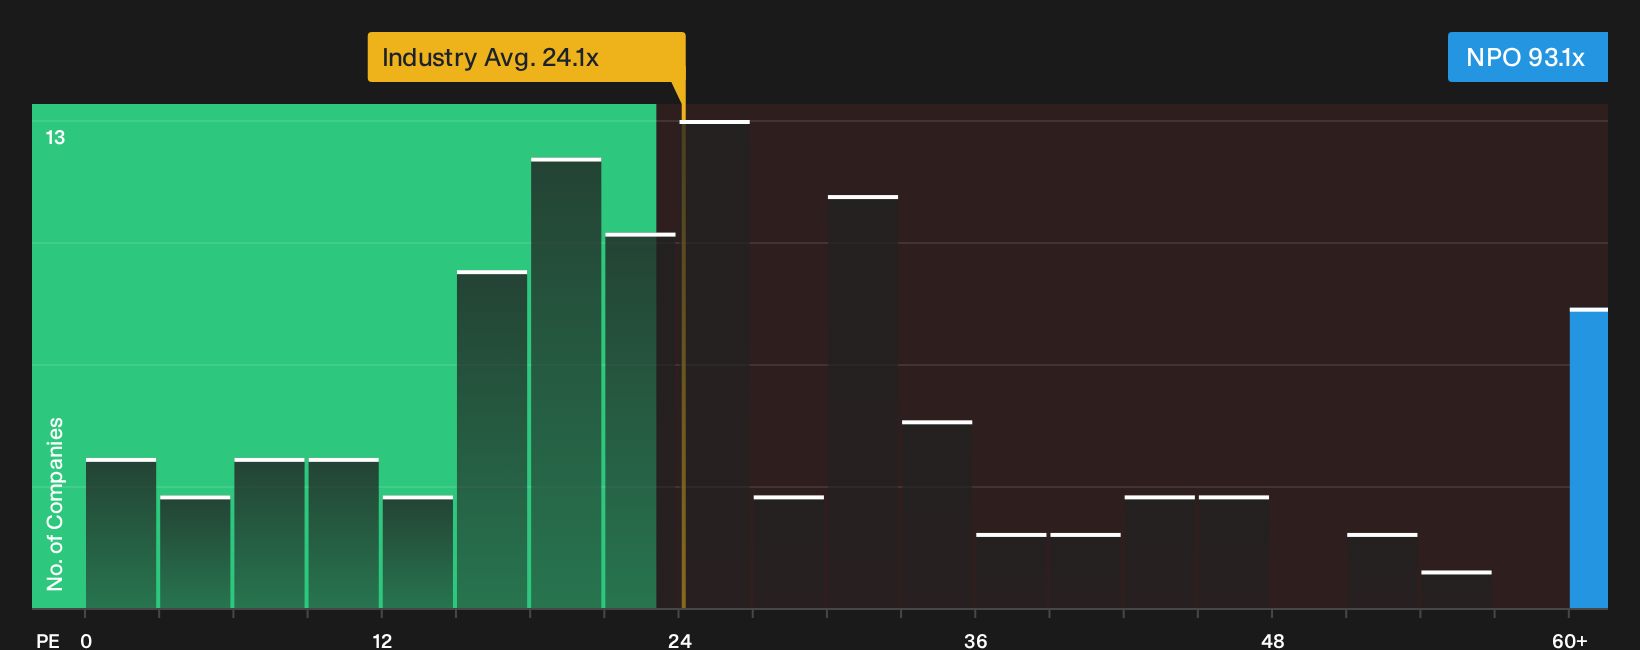
Analyst models on Simply Wall St frame Enpro as undervalued, yet the current P/E of 93.1x is described as expensive versus a fair ratio of 43.3x, the US Machinery industry at 23.2x, and a 29x peer average. That gap suggests meaningful valuation risk if expectations reset. Where does that leave you on the trade off between quality and price?
To pressure test whether the current earnings multiple leaves enough margin for error, take a closer look at how the numbers stack up in our valuation breakdown, including the fair ratio that the market could move toward over time, via the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Plenty of optimism runs through this Enpro story, yet there are also clear risk flags. If you want to move fast and reach your own judgment based on a balanced picture of concerns and potential upsides, start with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Enpro?
If Enpro’s latest move has sharpened your focus, do not stop here. The right screener can surface opportunities you would never spot manually.
- Hunt for underpriced quality by scanning companies with strong fundamentals and potential valuation gaps using the 33 high quality undervalued stocks.
- Target resilient businesses that aim to protect capital first by filtering for companies with sturdier finances through the 30 resilient stocks with low risk scores.
- Zero in on firms with healthier balance sheets and solid fundamentals by running a focused search via the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com