


EN
ON Semiconductor (ON) Reports Stronger Outlook, Is The Valuation Gap Still Compelling?
ON Semiconductor (ON) drew fresh attention on 2 November 2026 after reporting third quarter results alongside new fourth quarter revenue guidance that points to above seasonal sequential growth at the midpoint.
The fresh revenue outlook and stronger third quarter figures hit a stock that has been through a choppy spell. ON Semiconductor’s share price is up 9.16% over the last day but down 10.86% over 30 days and 14.79% over 90 days, while total shareholder return over the past year is 42.38% and 5-year total shareholder return is 16.74%. Together, these figures indicate that recent momentum has cooled compared with a stronger longer-term run.
See how ON Semiconductor compares with other chip companies experiencing similar earnings momentum by exploring our curated list of 53 AI infrastructure stocks.
ON Semiconductor has rebounded on fresh guidance, yet the share price is still well below its recent highs. Is most of the straightforward upside already realized, or does the current valuation still leave meaningful headroom?
Most Popular Narrative: 32% Undervalued
ON Semiconductor’s last close at $69.11 sits well below the analyst consensus Narrative fair value of $101.63, which implies a large valuation gap when using a 11.99% discount rate in the analyst consensus Narrative on Simply Wall St that compiles forecasts and price targets.
Rapid growth in AI data center infrastructure, combined with ON Semiconductor's claim to support the full power path from grid to processor and early traction with platforms such as NVIDIA MGX, AWS power systems and Chinese providers, underlies management's expectation that AI data center revenue will more than double in 2026 versus 2025 and scale at 50% or faster over several years, which is likely to be a key driver of overall revenue and earnings growth.
See why 130 investors see ON Semiconductor as 32% undervalued.
Result: Fair Value of $101.63 (UNDERVALUED)
Still, the ON Semiconductor narrative can be knocked off course if automotive demand stays sluggish or if fabs run below plan, which would put pressure on the margin story.
Find out about the key risks to this ON Semiconductor narrative.
Another View: ON Semiconductor Through The P/E Lens
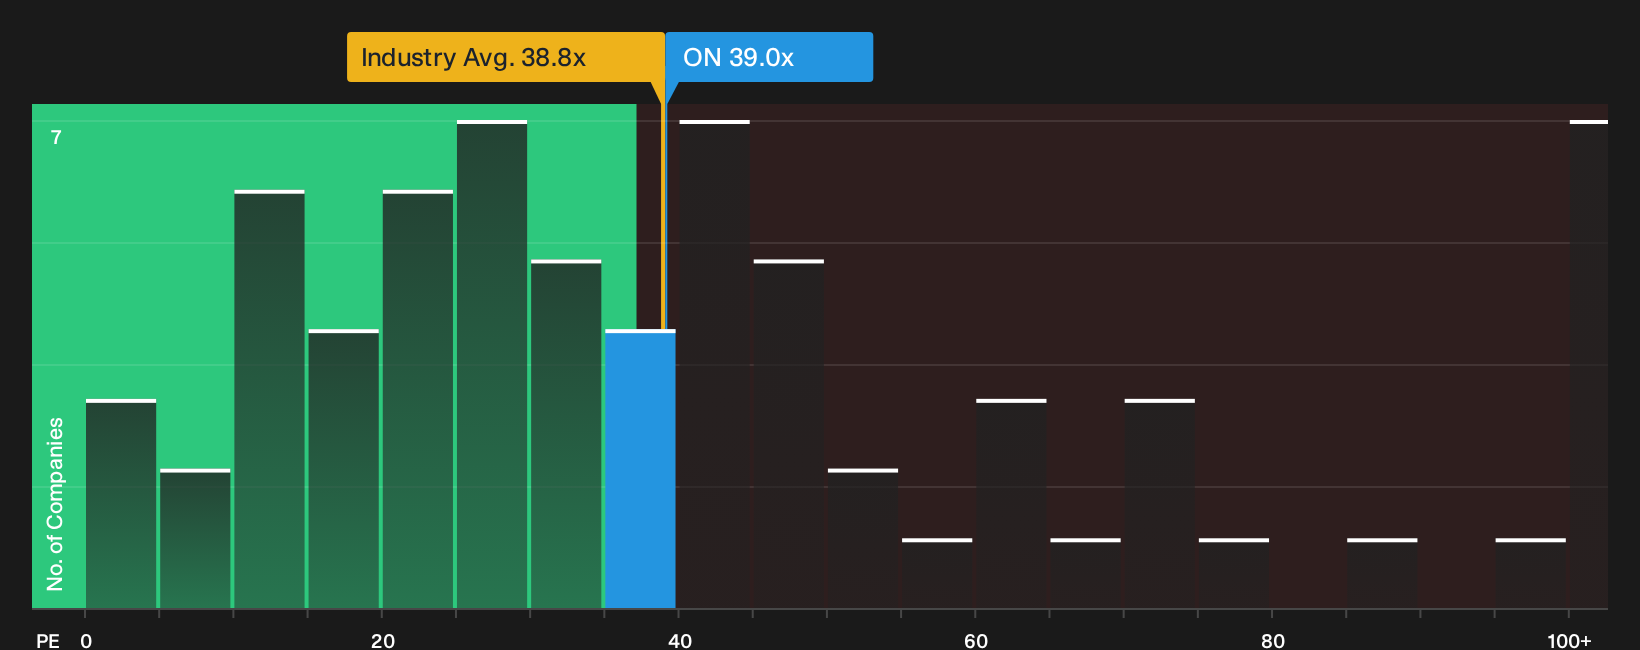
The narrative fair value for ON Semiconductor suggests a wide gap to $101.63, yet the simple P/E check paints a tighter picture. ON trades at about 39x earnings versus an estimated fair ratio of 37.9x and the US Semiconductor industry at 38.8x.
That means the stock currently sits slightly above the fair ratio and broadly in line with the wider sector, while still looking cheaper than a peer average of 61x. For investors, that mix points to less obvious multiple based upside and more emphasis on execution risk if sentiment cools. Where does that leave the comfort level with paying up for the growth story?
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the ON Semiconductor story still feels finely balanced between promise and risk, now is the moment to dig into the details yourself and decide where you stand. For a concise view of the trade off between the downside issues investors worry about and the upside factors they are excited about, start with these 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond ON Semiconductor?
If ON Semiconductor has sharpened your thinking, keep the momentum going by lining up a few fresh stock ideas built around clear financial strengths and different risk profiles.
- Spot opportunities with pricing power and balance sheet resilience by reviewing our hand picked 33 high quality undervalued stocks that combine quality metrics with discounted valuations.
- Prioritise durability in your income stream by scanning a focused set of 6 dividend fortresses where yield pairs with business strength and payout discipline.
- Dial back risk without stepping away from the market entirely by working through a targeted 30 resilient stocks with low risk scores designed to highlight resilient fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com