


EN
Silicon Laboratories (SLAB) Looks Fully Valued Following Its 68% Run
Silicon Laboratories Stock: Recent Returns Put Under The Microscope
Silicon Laboratories (SLAB) has drawn fresh attention after a solid run, with the stock showing a year to date return of 68.1% and a 1 year total return of 69.8%. Investors now face a different question: how much of the company’s mixed signal IoT story is already reflected in the current valuation, and where that leaves prospective buyers and existing holders weighing their next move.
Across that backdrop, Silicon Laboratories has posted a strong year to date share price return, while the 1 year and 3 year total shareholder returns show substantial gains, signalling momentum that has cooled only slightly in recent weeks as the stock consolidates around US$221.80.
Scan how Silicon Laboratories compares with other mixed-signal and IoT chip plays by reviewing our curated list of 53 AI infrastructure stocks in one place.
After a 68.1% year-to-date surge and a share price near the latest analyst target, Silicon Laboratories now forces a choice: lean in at US$221.80 or wait for the valuation to blink first.
Most Popular Narrative: 0% Undervalued
Silicon Laboratories is trading at $221.80, almost exactly in line with the analyst consensus Narrative fair value of $222.86, which uses an 11.32% discount rate and assumes substantial future earnings power to justify today’s price.
Planned acquisition by Texas Instruments, with more than US$450 million of annual manufacturing and operational synergies targeted within three years of closing and expectations for earnings per share accretion in the first full year, supports the view that Silicon Laboratories’ gross margin model in the high 50s and its industrial IoT focus can translate into stronger net margins over time.
See why 5 investors see Silicon Laboratories as 0% undervalued.
Result: Fair Value of $222.86 (ABOUT RIGHT)
Still, the story can crack if the Texas Instruments deal fails to deliver planned synergies, or if ongoing net losses persist longer than the current narrative assumes.
Find out about the key risks to this Silicon Laboratories narrative.
Another View: Silicon Laboratories Through A Sales Multiple Lens
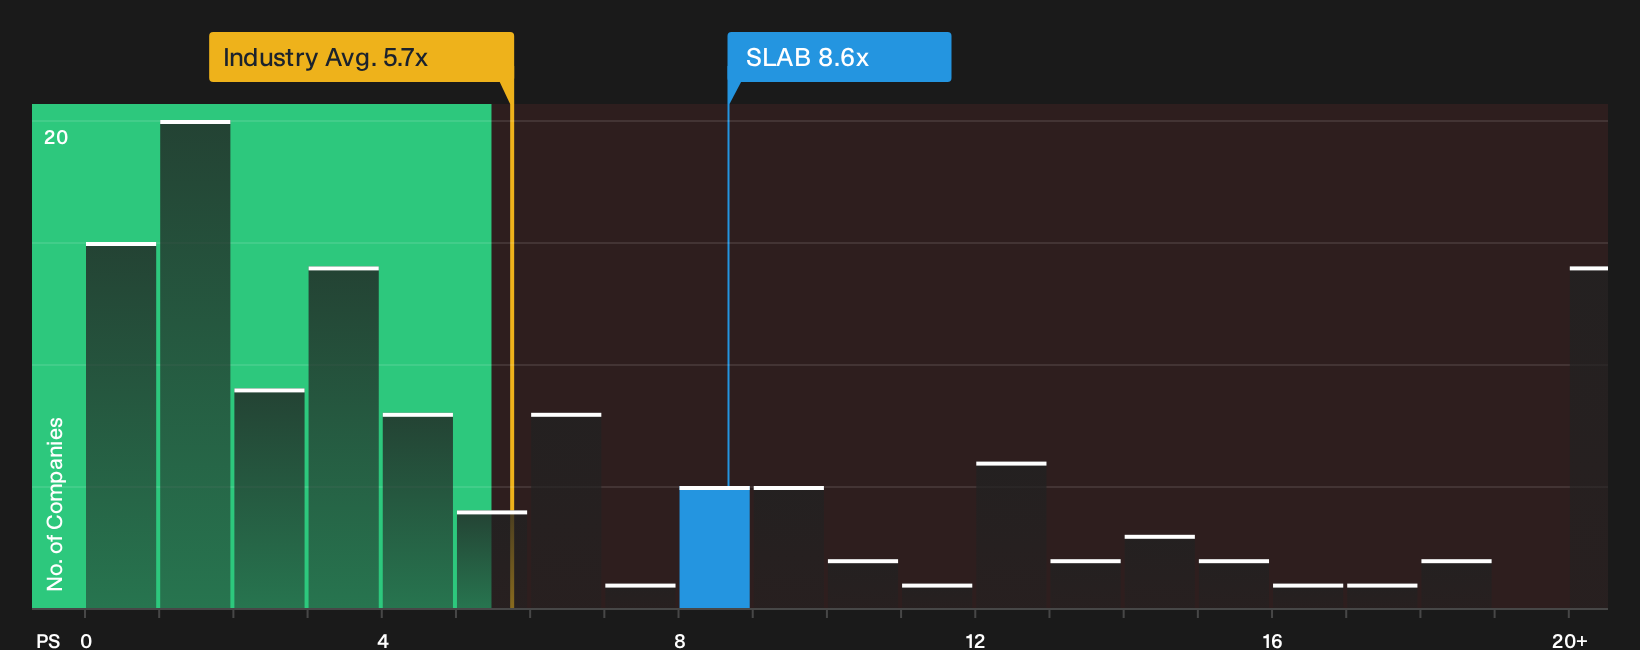
On a pure cash flow model, Silicon Laboratories looks appealing, yet the picture changes when you zoom in on what investors are paying for each dollar of revenue. The stock trades on a P/S ratio of 8.6x, above both the US Semiconductor industry at 5.2x and the peer group at 7.2x, while the fair ratio sits lower again at 5.4x. That gap suggests you are paying a premium today for a business that is still loss making, which raises a simple question: How comfortable are you betting that future execution fully justifies that richer tag?
See what the numbers say about this price in more detail by reviewing the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or balanced opportunity, either way the Silicon Laboratories story is now finely poised. Take a closer look at the data, weigh the trade off between the 1 or more risks and the 1 or more rewards, and then judge the 2 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Silicon Laboratories?
If Silicon Laboratories has sharpened your focus on quality and price, do not stop here. Broaden your watchlist now so you are not late to the next opportunity.
- Target resilience first by reviewing a curated set of 30 resilient stocks with low risk scores that aim to pair steadier fundamentals with controlled risk profiles.
- Hunt for pricing gaps by scanning a 33 high quality undervalued stocks that filters for strong cash flows and balance sheets trading at what may be discounted levels.
- Prioritise durability and quality by checking a list of solid balance sheet and fundamentals (25 results) that highlights businesses with financial footing designed to handle tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com