


EN
Does BOGO Promotion Change The Bull Case For Chipotle Stock?
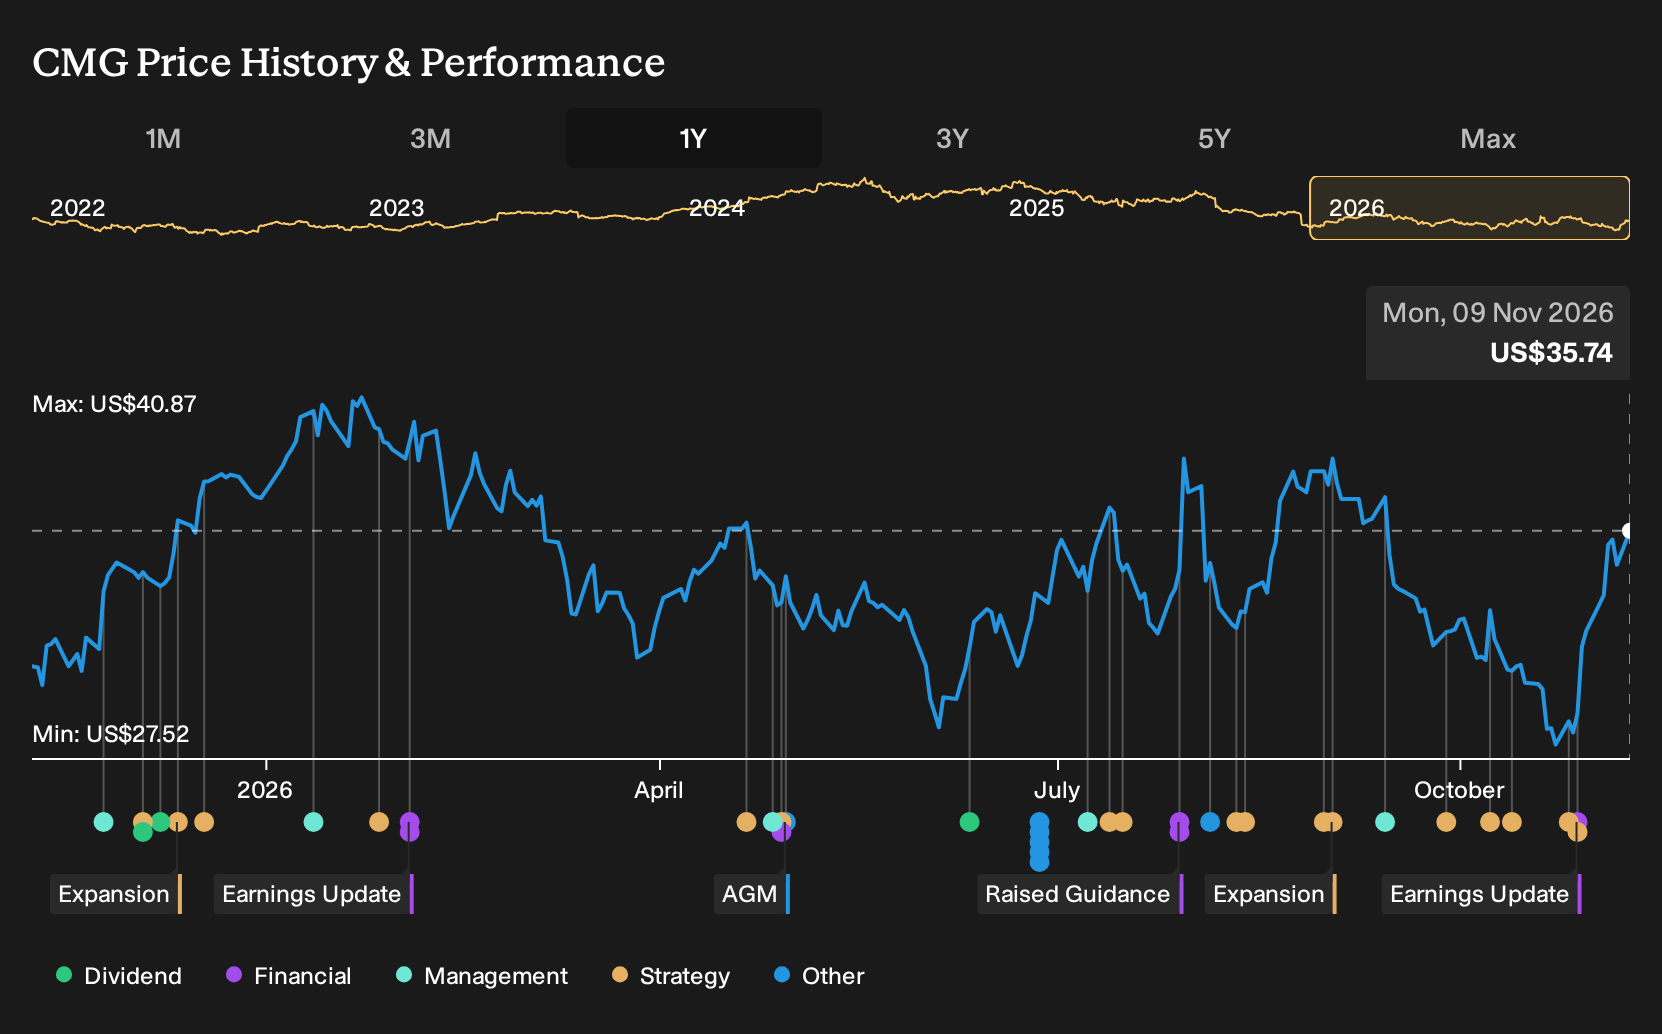
- Chipotle Mexican Grill reported mixed third quarter 2026 results, with revenue of US$3.29b and net income of US$339.87m. The company also announced 2027 expansion plans targeting up to 360 new restaurants in the U.S. and Canada, as well as as many as 25 locations internationally.
- The return of the "Tatted Like a Chipotle Bag" BOGO promotion in partnership with Wiz Khalifa highlights how Chipotle Mexican Grill continues to rely on marketing campaigns that have previously coincided with very strong single-day sales performance to support customer traffic.
- We will now look at how Chipotle Mexican Grill's investment narrative is influenced by this renewed BOGO promotion focused on traffic.
Chipotle Mexican Grill Investment Narrative Recap
To hold Chipotle Mexican Grill, you need to buy into a simple idea. Management is prioritising restaurant openings, digital ordering and promotions to support traffic, even if near term profitability feels choppy. The latest quarter shows revenue at US$3.29b and net income at US$339.87m, so growth spending is coming with some pressure on earnings and margins.
The key near term swing factor remains customer traffic. PTA, a Simply Wall St Community investor who wrote the Narrative, argues the thesis rests on rolling out hundreds of locations while keeping restaurant economics intact. That makes any sign of softer same store trends or sustained cost inflation the biggest operational risk right now.
The most relevant update here is the 2027 expansion plan. Management is guiding for 340 to 360 new Chipotle Mexican Grill restaurants in the U.S. and Canada plus 15 to 25 locations internationally, which keeps growth capital intensive and execution heavy. That pipeline keeps unit growth as a clear operational catalyst for the next few years.
This matters for the BOGO promotion because new stores only work if traffic holds up. The brand leaning on campaigns around events like "Tatted Like a Chipotle Bag" can help fill restaurants while the footprint grows. Investors are effectively watching the same few levers: new unit performance, same store sales and restaurant level margins, to see if this expansion remains sustainable.
PTA values Chipotle Mexican Grill at US$27.88 per share by applying the narrative’s own assumptions of revenue declining 3.0% a year and future profit margins of 12.0%. That framework hinges on Chipotle eventually settling into lower growth but still converting sales into meaningful earnings.
Uncover why Chipotle Mexican Grill's fair value indicates a 22% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the most bearish analysts focus less on promotions and more on Chipotle Mexican Grill’s restaurant level margins. Before this earnings and BOGO news, they were pencilling in revenue of about US$16.4b and earnings of roughly US$1.7b by 2029, which is a more cautious story. Use that as a prompt to compare several viewpoints before deciding how this update might shift your own narrative.
Explore 7 other Chipotle Mexican Grill fair value estimates, including one that suggests as much as 22% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Chipotle Mexican Grill research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for Chipotle Mexican Grill. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Chipotle Mexican Grill's overall financial health at a glance.
Looking for more investment ideas beyond Chipotle Mexican Grill?
Once you have formed a view on Chipotle Mexican Grill, it can help to compare that thesis with other businesses that share similar qualities or very different risk profiles. The Simply Wall St Screener surfaces groups of companies that meet clear financial filters so you can pressure test your thinking and spot alternatives that better fit your own goals and risk comfort.
- If you care most about balance sheet strength and fundamental resilience, start with this list of solid balance sheet and fundamentals (25 results) and see which companies match that filter set.
- For investors hunting for quality at a reasonable entry point, you may want to review a 33 high quality undervalued stocks that combines solid fundamentals with more appealing prices.
- If you prefer resilient profiles with less volatility in mind, scan through a 30 resilient stocks with low risk scores that screens well on Simply Wall St's risk scoring.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com