


EN
ConocoPhillips (COP) Stock Trades at a Discount to Its Earnings
ConocoPhillips has delivered a strong run in recent years, and after that climb, the live question is whether today's share price still lines up with the earnings that support it. With fresh headlines around higher shareholder payouts and project progress, the focus now shifts to what investors are really paying for each dollar of profit.
- Over the past 5 years, ConocoPhillips has returned 119.5%, which puts real weight on whether the current valuation can be grounded in its earnings power rather than just share price momentum.
- Recent news on higher dividends, sizable share repurchases, and ongoing development projects signals that management is leaning on cash generation and future production plans, which can influence how sustainable its earnings base looks against the current P/E multiple.
- Your read on ConocoPhillips is one view; the desks covering it have another. See what analysts think ConocoPhillips's shares could be worth.
The issue now is whether the stock's latest price fully reflects, or potentially stretches beyond, what ConocoPhillips is earning today and is expected to earn in the years ahead.
If you are weighing ConocoPhillips against other opportunities linked to the same theme of earnings power and shareholder returns, it can help to see how it stacks up beside 33 high quality undervalued stocks.
Does ConocoPhillips Look Undervalued on Earnings?
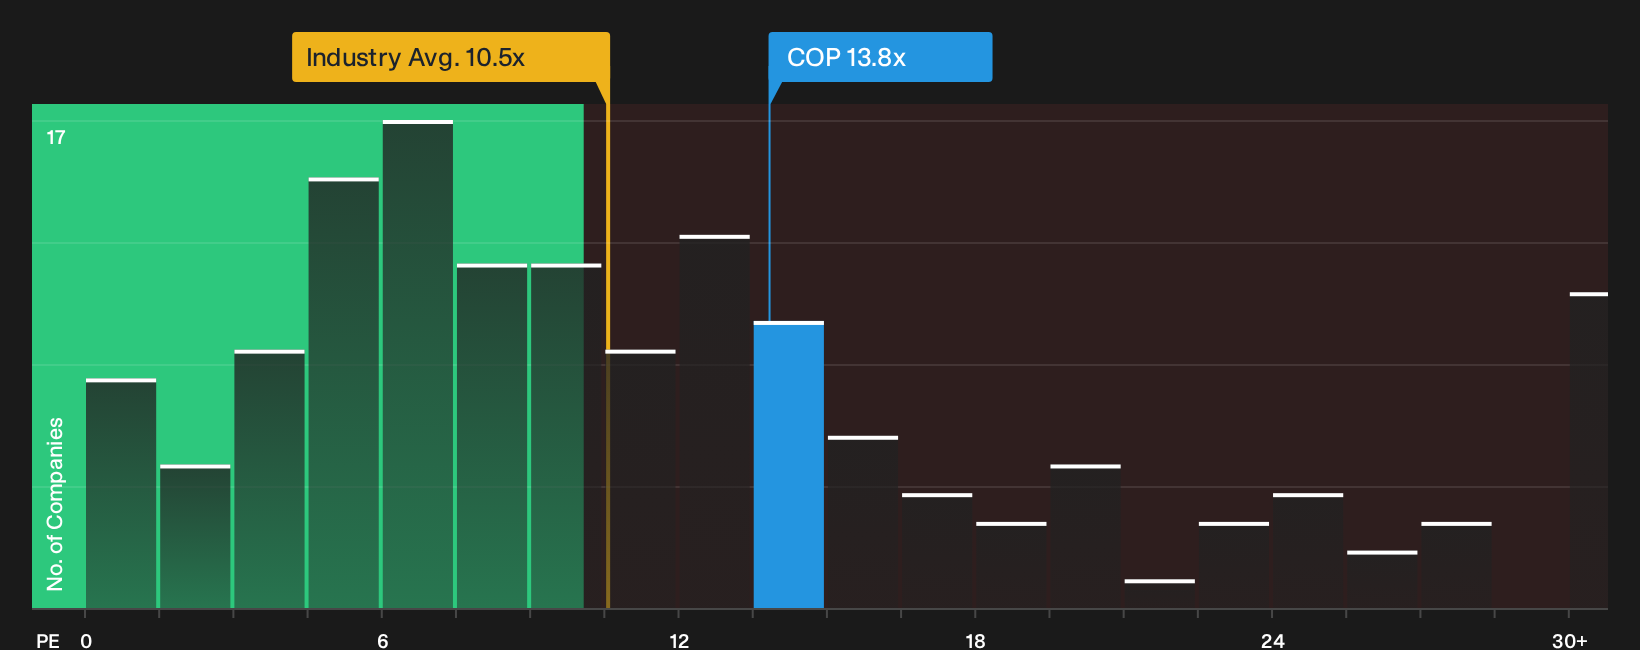
P/E is a useful lens for ConocoPhillips because the market is clearly keying off earnings power and cash generation. On this measure, the stock trades at about 13.8x earnings, very close to the 14.0x peer average for other large players, and above the broader Oil and Gas sector on roughly 10.5x. Against a more tailored fair value yardstick that factors in ConocoPhillips' size, profitability and risk profile, the current P/E appears undervalued relative to that metric.
Because the latest quarterly update showed strong profits and higher shareholder payouts, the share price already reflects a lot of good news, yet the P/E still sits below what that fair value framework indicates investors might typically pay for this earnings stream. That leaves the ratio pointing to a discount versus what the model suggests ConocoPhillips could justify on its reported performance and industry context. Explore the numbers behind ConocoPhillips's P/E valuation.
The ConocoPhillips Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for ConocoPhillips leaves off by explaining which paths for future growth, margins and earnings would need to occur for the shares to appear meaningfully cheaper or more expensive than they do today. Each narrative links a specific fair value to a clear storyline about ConocoPhillips' potential catalysts and key risks so you can monitor over time which version of events actually unfolds.
Bulls in ConocoPhillips see long life projects and LNG shaping a bigger cash engine, while bears focus on how concentrated those same bets have become.
Bull case: 10% undervalued
The analyst consensus Narrative on Simply Wall St ties the upside view to major LNG and oil projects plus lower breakeven targets.
"The company’s outlined path to a $7b free cash flow uplift by 2029, helped by lower free cash flow breakevens from the mid US$40s WTI range today to the low US$30s, suggests that margin expansion and higher earnings power are still ahead of what recent results fully capture…"
Discover why this Narrative puts ConocoPhillips at 10% undervalued.
Bear case: roughly fairly valued
The bearish analyst Narrative on Simply Wall St argues that long cycle spending and execution risk already justify a more cautious stance.
"The plan to drive a $7b free cash flow inflection by 2029, including around $1b of incremental free cash flow per year from 2026 to 2028 and a further $4b from Willow, concentrates expectations on a narrow set of large projects…"
Explore why this Narrative puts ConocoPhillips at roughly fairly valued.
One more angle on ConocoPhillips that could change the story
Before you close the file on ConocoPhillips, it is worth asking who is actually steering the business, how their rewards are structured, and whether that pay design truly lines up with your interests. See who runs ConocoPhillips and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com