


EN
Talos Energy (TALO) Stock Could Trade Below Fair Value After A 42% Run
Talos Energy has delivered a 41.7% gain over the past year, even after a recent pullback, which puts fresh attention on a simple question for investors. Is the current share price at around US$14.62 properly supported by what the business generates in sales?
- The stock is up 41.7% over the past 12 months, so anyone looking at Talos Energy today has to ask whether that move lines up with what its revenue base can justify.
- Recent deals to buy deepwater assets and sell older fields, along with higher expected production and trimmed capital spending, may support a different sales and cash flow profile than investors were modelling a year ago.
- Your read on Talos Energy is one view; the desks covering it have another. See what analysts think Talos Energy's shares could be worth.
The issue now is whether the current market value of Talos Energy makes sense when measured against its sales.
If you want more than a single stock to analyse against sales, a focused screen of other companies trading on their top line is a useful second step. You can start with 33 high quality undervalued stocks.
Is Talos Energy a Bargain on Sales?
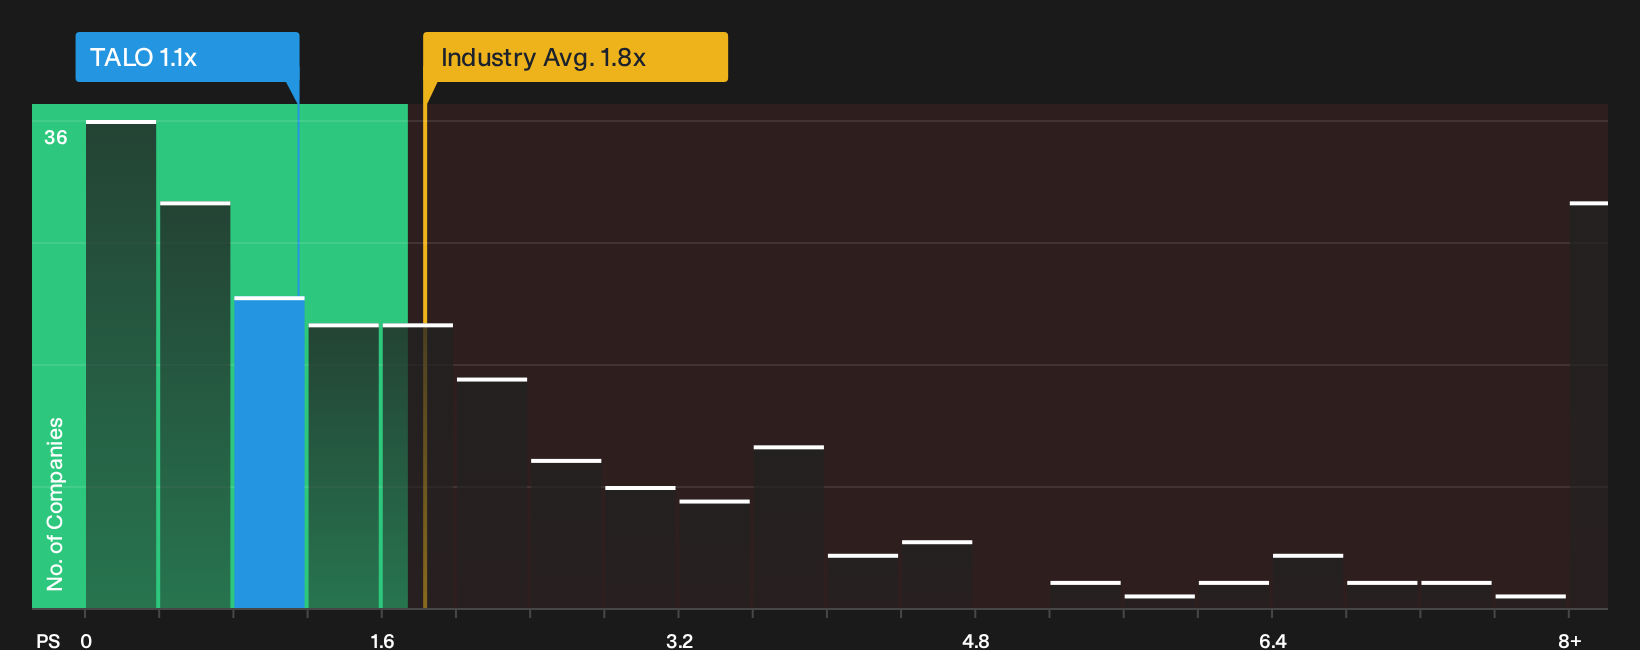
P/S suits Talos Energy because investors are currently focused on what each dollar of revenue could mean for future cash generation after recent asset moves. On this lens, the stock trades at about 1.1x P/S, which is below the wider oil and gas industry on roughly 1.8x and under the peer group near 2.2x. That points to a discount valuation on sales even though the company is now being valued more keenly after its recent share price run.
Because the fair multiple for Talos Energy screens higher than both those simple averages, the current 1.1x P/S sits below what the model would suggest for a business with these margins, growth expectations and risk profile. Despite the Shell asset acquisition and raised production guidance supporting stronger recent EBITDA, the market is still pricing Talos at a lower sales multiple than those benchmarks would imply. This leaves readers weighing whether the gap reflects caution on execution or a potential opportunity. Explore the numbers behind Talos Energy's P/S valuation.
The Talos Energy Narrative: What Would Justify Today's Price?
Narratives for Talos Energy pick up from this valuation gap and outline which combinations of future growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today. Each scenario is framed as a thesis about Talos Energy's business that can be tracked over time so you can see how the underlying logic holds up as new information arrives.
One of the top narratives on Talos Energy: 32% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The primary requirement for this thesis is successful integration and optimization of the Na Kika and Coulomb interests, together with ongoing cost and capital discipline…"
Discover why this Narrative puts Talos Energy at 32% undervalued.
Before acting on Talos Energy's valuation, look at who is steering the ship
Numbers only tell part of the Talos Energy story, because the people making capital calls and how they are rewarded can push outcomes in very different directions. See who runs Talos Energy and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com