


EN
PPL (PPL) Stock Looks About Right With Earnings Doing The Heavy Lifting
PPL Corporation has delivered a powerful share price run over the past few years, and the latest investment plans and earnings targets keep attention firmly on what buyers are really paying for. With the stock now around US$35.70, the question is whether that price can be squared with what PPL earns today and what it is aiming to earn in the years ahead.
- PPL has returned about 58.0% over the past 3 years, which puts real pressure on the current earnings profile to carry that kind of performance story forward.
- The recently announced US$25b capital plan and higher long term earnings ambitions can reshape how investors think about the utility's future profit base and the level of earnings needed to support today’s valuation.
- There is a second opinion on PPL worth weighing. See what analysts think PPL's shares could be worth.
The issue now is whether PPL's current share price is properly supported by its earnings once you line it up against the Fair Ratio benchmark.
For a wider view on how other power and grid players are priced on similar themes, compare PPL with 42 power grid technology and infrastructure stocks.
Does PPL Look Fairly Valued on Earnings?
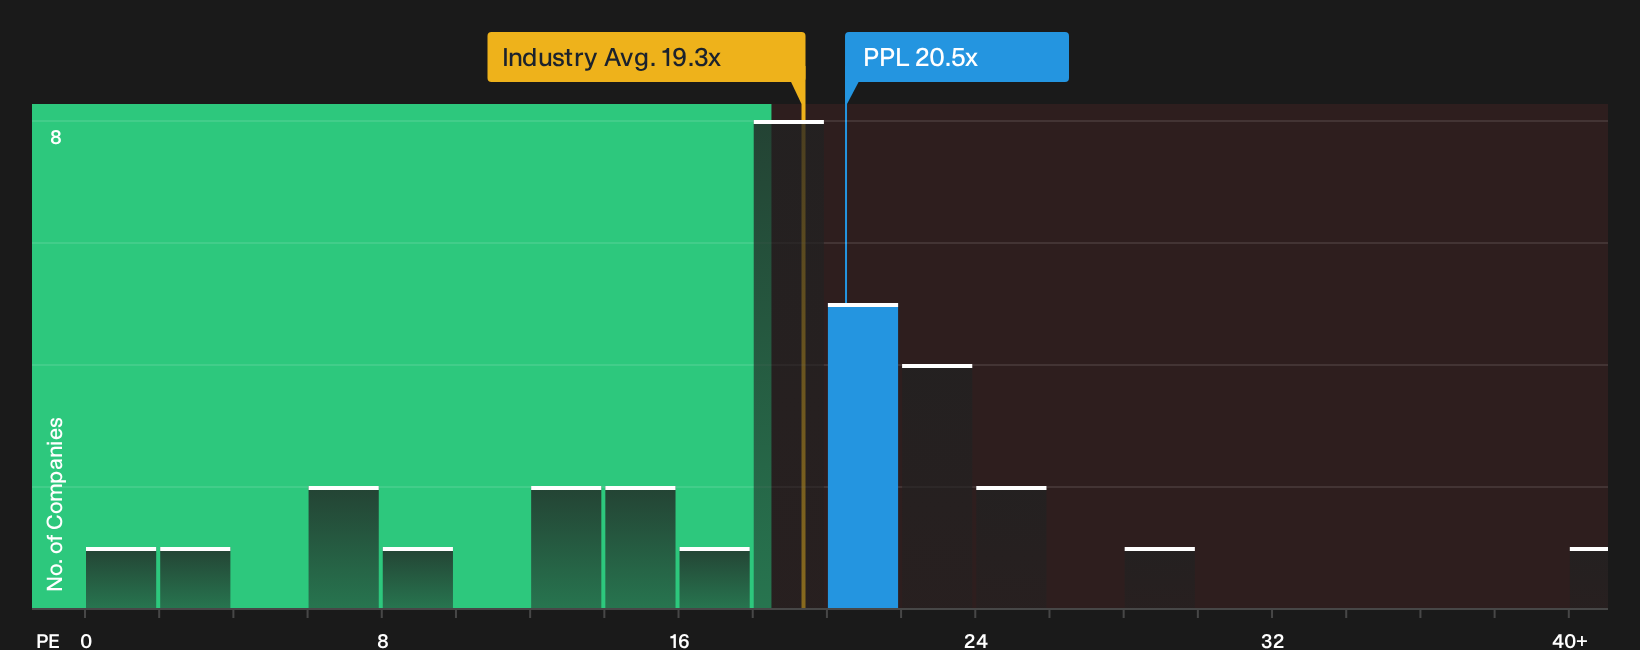
The P/E ratio tends to matter most for a regulated earner like PPL because profits and allowed returns drive the story more than headline revenue. At around 20.5x earnings, PPL trades above the peer average of roughly 14.2x and also above the Electric Utilities sector on about 19.3x, which indicates the market is willing to pay a premium versus many other listed utilities.
That gap aligns with the Fair Ratio framework, which suggests PPL stock is broadly in the right ballpark rather than clearly cheap or expensive on earnings alone. Because the recent Q3 2026 update set out higher long term EPS growth targets and a US$25b capital plan, the current multiple effectively prices in that more ambitious profit path instead of treating the recent performance as a one off. Investors weighing the shares now need to decide how much conviction they have in those plans holding up over the coming years. Explore the numbers behind PPL's P/E valuation.
The PPL Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the PPL valuation puzzle leaves off, by spelling out which paths for PPL's future growth, margins and earnings would need to occur for the stock to be worth materially more or less than it is today. They sit on the company’s Community page so you can see how each potential storyline links a specific fair value to concrete catalysts and risks, and then judge over time which version of events appears to be taking shape.
One of the top narratives on PPL: 11% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The current valuation implies the market is discounting PPL's load and capex pipeline and is not fully pricing in the earnings contribution that management targets..."
Discover why this Narrative puts PPL at 11% undervalued.
One last PPL check that sits beside the share price
PPL's earnings targets tell only part of the story, because the people setting those goals and how they are rewarded can strongly influence what actually happens over time. See who runs PPL and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com