


EN
Is Ramelius Resources (ASX:RMS) Undervalued As Its Share Buyback Puts Focus On Mt Magnet?
Ramelius Resources (ASX:RMS) has initiated a substantial share buyback that puts capital management in the spotlight, with the Mt Magnet hub and cost discipline now central to how investors think about future earnings power.
Ramelius Resources has seen momentum pick up recently, with a 16.62% 7 day share price return and a 6.22% 90 day share price return at A$3.93. Longer term total shareholder returns of 164.20% over three years and 144.59% over five years point to a story that has rewarded patient holders, even as the year to date share price return is down 7.09%.
Scan the gold sector for other producers combining capital returns with disciplined cost control by reviewing our hand picked 34 elite gold producer stocks alongside Ramelius Resources.
Ramelius Resources trades at a steep discount to both analyst targets and estimated fair value after announcing the buyback. Is the gap a genuine opportunity, or a warning that the market still doubts the story?
Most Popular Narrative: 58.5% Undervalued
On the narrative view, Ramelius Resources lines up with a fair value of A$9.47 against the last close at A$3.93, which puts a big valuation gap in focus according to dazza865, an investor in the Simply Wall St Community who has followed the story for years.
I've been a share holder of this company for over 15 years, and seen the share price at 7c. With incremental share purchases, I've accumulated a 6 figure holding. It's been one of my set and forget 'Buffet' stocks. Each read of the annual report maintains my faith in its growth strategy, where a disciplined board of directors with a very professional management team have executed a promised vision. I've seen the share price punch through $5 and I've taken some profit. However, the journey to greater riches is still on, with continued exploration, acquisitions and sensible operations, so while I have time before retirement, I'll keep riding the outlook.
See why 7 investors see Ramelius Resources as 59% undervalued.
Result: Fair Value of A$9.47 (UNDERVALUED)
Still, the Ramelius Resources story can be knocked off course if cash returns crowd out exploration spend or if cost discipline at Mt Magnet slips and margins tighten.
Find out about the key risks to this Ramelius Resources narrative.
Another View on Ramelius Resources Valuation
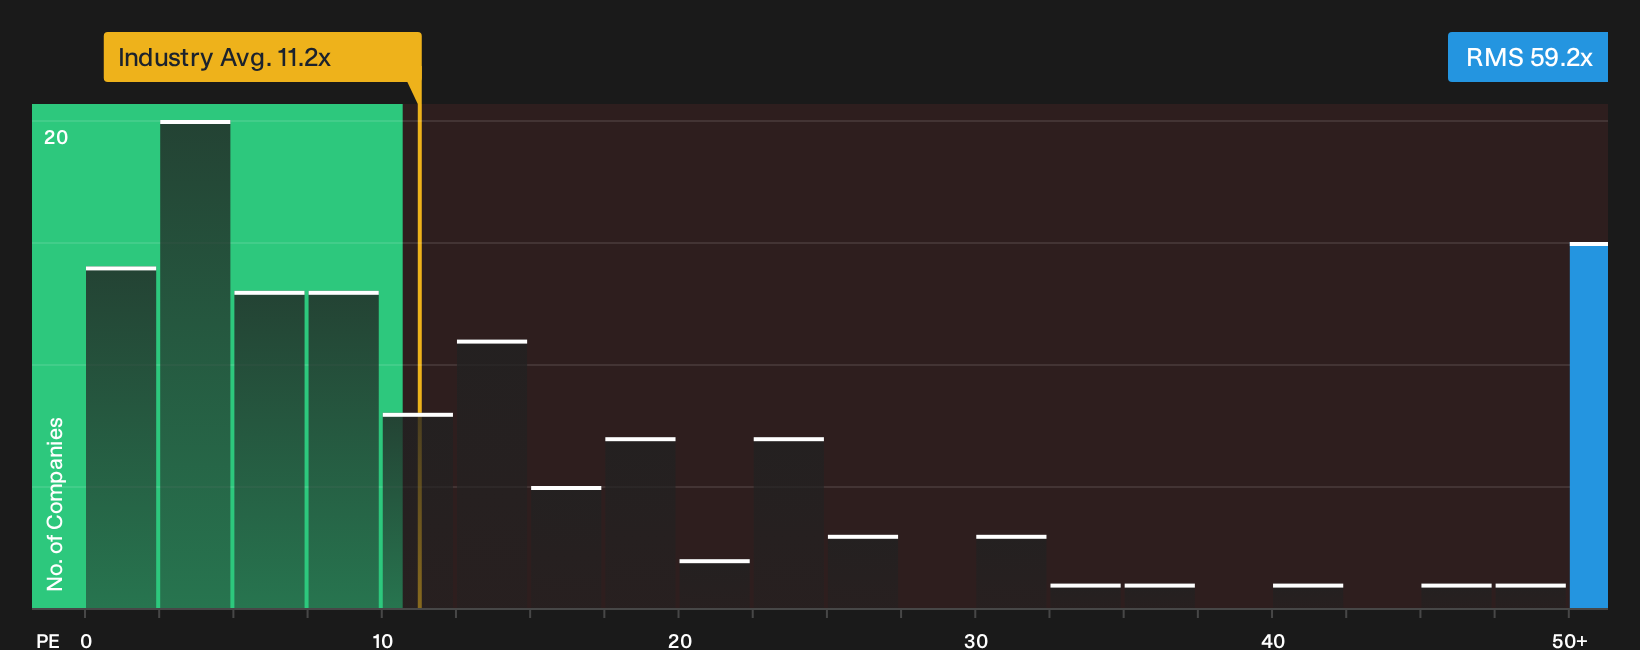
The first narrative points to Ramelius Resources looking 58.5% undervalued. On simple P/E maths, the picture is very different. RMS trades on a P/E of 59.2x, while the fair ratio sits at 22.3x and peers around 16x. This implies a rich tag and more valuation risk if sentiment cools.
That kind of premium can reflect confidence in future earnings, yet it also leaves less room for mistakes if margins or production disappoint. If the multiple drifts back toward the fair ratio or peer levels, what does that mean for anyone buying at today’s price?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Ramelius Resources valuation and sentiment can be confusing, so move quickly, test the numbers yourself, and weigh both sides of the story with 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Ramelius Resources?
If Ramelius Resources has your attention, do not stop here. Broaden your watchlist with other high quality ideas filtered by fundamental strength, value, and resilience.
- Target dependable income and shortlist companies offering robust payouts by scanning our focused set of 5 dividend fortresses.
- Hunt for mispriced opportunities and compare Ramelius Resources with a hand picked group of 14 high quality undiscovered gems.
- Prioritise capital preservation and stress test your portfolio against market shocks with a curated pool of 6 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com