


EN
Is Donaldson Company (DCI) Undervalued After Its Alpha Pore Filtration Platform Launch?
Donaldson Company (DCI) has put its filtration expertise in the spotlight with the launch of Alpha-Pore, a sterile filtration platform designed to extend filter service life and sustain process performance.
Recent trading has been mixed for Donaldson Company. The 1 day share price return of 4.60% and 7 day gain of 3.38% suggest short term momentum has picked up, even though the 90 day share price return declined 8.98% and the year to date move is down 1.91%. Over a longer horizon, total shareholder return of 1.74% over 1 year and more than 50% across both 3 and 5 years indicates a steadier compounding story behind the latest Alpha-Pore announcement and the recent US$250m senior notes agreement.
Scan other high-efficiency filtration and industrial plays that are moving on similar catalysts with our curated list of list of solid balance sheet and fundamentals (25 results).
After the Alpha-Pore news and a short burst of gains, Donaldson Company now presents a familiar fork in the road. Does it make more sense to act on this move, or to wait for a cleaner entry as valuation becomes clearer?
Most Popular Narrative: 12% Undervalued
Against Donaldson Company’s last close at $88.21, the analyst consensus Narrative on Simply Wall St anchors fair value at $100.40, implying a double digit discount based on long range cash flow and earnings assumptions. That framework leans heavily on how filtration mix and aftermarket exposure shape both future profitability and what investors might be willing to pay for those earnings.
Shift toward higher technology and high purity filtration in areas such as disk drives, process filtration, microelectronics, liquid cooling and advanced power generation is increasing content per asset and mix of more complex products, which can support higher average selling prices and margin mix and feed into both revenue and operating margin over time.
See why 12 investors see Donaldson Company as 12% undervalued.
Result: Fair Value of $100.40 (UNDERVALUED)
Still, a slower than expected recovery in higher margin bioprocessing and any prolonged drag from Industrial Solutions inefficiencies could challenge the Donaldson Company undervaluation story.
Find out about the key risks to this Donaldson Company narrative.
Another View: What P/E Says About Donaldson Company
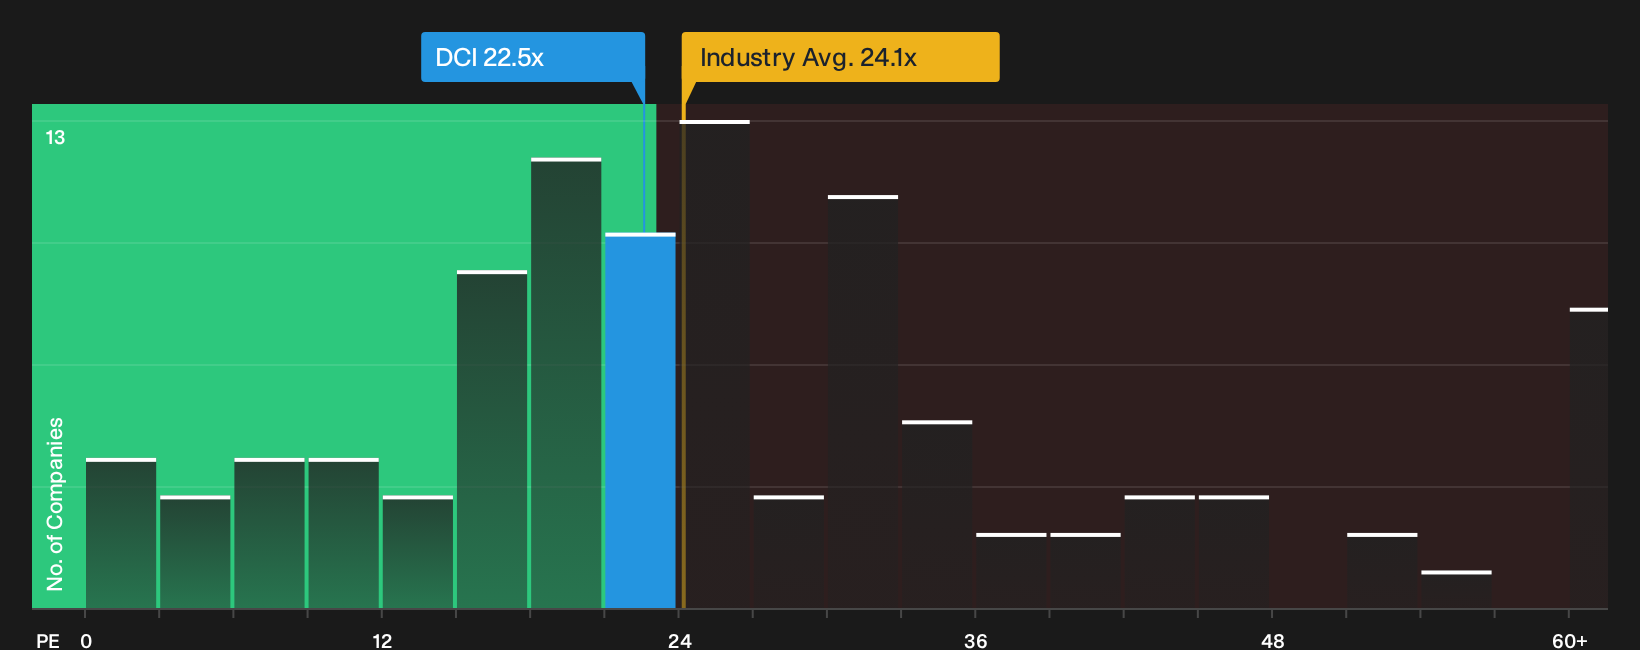
The cash flow work on Donaldson Company points to value, yet the P/E picture is more cautious. The stock trades on 22.5x earnings, above an estimated fair ratio of 20.9x. It still sits below the peer average of 27.5x, which leaves a thinner margin of safety if sentiment shifts.
For investors weighing that trade off between cash flow upside and earnings multiples, the valuation breakdown helps frame how much mispricing might really be on the table See what the numbers say about this price — find out in our valuation breakdown..
To see how Donaldson Company stacks up visually against its sector on earnings multiples, review the comparison chart
Next Steps
Curious whether the balance of optimism and concern around Donaldson Company matches your own read of the situation? Move fast and pressure test the upside and downside in the full breakdown of 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Donaldson Company?
If Donaldson Company has your attention, do not stop here. Use the same disciplined lens to hunt for other opportunities before the crowd catches on.
- Target resilient opportunities by focusing on companies with stronger financial footing and lower risk profiles through the 30 resilient stocks with low risk scores.
- Chase value by zeroing in on companies that pair quality fundamentals with attractive pricing using the 33 high quality undervalued stocks.
- Build a future income stream by focusing on higher yielding businesses with sturdier payout profiles through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com