


EN
Wintrust Financial (WTFC) Fair Value Was Raised, Is The Stock Still Cheap?
Argus recently lifted its fair value estimate for Wintrust Financial (WTFC), which is putting fresh attention on how this regional bank fits into portfolios that already hold U.S. financials.
Wintrust Financial’s recent fair value upgrade comes as the share price trades at US$154.92, with a 30-day share price return of 8.15% and a year-to-date gain of 8.59%. This contrasts with a 90-day decline of 4.43%, while the 1-year total shareholder return of 19.39% and 3-year total shareholder return above 2x highlight stronger longer-run momentum than the last quarter implies.
Compare Wintrust Financial’s re-rated profile with a hand-picked group of regional banks and financials using the list of solid balance sheet and fundamentals (25 results) to see how its metrics stack up against peers.
Bulls see Wintrust Financial’s upgraded fair value and double digit multi year returns as proof the rerating has room to run. Bears see a regional bank that has already moved. Which story do the current valuation markers back up?
Most Popular Narrative: 12% Undervalued
Wintrust Financial’s analyst consensus Narrative on Simply Wall St pegs fair value at $176.20 against the latest close of $154.92. This frames the upgraded Argus view inside a broader valuation gap that still appears open.
Organic loan and deposit growth across commercial, premium finance, mortgage and specialty lending segments is building a larger base of earning assets, which directly supports revenue and earnings.
Growth in noninterest income streams such as mortgage banking, wealth management and insurance premium finance is building a more balanced revenue mix. This can reduce reliance on spread income and support steadier total revenue and earnings.
See why 1 investors see Wintrust Financial as 12% undervalued.
Result: Fair Value of $176.20 (UNDERVALUED)
Still, the Wintrust Financial story can break if competition further squeezes loan pricing or if higher technology and branch spending erodes profitability more than expected.
Find out about the key risks to this Wintrust Financial narrative.
Another View: Wintrust Financial Through The P/E Lens
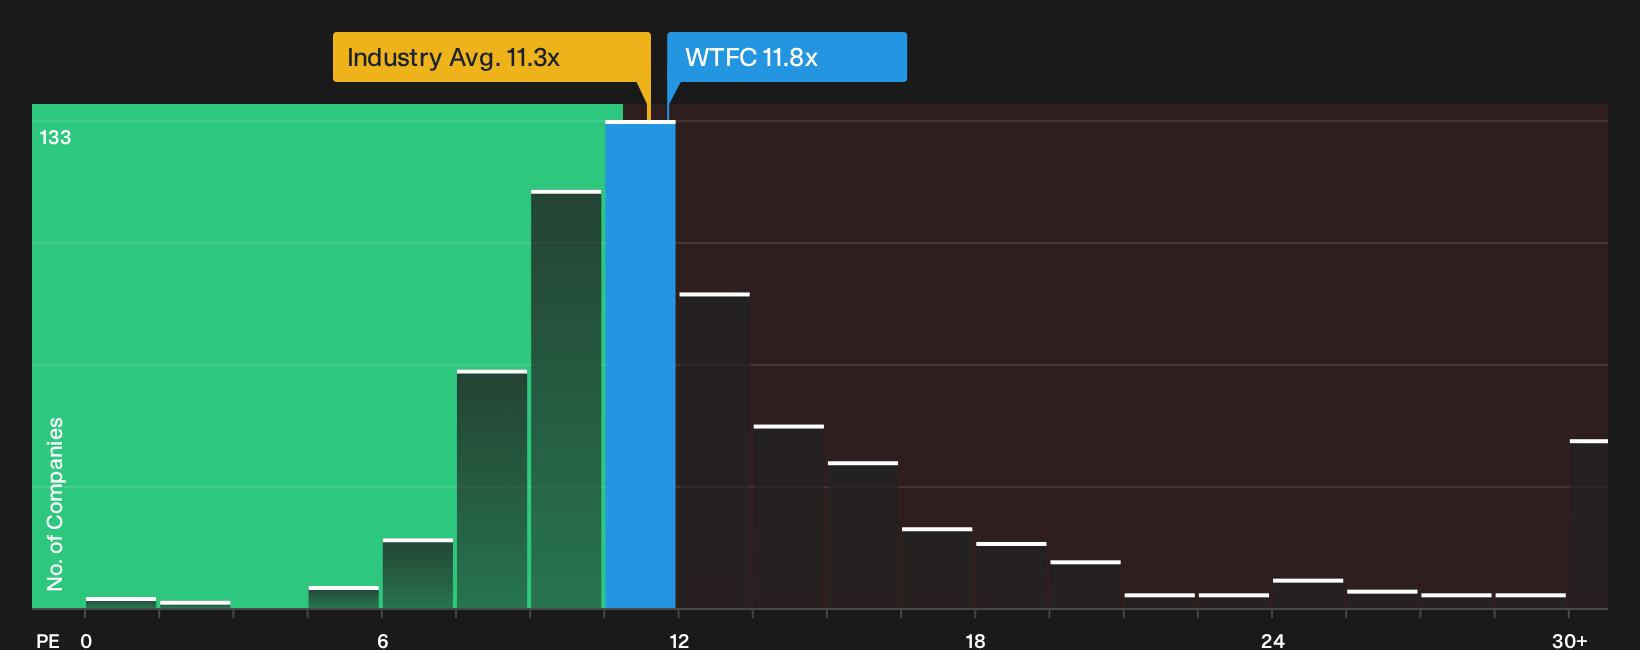
The SWS DCF model points to upside for Wintrust Financial, yet the simpler P/E yardstick sends a cooler message. The stock trades on 11.8x earnings versus 11.3x for the wider US Banks group and a fair ratio of 12.5x. That mix hints at limited downside on multiples, but it also raises the question of how much upside is already priced in.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on value and risk can be useful if you test them yourself and act before the next round of opinions lands. To see both sides of the story in one place, review the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Wintrust Financial?
If you only focus on Wintrust Financial, you could miss other opportunities with strong fundamentals, different risk profiles, or more income focused potential.
- Target stronger balance sheets by reviewing the list of solid balance sheet and fundamentals (25 results) and see which businesses pair financial resilience with consistent fundamentals.
- Hunt for mispriced opportunities using the 33 high quality undervalued stocks to spot companies where quality metrics and current pricing are out of sync.
- Build a steadier income stream by scanning the 6 dividend fortresses and focus on businesses offering higher yields with support from their financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com