


EN
Teledyne (TDY) Stock Looks Reasonable Based On Cash Flow
Teledyne Technologies has delivered a strong run over the past few years, which puts a spotlight on whether the current share price lines up with the cash flows the business is expected to generate. With the stock recently closing at US$643.34 and new contract wins in the spotlight, the question now is how well that market value matches the cash the company can produce over time.
- Over the past 3 years Teledyne Technologies has returned 67.4%. This makes the link between that track record and the durability of its future cash flows a central issue for anyone looking at the valuation today.
- The recent subcontract for Next Generation Interceptor ground support equipment and expanded gas detection capabilities at Teledyne FLIR can influence expectations for long term project revenues, capital demands and the timing of cash inflows across the group.
- Prefer to judge Teledyne Technologies on earnings? See why Teledyne Technologies's 28.8x P/E tells a different valuation story.
The stock's next move may depend on whether those projected cash flows, when valued through the Discounted Cash Flow (DCF) lens, appear sufficient to justify where Teledyne Technologies trades today.
If you want a wider set of ideas with a similar cash flow focus, a targeted screen of resilient balance sheet plays can be a useful second starting point for research such as solid balance sheet and fundamentals stocks screener (25 results).
Is Teledyne Technologies Fairly Priced on Cash Flow?
The Discounted Cash Flow (DCF) model here weighs the cash Teledyne Technologies may return to shareholders against the price you pay today. Latest twelve month free cash flow sits at about $1.16b, and the projection for the early 2030s points to a business assumed to be growing rather than shrinking its cash generation.
Those cash forecasts, when discounted back and compared with the share price of US$643.34, suggest the estimated intrinsic value is broadly in line with where the stock trades. The new Next Generation Interceptor ground support subcontract helps explain why the market is comfortable valuing Teledyne Technologies as a company with cash flows that need to keep grinding higher rather than one priced for stress. Find out what Teledyne Technologies could be worth using our Discounted Cash Flow (DCF) estimate.
The Teledyne Technologies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Teledyne Technologies valuation puzzle leaves off. They spell out which assumptions on Teledyne Technologies' growth, profitability and earnings power would need to hold for the share price to sit meaningfully above or below today's level. Each one treats fair value as a thesis about the business that you can revisit over time rather than a one off snapshot. They live on Simply Wall St's Community page.
One of the top narratives on Teledyne Technologies: 15% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Deep positions in high reliability sensing and imaging niches where Teledyne Technologies is often a top supplier are supporting pricing power and contributing to operating margin expansion…"
Discover why this Narrative puts Teledyne Technologies at 15% undervalued.
One more Teledyne Technologies check that sits beside the valuation math
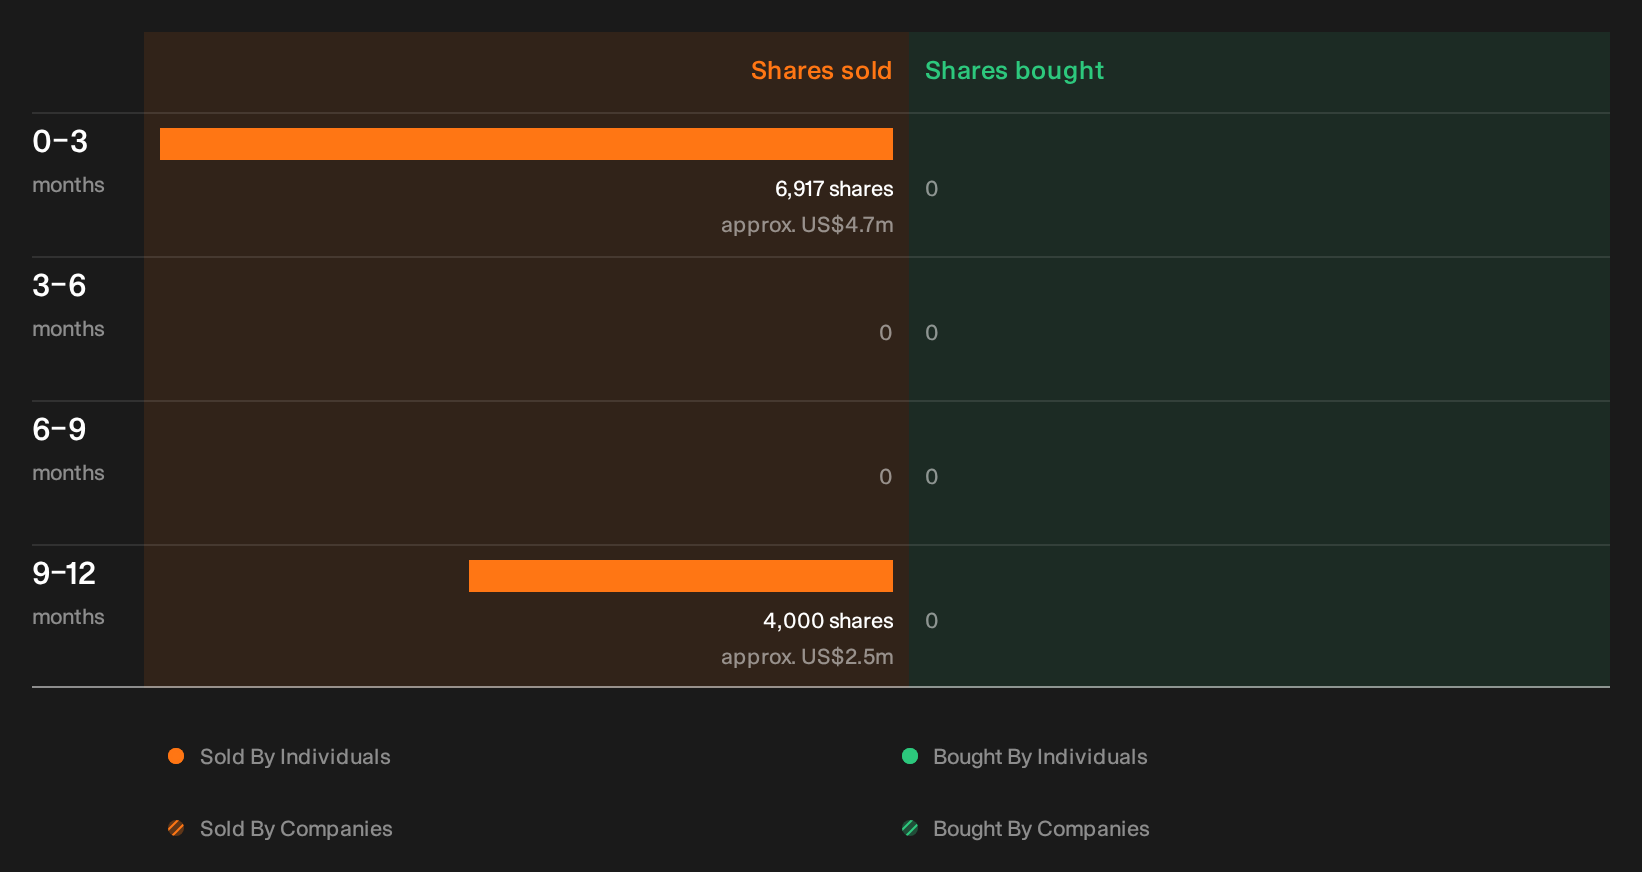
Price and cash flow only tell part of the story, because recent trading disclosures show selling by people inside the business and the identities, sizes and possible read across of those moves are still for you to review. See the recent insider selling flagged for Teledyne Technologies.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com