


EN
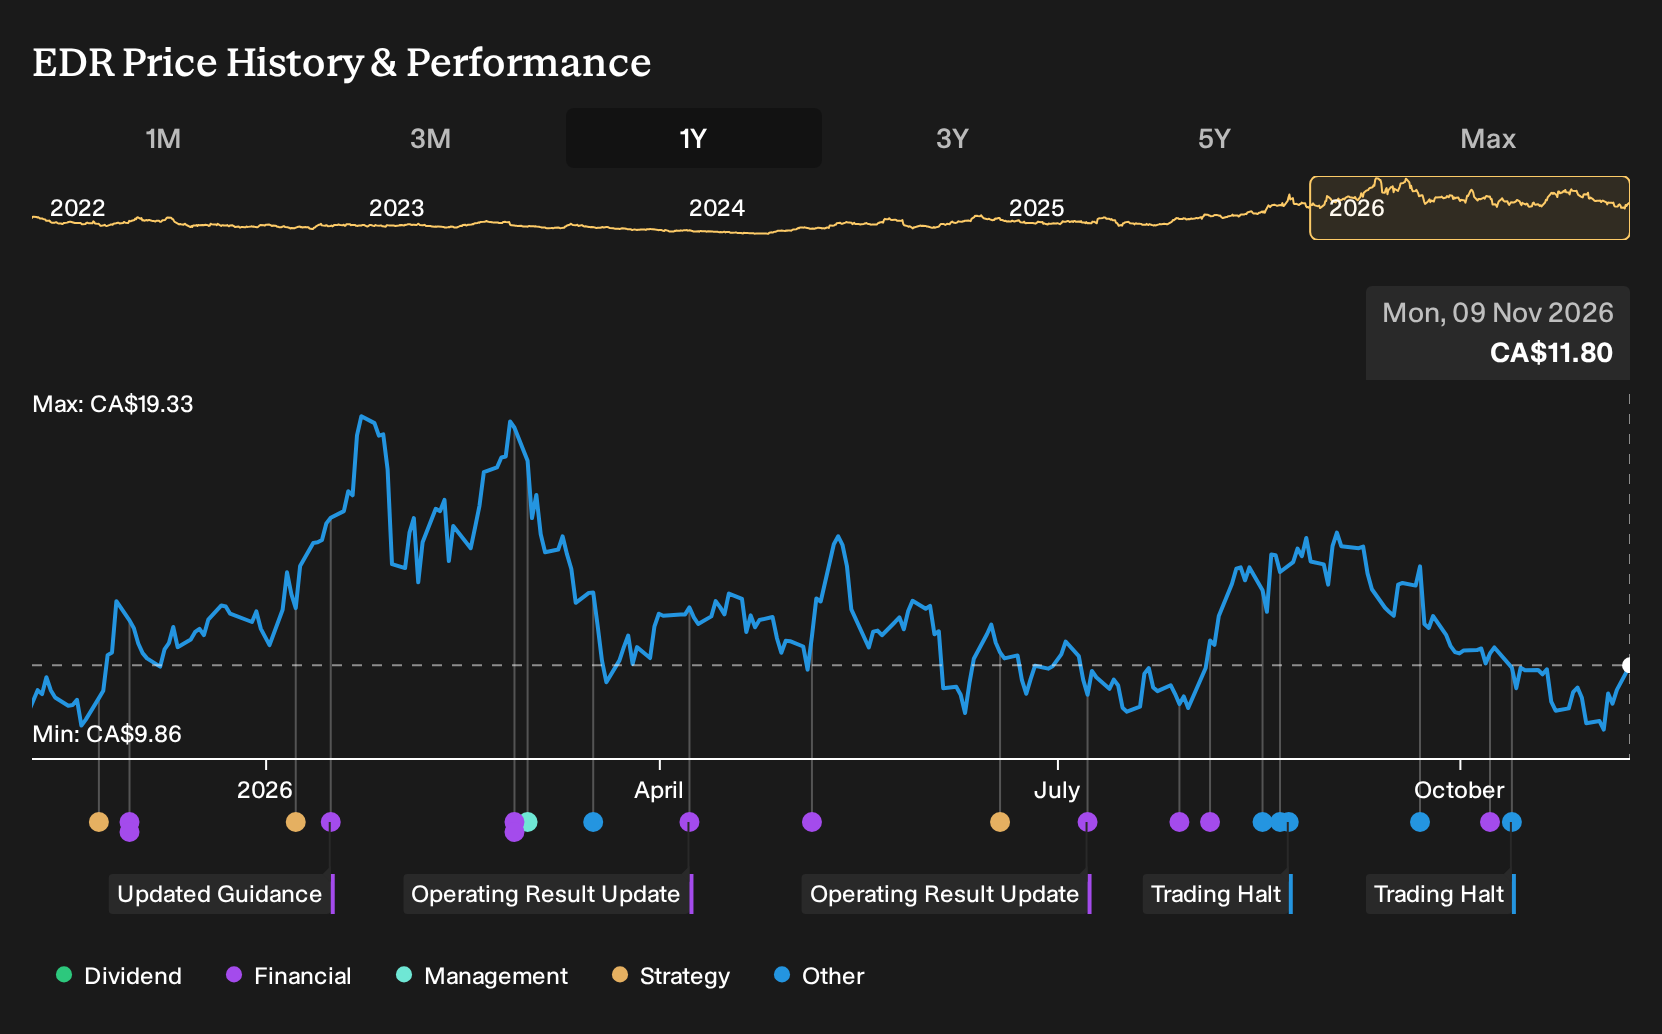
Endeavour Silver Stock Is Up 6.7% What's Changed After Earnings Beat
- Endeavour Silver Corp. reported Q3 2026 sales of US$184.5 million, net income of US$26.4 million, and basic EPS of US$0.09 from continuing operations, with nine month sales of US$606.3 million and net income of US$157.8 million.
- The swing from prior period losses to profitability, alongside higher production guidance and a new revolving credit facility, highlights how Endeavour Silver is relying on stronger operations and added liquidity to support ongoing mine development and project advancement.
- The focus now shifts to how Endeavour Silver's investment narrative aligns with this move back to profitability and raised production guidance.
Scan how Endeavour Silver’s turnaround compares with other precious metals producers by reviewing the hand picked 10 top silver producer stocks in the same space.
Endeavour Silver Investment Narrative Recap
To own Endeavour Silver, you need to be comfortable with a miner that is tying its story to ramp ups at Terronera and Kolpa, plus eventual contributions from Pitarrilla. The analyst consensus narrative on Simply Wall St leans on higher forecast earnings and profitability, so the Q3 move back to profit supports that thesis operationally.
The most important near term swing factor is execution at Terronera and Kolpa while controlling costs. The biggest current risk remains operational setbacks or delays at these assets or project overruns at Pitarrilla, especially given prior liquidity concerns and the impact that higher spending could have on working capital.
The revolving credit facility of up to US$100 million is the announcement that ties closest to the current earnings story. Management now has extra flexibility to fund Terronera commissioning issues, Kolpa integration work, and early Pitarrilla spending without relying only on internal cash generation.
For you as a shareholder, that credit line cuts near term funding stress but also raises the stakes on execution. If Terronera ramp up problems, higher Terronera costs, or Kolpa expansion delays persist, debt usage could rise against cash flows, which would make project delivery and operating reliability even more important catalysts to watch.
Endeavour Silver's current analyst narrative points to revenues of US$807.1 million and earnings of US$207.7 million by 2029, based on forecast revenue growth of 3.1% a year and an increase in earnings of about US$142 million from US$65.7 million today.
Uncover why Endeavour Silver's fair value indicates a 73% potential upside to its current price, a gap that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts frame Kolpa’s long 15 to 25 year mine life potential as the key upside swing factor, not just Terronera ramp up. Before this Q3 report, that group was already penciling in revenue of about US$1.2b and earnings of roughly US$407.5 million by 2029, so this fresh profitability beat could push those narratives even further apart from more cautious views as forecasts get refreshed.
Explore 4 other Endeavour Silver fair value estimates, including one that suggests as much as 627% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Endeavour Silver research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Endeavour Silver. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Endeavour Silver's overall financial health at a glance.
Looking For More Investment Ideas Beyond Endeavour Silver?
After forming a view on Endeavour Silver, it can help to widen the lens and compare it with other opportunities that match your risk tolerance, income needs, and preference for financial strength. The Simply Wall St Screener offers several focused lists that can point you toward stocks with characteristics similar to what you like about Endeavour, or that balance out its risks.
- If you want to balance potential upside with a margin of safety, scan a curated set of 6 high quality undervalued stocks that combine stronger fundamentals with room for the market to close the gap.
- For readers who care most about stability and sleep at night factor, review a group of 9 resilient stocks with low risk scores that score well on resilience and downside protection.
- If quality balance sheets matter most to you, filter for companies in the list of solid balance sheet and fundamentals (5 results) to focus on businesses with stronger financial foundations backing their growth plans.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com