


EN
Earnings Beat Might Change The Case For Investing In Toromont Industries (TSX:TIH)
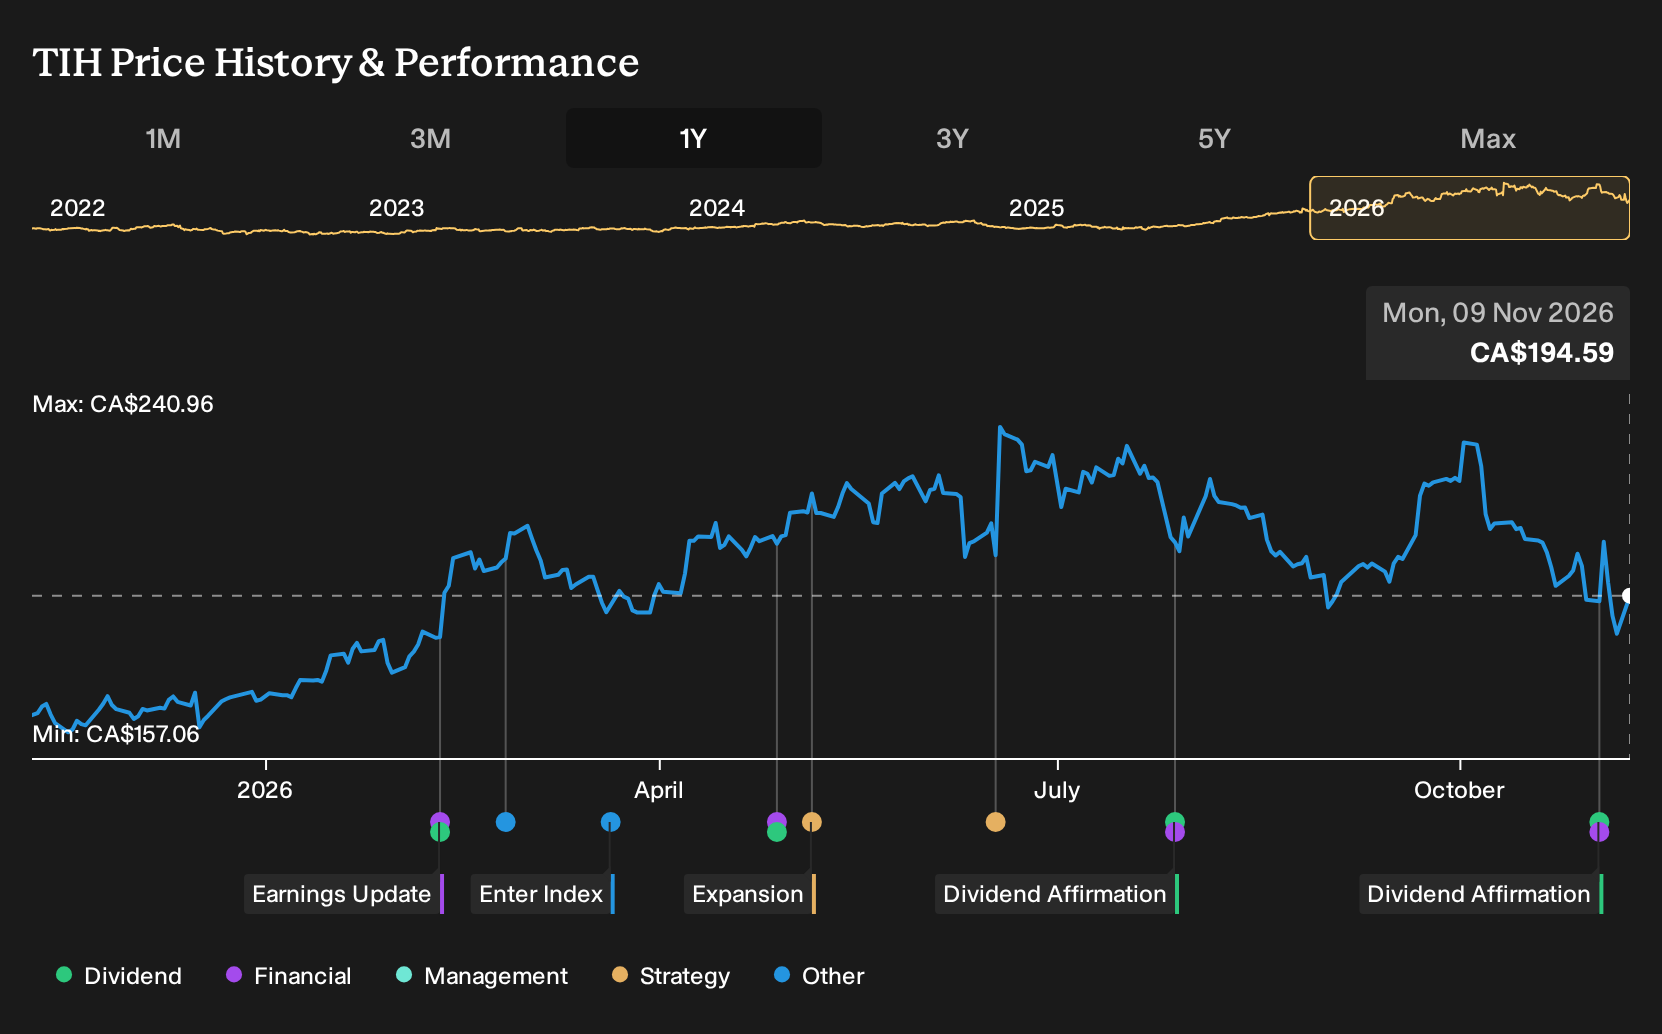
- Toromont Industries reported third quarter 2026 sales of C$1,652.15 million and net income of C$192.11 million, alongside a regular quarterly dividend of C$0.56 per share approved for payment on January 5, 2027, to shareholders of record on December 7, 2026.
- Stronger earnings per share from continuing operations in both basic and diluted terms point to improved profitability, which is relevant for how Toromont Industries balances reinvestment needs with ongoing dividend commitments.
- This article examines how Toromont Industries' stronger earnings per share may reshape the investment narrative around AVL growth and capital deployment.
Toromont Industries Investment Narrative Recap
To own Toromont Industries, you need to believe the AVL power systems opportunity, the Equipment Group backlog and the services push can all convert into durable earnings without eroding margins through cost or execution issues. The latest quarter shows higher sales and earnings per share, which supports that thesis, but does not remove the risk from large non cash AVL related charges mentioned in the analyst consensus Narrative on Simply Wall St.
In the short term, the key swing factor remains how efficiently Toromont Industries ramps AVL capacity while stabilizing CIMCO profitability. CIMCO weakness and any repetition of sharp share price pullbacks are still meaningful risks. The strong quarter helps sentiment and absorbs some financial pressure, yet it does not fundamentally change those operational pressure points.
The most relevant update is the C$0.56 per share quarterly dividend affirmation, payable on January 5, 2027. For you as a shareholder, that matters because it sits alongside a capital intensive AVL build out and ongoing facility investments, which can compete for cash if conditions tighten or earnings momentum slows.
Toromont Industries now has to keep funding AVL expansion, technician hiring and the remanufacturing build while maintaining the dividend track record referenced in the analyst consensus Narrative on Simply Wall St. If AVL execution, CIMCO margins or industrial demand soften at the same time, management may face more difficult trade offs between reinvestment, balance sheet flexibility and maintaining the current payout level.
Toromont Industries' current analyst narrative points to forecast revenue of C$7.6b and projected earnings of C$975.0 million by 2029. This assumes revenue growth of 11.2% per year and an earnings increase of about C$460.0 million from current earnings of C$515.0 million.
Uncover why Toromont Industries' fair value indicates a 27% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about C$247.91 and C$301.34 per share, which already shows how far opinions on Toromont Industries can stretch. When you factor in risks such as persistent AVL related charges, or catalysts such as AVL backlog and capacity projects, you get a wider spread of possible performance paths. Explore the different viewpoints before deciding how you frame the stock.
Explore another Toromont Industries fair value estimate, including one that suggests it could be worth just CA$247.91!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Toromont Industries research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Toromont Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Toromont Industries' overall financial health at a glance.
Looking for more Toromont Industries style investment ideas?
If Toromont Industries has sharpened your focus on quality, cash generation and dividend clarity, it can be useful to widen the lens and scan for other businesses that fit a similar mindset on fundamentals, income or risk control using the Simply Wall St Screener.
- For investors who want income resilience front and center, start with a shortlist of 3 dividend fortresses that can help anchor the more volatile parts of your portfolio.
- If balance sheet strength is your first filter, narrow the field to a list of solid balance sheet and fundamentals (5 results) so you can focus on businesses with room to handle shocks and still fund their plans.
- When the goal is finding opportunities the market may be overlooking, scan a focused 7 high quality undiscovered gems and see which stories deserve a closer look next.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com