


EN
Huntington Ingalls Stock Is Up 5.4% What's Changed After Strong Earnings
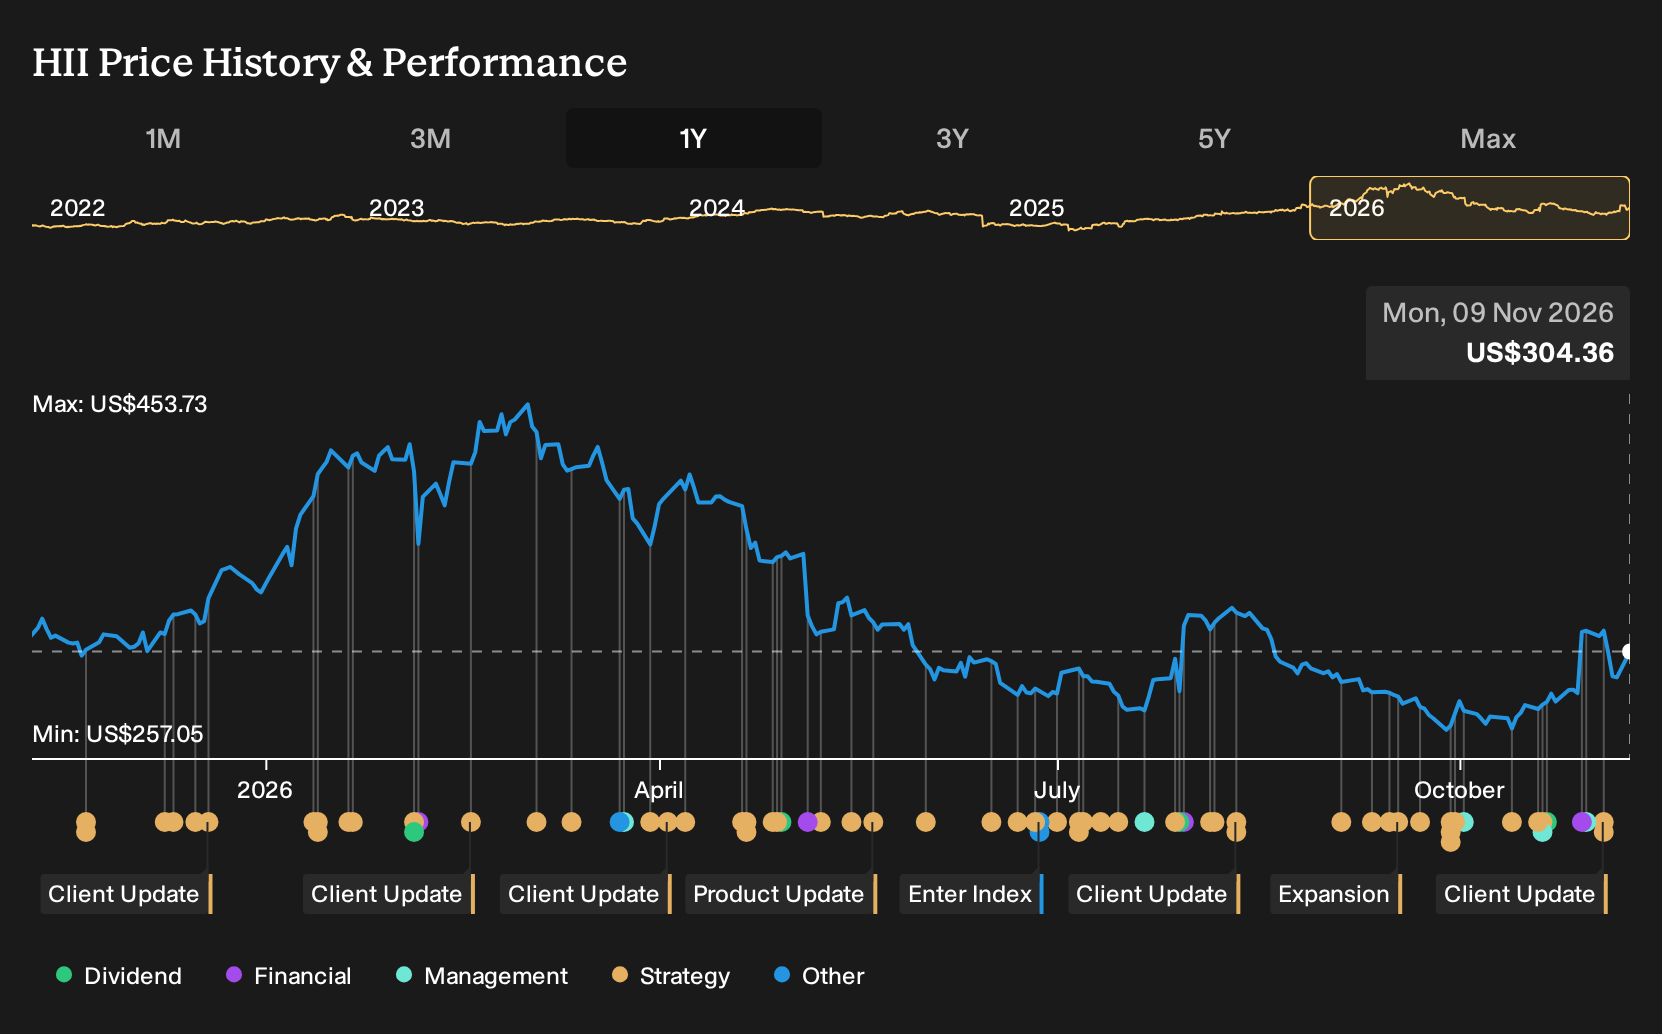
- Huntington Ingalls Industries reported third quarter 2026 revenue of US$3.537b and net income of US$217m, while also completing builder’s sea trials for amphibious transport dock Harrisburg and advancing autonomous mine countermeasure capabilities with Thales.
- The combination of higher earnings and progress on both large Navy ship programs and modular autonomous systems highlights how HII’s backlog is increasingly supported by operational milestones, not just contract announcements.
- We will now look at how Huntington Ingalls Industries’ investment narrative is affected by stronger earnings and the Harrisburg sea trials.
Scan beyond Huntington Ingalls Industries to see how other defense and mission-critical contractors compare in terms of cash flow strength and balance sheet resilience with our hand-picked list of solid balance sheet and fundamentals (25 results)
Huntington Ingalls Industries Investment Narrative Recap
To own Huntington Ingalls Industries, you need to be comfortable with a long build cycle, heavy contracts and the ongoing effort to turn that backlog into predictable cash. The analyst consensus Narrative on Simply Wall St leans on higher shipbuilding throughput, better margins and steadier earnings quality. The latest quarter showed higher revenue and net income, which supports that thesis, but the story still hinges on execution rather than headlines.
The key short term swing factor remains free cash flow delivery against the US$500m to US$600m target for 2026. Harrisburg’s successful builder’s trials help de risk near term shipyard performance a bit, yet they do not change the heavy reliance on later contract advances, incentives and tax credits. Carrier execution issues and high debt keep the main risks firmly in view.
The most relevant recent update for this story is Harrisburg’s builder’s sea trials at Ingalls. That test run covered propulsion, steering, combat and mission systems, with major objectives reported as met. For an investor watching Huntington Ingalls Industries, that reads as incremental evidence that throughput and schedule discipline at Ingalls are lining up with what management has been targeting.
This trial also speaks directly to the catalysts built around higher volume and better margins in shipbuilding. A clean path to acceptance trials and delivery reduces the odds of fresh cost overruns on this LPD and may free resources for Pittsburgh, Philadelphia and follow on LPDs. It does not solve carrier program volatility or the back end loaded cash profile, but it supports the case that parts of the yard network are doing what they need to do.
Huntington Ingalls Industries’ narrative projects US$15.3b revenue and US$965.0m earnings by 2029. That outlook aligns with analyst assumptions of 5.2% yearly revenue growth and an earnings increase of about US$304.0m from US$661.0m today.
Uncover why Huntington Ingalls Industries' fair value indicates a 17% potential upside to its current price, which could narrow quickly as sentiment shifts.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into Huntington Ingalls Industries’ automation push as the real story, not just one ship’s clean sea trials. Before this news, the bullish camp was modeling roughly 7.3% annual revenue growth and earnings of about US$1.2b by 2029. You can compare that to your own view and see how opinions might shift after Harrisburg and the Thales mine countermeasure update.
Explore 4 other Huntington Ingalls Industries fair value estimates, including one that suggests as much as 64% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Huntington Ingalls Industries research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Huntington Ingalls Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Huntington Ingalls Industries' overall financial health at a glance.
Looking for more investment ideas beyond Huntington Ingalls Industries?
Once you have a handle on Huntington Ingalls Industries, it can help to widen the lens and compare it with other opportunities that fit your preferences for quality, income or risk.
- If you want potential mispricings backed by solid fundamentals, you can explore a curated set of companies trading on attractive metrics with strong financial profiles through the 33 high quality undervalued stocks.
- For investors who care most about consistent income, you can review a focused group of higher yielding payers and stress test their staying power using the 6 dividend fortresses.
- If capital preservation matters just as much as upside, you can start with a pre filtered pool of sturdier balance sheets and steadier risk profiles via the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com