


EN
Does Earnings Surge Change The Bull Case For Darling Ingredients Stock (DAR)
- Darling Ingredients reported third quarter 2026 revenue of US$1,791.12 million and net income of US$266.99 million, with basic earnings per share from continuing operations of US$1.70.
- The nine month figures highlighted a sharp shift in profitability, as net income reached US$788.61 million compared with a very small profit in the prior year period.
- We will look at how Darling Ingredients' investment narrative is affected by this surge in quarterly earnings and improved profitability.
See how Darling Ingredients' recent increase in profitability compares with other businesses showing strong fundamentals in our curated 33 high quality undervalued stocks.
Darling Ingredients Investment Narrative Recap
For an investor to own Darling Ingredients, there needs to be confidence that the mix of feed, food and fuel ingredients can turn policy support for renewable diesel and higher value collagen into durable cash generation. The analyst consensus Narrative on Simply Wall St leans on that multi segment story. The latest quarterly profit jump helps that case, but does not remove the core execution risks.
In the short term, the key catalyst is whether Diamond Green Diesel can keep running strongly while regulations around Renewable Identification Numbers and Renewable Volume Obligations remain supportive. The biggest current risk is that these policy levers or commodity pricing move against the business, which could quickly pressure margins after a very profitable nine month stretch.
The fresh third quarter results are the main update investors have to work with right now. Sales for the period reached US$1,791.12 million, with net income of US$266.99 million and basic earnings per share from continuing operations of US$1.70. For the nine months, revenue was US$5,066.02 million and net income was US$788.61 million.
Those figures sit alongside the existing catalysts in the analyst consensus Narrative on Simply Wall St, such as potential EBITDA uplift from operational efficiency in the Feed segment and growth in higher margin collagen within Rousselot. The recent profitability gives management more room to focus on debt reduction and any future capital returns, although policy and pricing risks in renewable fuels still loom large over the outlook.
Darling Ingredients' current analyst framework points to revenues of US$7.3b and earnings of US$864.7 million by 2029, based on forecast revenue growth of 3.7% a year and an increase in earnings from US$597.9 million today to the 2029 consensus, which is roughly a 45% rise in profit over that period.
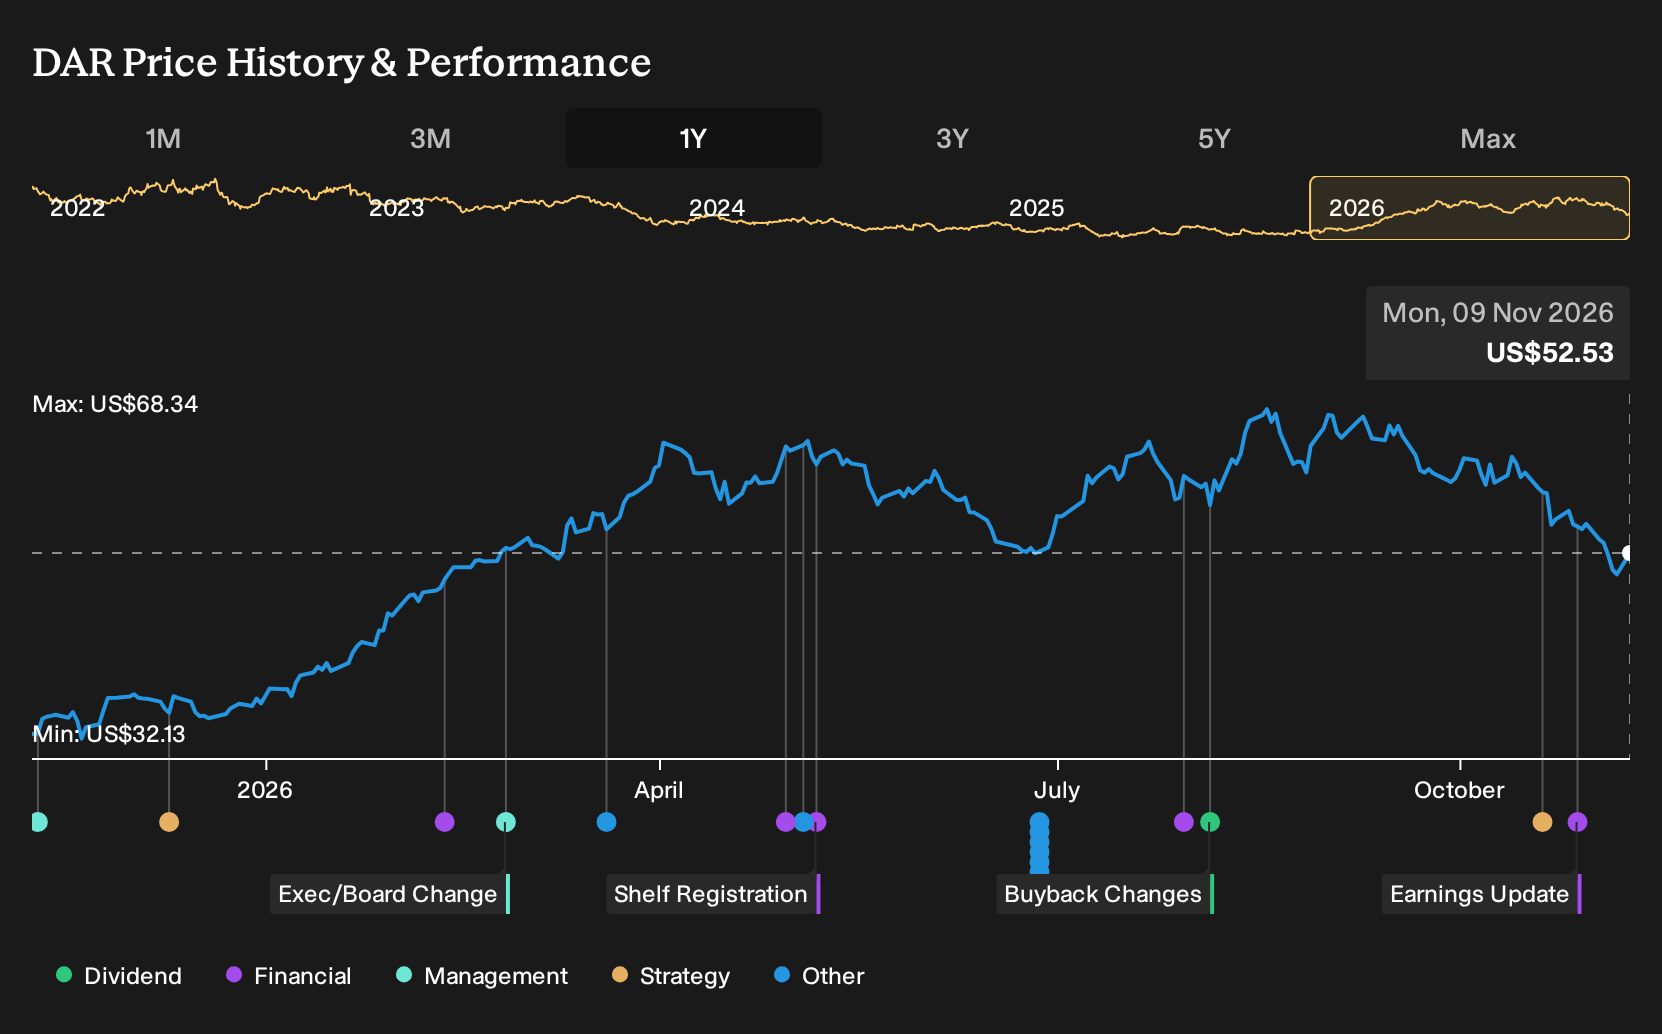
Uncover why Darling Ingredients' fair value indicates a 56% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view fixates on renewable diesel margins as a risk rather than a growth engine. The most cautious analysts were only penciling in 2.2% annual revenue growth and earnings of about US$817.2 million by 2029 before this report. That is a much more restrained story. Use these differences to test your own expectations as fresh Darling Ingredients results roll in and forecasts potentially shift.
Explore 5 other Darling Ingredients fair value estimates, including one that suggests it could be worth just $67.50!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own judgment.
- A great starting point for your Darling Ingredients research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Darling Ingredients. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Darling Ingredients' overall financial health at a glance.
Looking for more investment ideas beyond Darling Ingredients?
If the Darling Ingredients story has sharpened your view on what you want to own, the next step is to line that thesis up against a broader watchlist. The Simply Wall St Screener can help you quickly filter for businesses that fit your risk tolerance, income needs, or quality focus.
- For investors who care most about balance sheet strength and fundamental resilience, start by scanning our list of solid balance sheet and fundamentals (25 results) to see which companies meet those criteria.
- If your priority is finding potential mispricings backed by solid financial profiles, review the 33 high quality undervalued stocks and compare how these candidates stack up against Darling Ingredients.
- Readers aiming to control downside risk can use the 30 resilient stocks with low risk scores as a way to surface stocks that our models suggest carry relatively lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com