


EN
3 Export Stocks Investors May Search As Tariffs Push Orders Beyond China
China’s surging trade surplus and underpriced yuan are quietly reshaping where the next wave of profits, and pain, could land for global exporters. A stronger currency or fresh tariffs would not just hit spreadsheets in Beijing; it could redirect orders, pricing power, and supply chains toward non Chinese manufacturers. This article walks through 3 stocks exposed to that story so you can judge whether they deserve a closer look now.
The exporters profiled next are only a starter set, drawn from a wider group of multinational manufacturers that fit this yuan and tariff re routing theme. The full screen surfaced 47 more companies with equally compelling narratives that do not fit into a single article.
If you want to go beyond this sample and quickly identify which large exporters line up best with your own risk, sector, and valuation preferences, head straight to the Non‑Chinese Multinational Exporters Benefiting from Potential Yuan Revaluation and Tariff-Driven Re‑shoring screener to analyze the full universe and focus on your highest conviction ideas.
Wonik IPS (KOSDAQ:A240810)
Wonik IPS is a Korean equipment maker that supplies semiconductor, display, and solar cell systems to global manufacturers, fitting the non Chinese exporter theme as buyers look for alternatives to China. Almost all of its roughly ₩942.8 billion segment revenue comes from semiconductor equipment, and the group carries a market value around ₩3.3 trillion.
Wonik IPS sits right in the path of any shift away from Chinese suppliers. It sells critical semiconductor and display tools from Korea into global fabs that are reassessing where they source equipment. The story is largely about whether that desire for non Chinese capacity meets one powerful constraint that could change both pricing power and how steady demand really feels.
If that constraint matters for you, start with the 3 key rewards and 2 important warning signs (1 is major!) and see how the potential upside and pressure points stack up.

Taiyo Yuden (TSE:6976)
Taiyo Yuden develops and sells electronic components like multilayer ceramic capacitors, inductors, and RF parts, giving manufacturers a non Chinese sourcing option as tariffs and currency moves reshape supply chains. Its electronic components arm produces about ¥383.8 billion in sales, and the stock carries a market value near ¥885.5 billion.
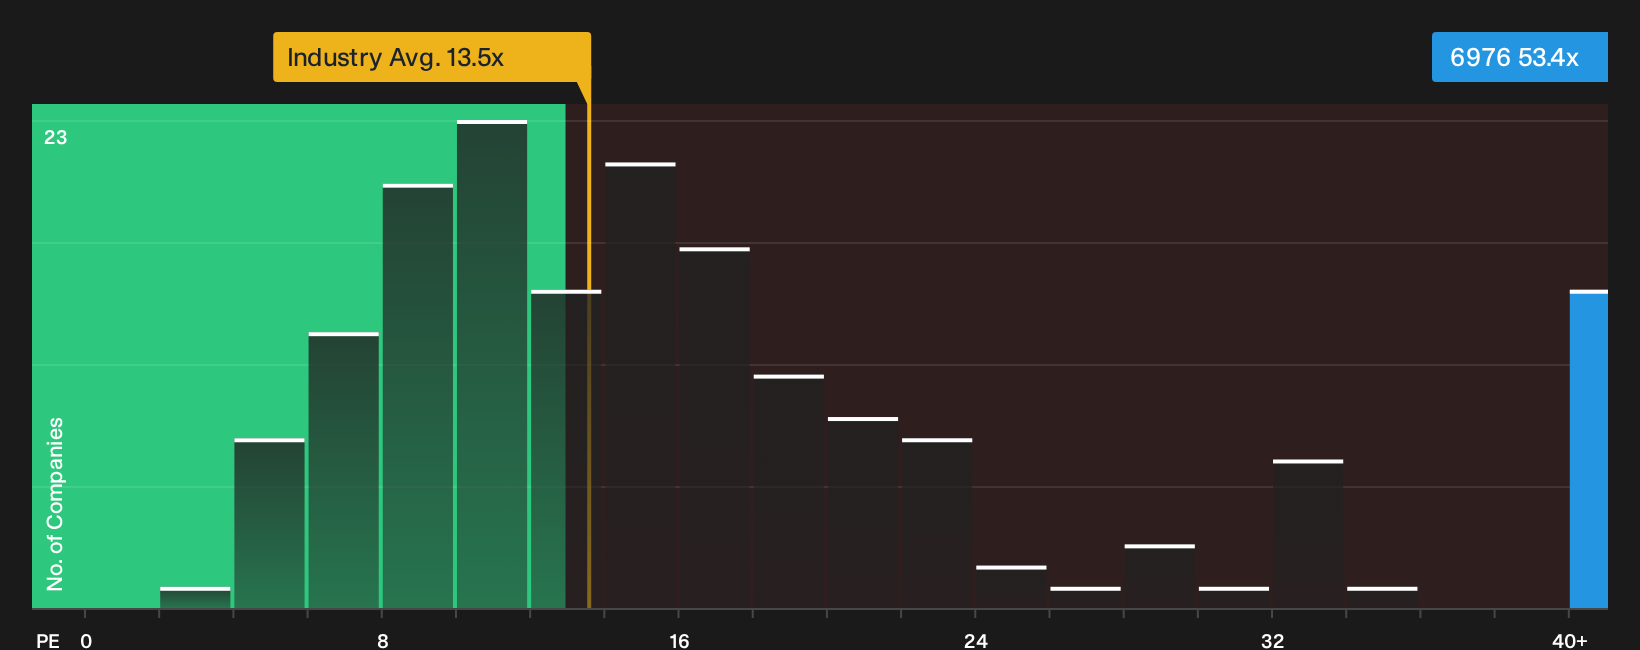
Taiyo Yuden gives you a Japan based exporter with capacitors and RF parts spread across North America, Europe, and Asia at a time when buyers are looking beyond Chinese suppliers. The company reports that earnings have rebounded and that revenue growth is outpacing the broader Japanese market. The current valuation of about 53x P/E together with still modest margins is a key factor for investors to consider.
That rich 53x P/E and modest profitability put the focus squarely on quality, so see the analysis report for Taiyo Yuden to understand what might justify that valuation or challenge it.
Murata Manufacturing (TSE:6981)
Murata Manufacturing is a Japan based producer of ceramic capacitors, inductors, RF modules, sensors, and batteries that slots neatly into the non Chinese exporter theme as buyers consider alternatives to Chinese component suppliers. Components generate about ¥1.35t, Devices and Modules ¥667.1b, and Others ¥70.5b in revenue, with the group valued around ¥8.93t.
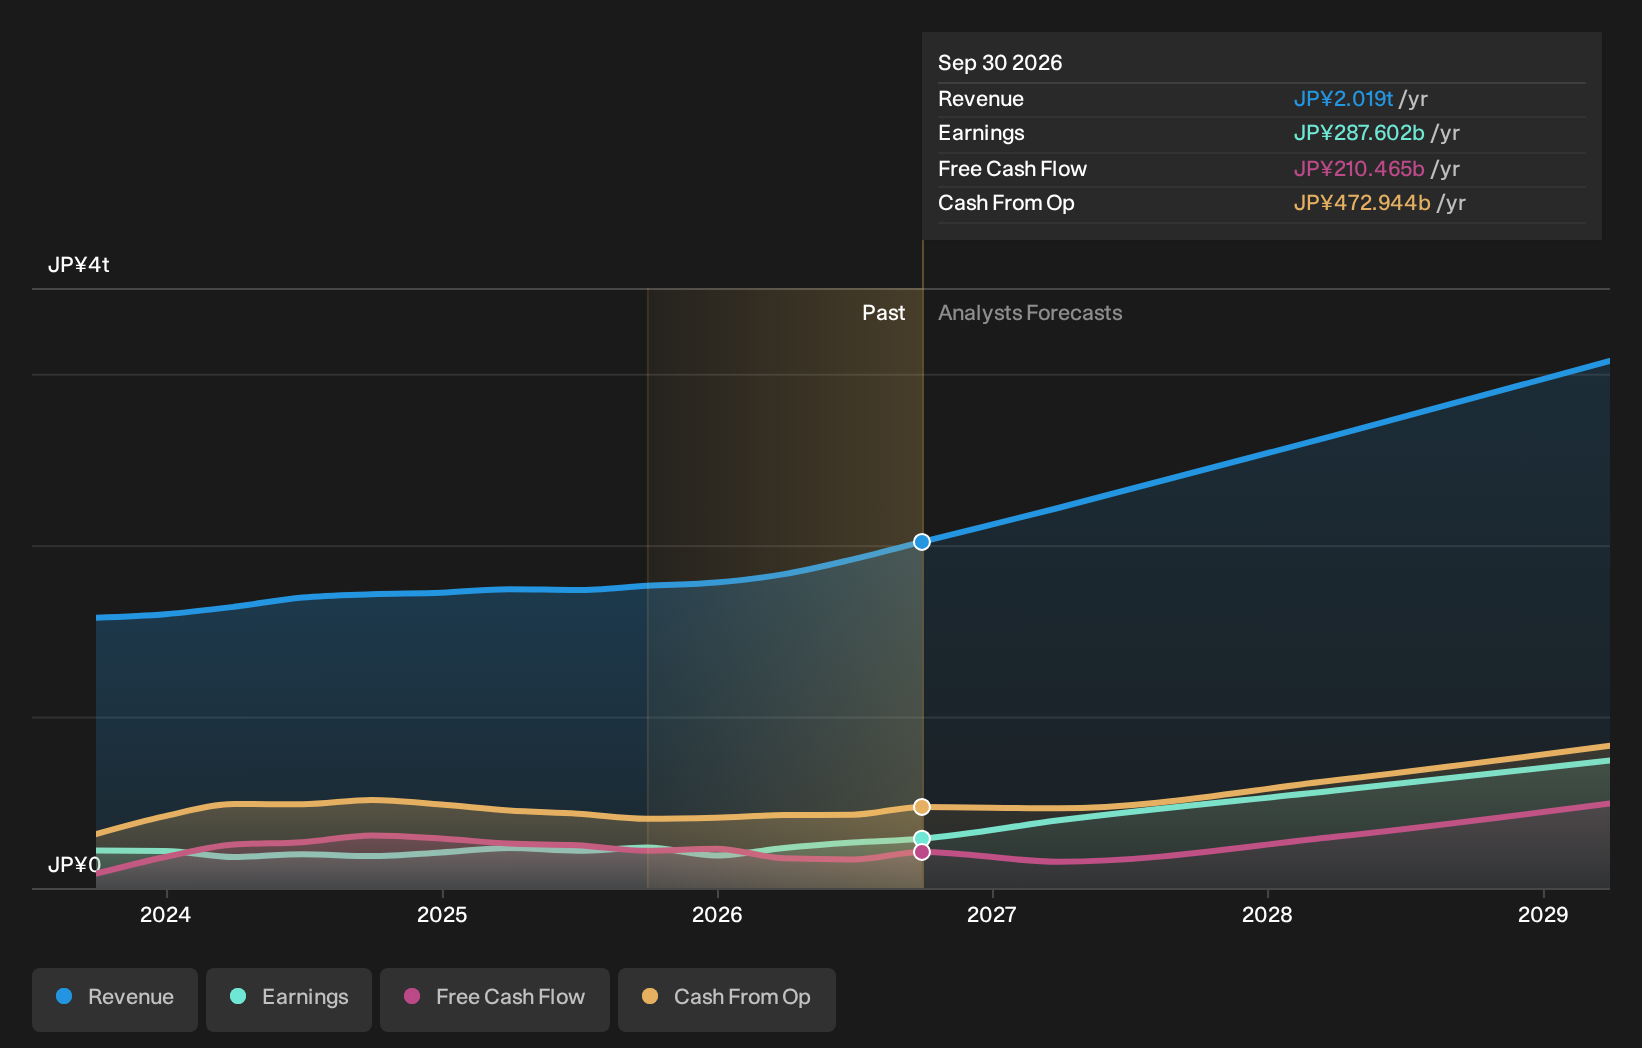
Murata Manufacturing provides exposure to a large, non Chinese exporter supplying capacitors and RF parts into communications, autos, data centers, and wearables across the US, Europe, Asia, and China. Expectations for earnings, revenue, margins, and capacity expansion are closely linked to how trade policies may influence where global electronics orders are placed.
That trade driven order flow is exactly why the analyst forecasts for Murata Manufacturing could be worth your time if you want to see where expectations might be stretching or still conservative.
Seeking Alternatives Before Others Catch On
Fresh ideas move first. Once the crowd notices, the best entry points can slip away as momentum builds, prices react, and opportunity drops out of reach. Scan what is flying under the radar for now and look for opportunities early.
- Look for early momentum in smaller, financially resilient businesses by scanning the curated 126 elite penny stocks with strong financials before potential breakouts are fully reflected in prices.
- Review the hand picked 42 power grid technology and infrastructure stocks to explore the next wave of infrastructure demand while the theme may still be under the radar for many investors.
- Explore companies involved in AI’s real-world backbone by screening the focused 53 AI infrastructure stocks before institutional money potentially increases attention on this area.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com