


EN
Is Man Group (LSE:EMG) Cheap As Deutsche Bank's Target Cut Hits Sentiment?
Man Group (LSE:EMG) has come under pressure after a sharp 7.65% share price drop, following a Deutsche Bank target cut and broader weakness in technology stocks that spilled over into sentiment toward the asset manager.
For context, Man Group shares are still up 32.81% on a year to date share price basis and the 1 year total shareholder return is 53.70%. The recent 9.55% 1 month share price decline and 8.80% 7 day pullback therefore look more like momentum cooling after a strong run, rather than a complete change in the longer term trend, especially given the 68.39% 3 year and 75.49% 5 year total shareholder returns.
Scan how Man Group compares with other fee-driven managers by reviewing the hand picked 16 high quality undervalued stocks that combine cleaner balance sheets with room for sentiment to shift.
Bulls point to Man Group’s solid fee income and long record as an investment manager. Bears focus on sentiment risks, borrowing concerns and a sharp pullback. Which side do the current valuation markers support next?
Most Popular Narrative: 20% Undervalued
On the analyst consensus Narrative on Simply Wall St, Man Group screens as undervalued, with a fair value of £3.83 against a last close of £3.07. That view leans heavily on fee growth potential and an AI enabled operating model to support profitability.
Ongoing broadening of Man Group’s product set, with performance fee eligible assets rising to $69.2b by June 2026 and assets at high watermark at $53.3b, sets up a larger pool that can translate into future performance fees and higher earnings power.
See why 79 investors see Man Group as 20% undervalued.
Result: Fair Value of £3.83 (UNDERVALUED)
Still, the narrative for Man Group hinges on sensitive points, including ongoing PIFSS litigation outcomes and the risk that weaker net inflows could cut into fee revenue.
Find out about the key risks to this Man Group narrative.
Another View: Man Group Through The P/E Lens
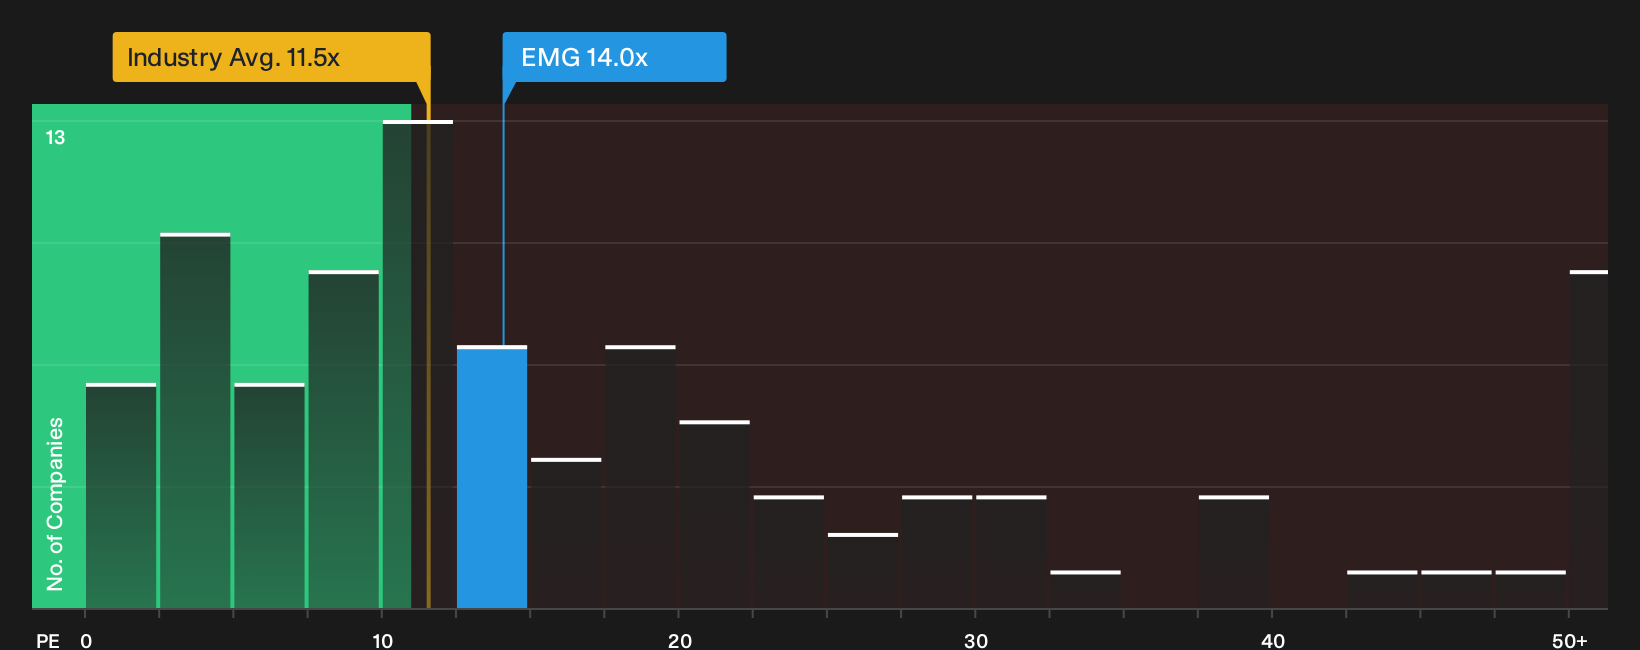
There is a catch. On a simple P/E comparison, Man Group trades at about 14x, which is richer than both the UK Capital Markets group at roughly 11.4x and direct peers near 11.1x, even though the estimated fair ratio sits higher at 17.4x. Is that premium a cushion or a warning sign for you?
To unpack what this gap between current P/E, sector levels and the fair ratio might mean for upside risk or downside risk in practice, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Feeling torn between the upside story and the headline risks around Man Group after this pullback? You may want to act while sentiment is still mixed and check the balance of concerns and positives for yourself by reviewing the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Man Group?
If Man Group has your attention but you want a few more angles to test your thinking, let the Simply Wall St Screener surface some fresh contenders.
- Target resilient income potential by reviewing 6 dividend fortresses that combine sizeable yields with a focus on sustaining regular payouts.
- Hunt for stronger balance sheet quality through the list of solid balance sheet and fundamentals (9 results) and compare businesses that pair lower financial strain with sturdier fundamentals.
- Spot opportunities others may be overlooking by scanning the 5 high quality undiscovered gems before the wider market catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com