


EN
What JHSF Participações Buyers Were Betting On
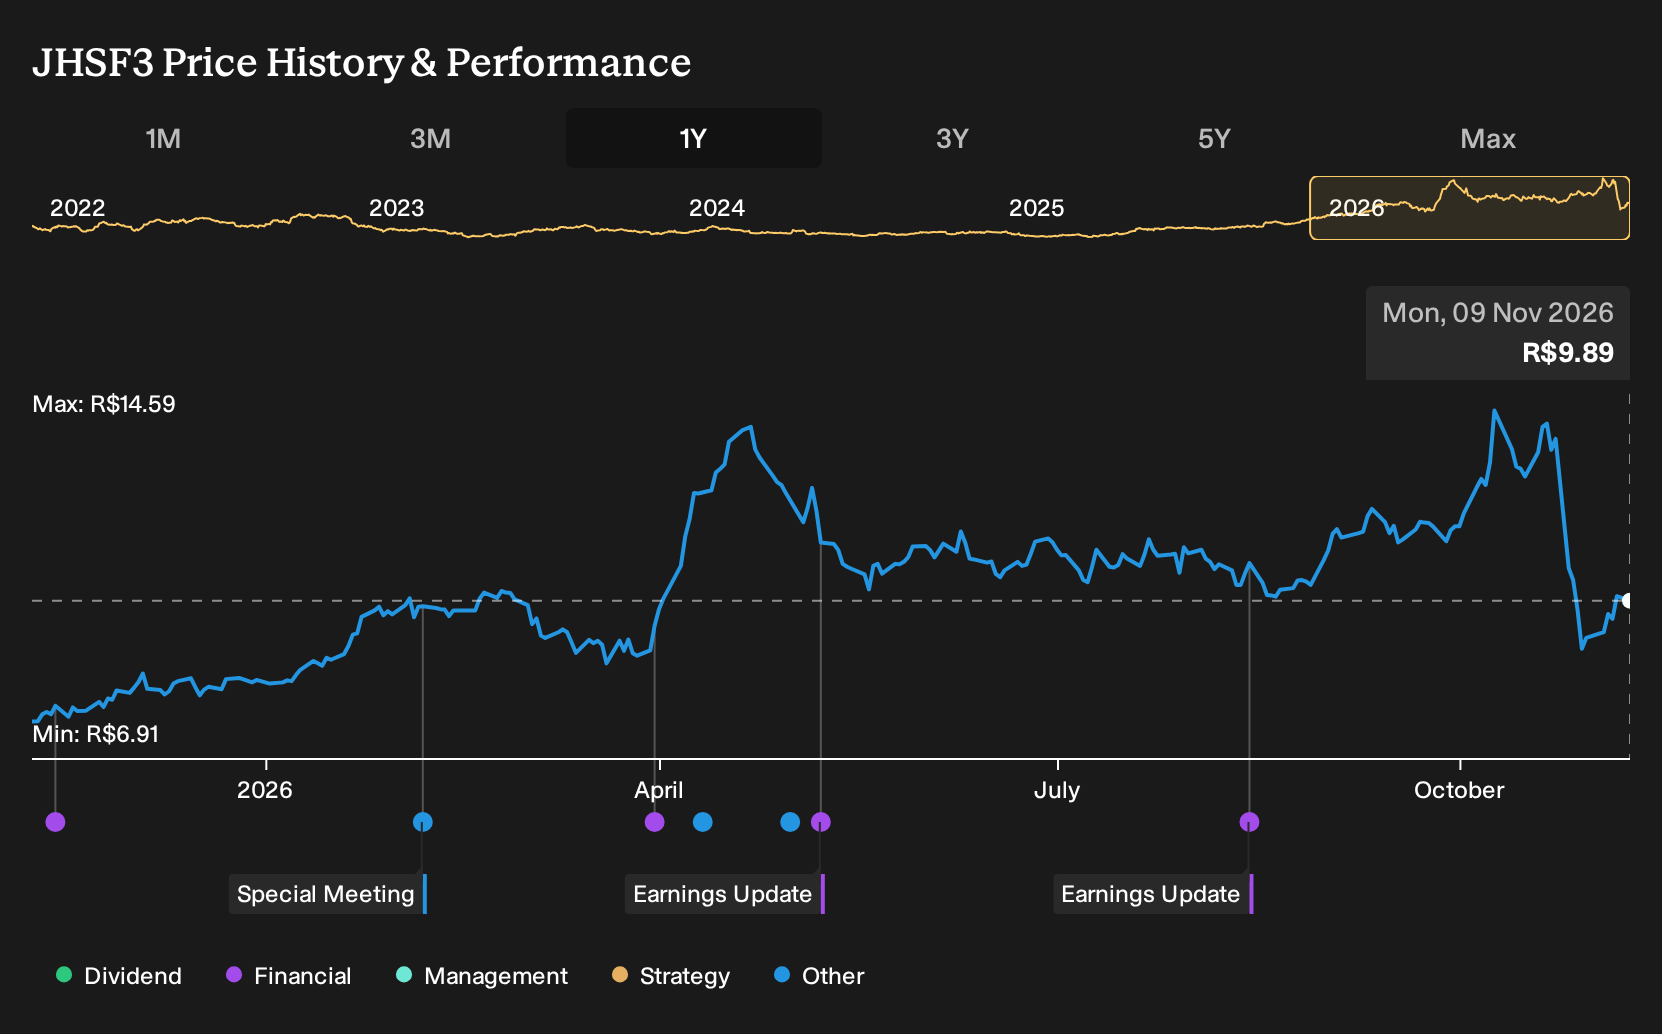
If you had bought JHSF Participações on 9 November 2025, the outcome over the following year would have been very different from sitting in cash. For JHSF Participações shareholders, the return over the past year was 54.7%, including dividends. That result now sits next to a valuation gap. Bulls argued that Cidade Jardim’s scarcity could support higher rents, while bears highlighted concentration, leverage, and climate risk. If you were choosing that day, which side of that trade-off would have seemed more convincing?
JHSF Participações has already moved. See which of 204 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Were Weighing On JHSF Participações
The shares cost R$6.89 at the start of the period, and anyone looking at JHSF Participações then was really choosing between two very different stories.
On the bullish side, one group saw Cidade Jardim and other luxury assets supporting a Fair Value of R$10. This was a notional price that assumed scarce premium properties, near full occupancy, and a larger role for high-end recurring income across malls, hospitality, and real estate.
The bearish narrative pointed to a Fair Value of R$4.2. This implied level was built on concerns that heavy exposure to ultra-luxury clients, leverage, and climate and regulatory risks could strain margins as new projects, international hotels, and airports required ongoing funding.
What The Results Changed For JHSF Participações
The clearest datapoint was the jump in total revenue from R$496.093 million in Q2 2025 to R$935.319 million in Q2 2026, alongside higher net income and a slightly stronger net margin at 48.3%. That tilt in profitability supported more of the bullish story on earnings power, although it did not directly answer concerns about leverage, climate exposure, or client concentration.
The lesson is simple. When a thesis rests on premium assets and pricing power, treat net margin and segment revenue as the scoreboard, and check whether each report actually tracks that claim.
What JHSF Participações' Recent Run Already Prices In
JHSF Participações now trades at R$9.89. The bullish analyst Narrative on Simply Wall St sees Fair Value above that level, based on a view that the high-end ecosystem can keep supporting strong operating profitability over time.
According to this Narrative, today's price still does not fully credit recurring, fee based earnings from malls, hospitality, Catarina Airport and JHSF Capital.
"The shift of JHSF Participações toward an ecosystem that leans on malls, hospitality, airport, residences and investment management, combined with BRL 4.2b of revenue still to be recognized from inventories sold into the development fund, can deepen multi-year earnings visibility and sustain higher quality EBITDA and net profit."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Find Your Own Contrarian Opportunity
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 17% below our estimate - sells automated cooking systems as restaurants upgrade to more resource-efficient kitchen technology.
- Company 2 - 16% below our estimate - targets excavator operators adopting tiltrotators as new projects demand faster, more precise digging.
- Company 3 - 47% below our estimate - expands digital forensics software as agencies upgrade to higher tier subscriptions and ACV contracts.
Three companies from the same screener. Open every one of the 194 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com