


EN
Chevron (CVX) Names Governance Chief, Is The Stock Still Undervalued?
How Chevron’s latest governance move ties back to the stock
Chevron (CVX) has sparked fresh attention after naming long-time in house lawyer Siva Barnwell Adams as corporate secretary and chief governance officer, succeeding Mary A. Francis from January 2027.
For shareholders, a change in the officer responsible for board counsel, governance policy and oversight of major corporate actions can influence how risk controls, disclosure practices and large transactions are evaluated inside the company.
Chevron’s governance reshuffle comes after a busy spell for the stock. The share price is down 7.46% over the past week but still shows a 35.20% year to date share price return and a 5 year total shareholder return of 120.48%, which indicates momentum that has built over time rather than faded in recent sessions.
Scan how Chevron’s governance shift compares with other large energy players by reviewing the 30 resilient stocks with low risk scores that combine resilient balance sheets with lower overall risk profiles.
Chevron has a seasoned insider taking charge of governance just as the stock’s long run of gains meets a short term pullback. Is that shift reflecting underlying business strength, or simply sentiment catching its breath before investors reprice the shares?
Most Popular Narrative: 9% Undervalued
Chevron closed at $210.78 compared to an analyst consensus fair value of $232.50 from the analyst consensus Narrative on Simply Wall St, which applies a 7.24% discount rate to its cash flow forecasts and earnings assumptions.
Long duration projects such as the 20 year, 2.67 GW take or pay power agreement with Microsoft and the planned US$7b growth phase in Venezuelan joint ventures are expected to add contracted or low cost production and power sales that can support future revenue, earnings and free cash flow.
See why 491 investors see Chevron as 9% undervalued.
Result: Fair Value of $232.50 (UNDERVALUED)
Still, the Chevron story can break if analyst projections on margins and earnings miss the mark, or if long term energy demand shifts faster than modeled.
Find out about the key risks to this Chevron narrative.
Another View: Chevron looks expensive on earnings multiples
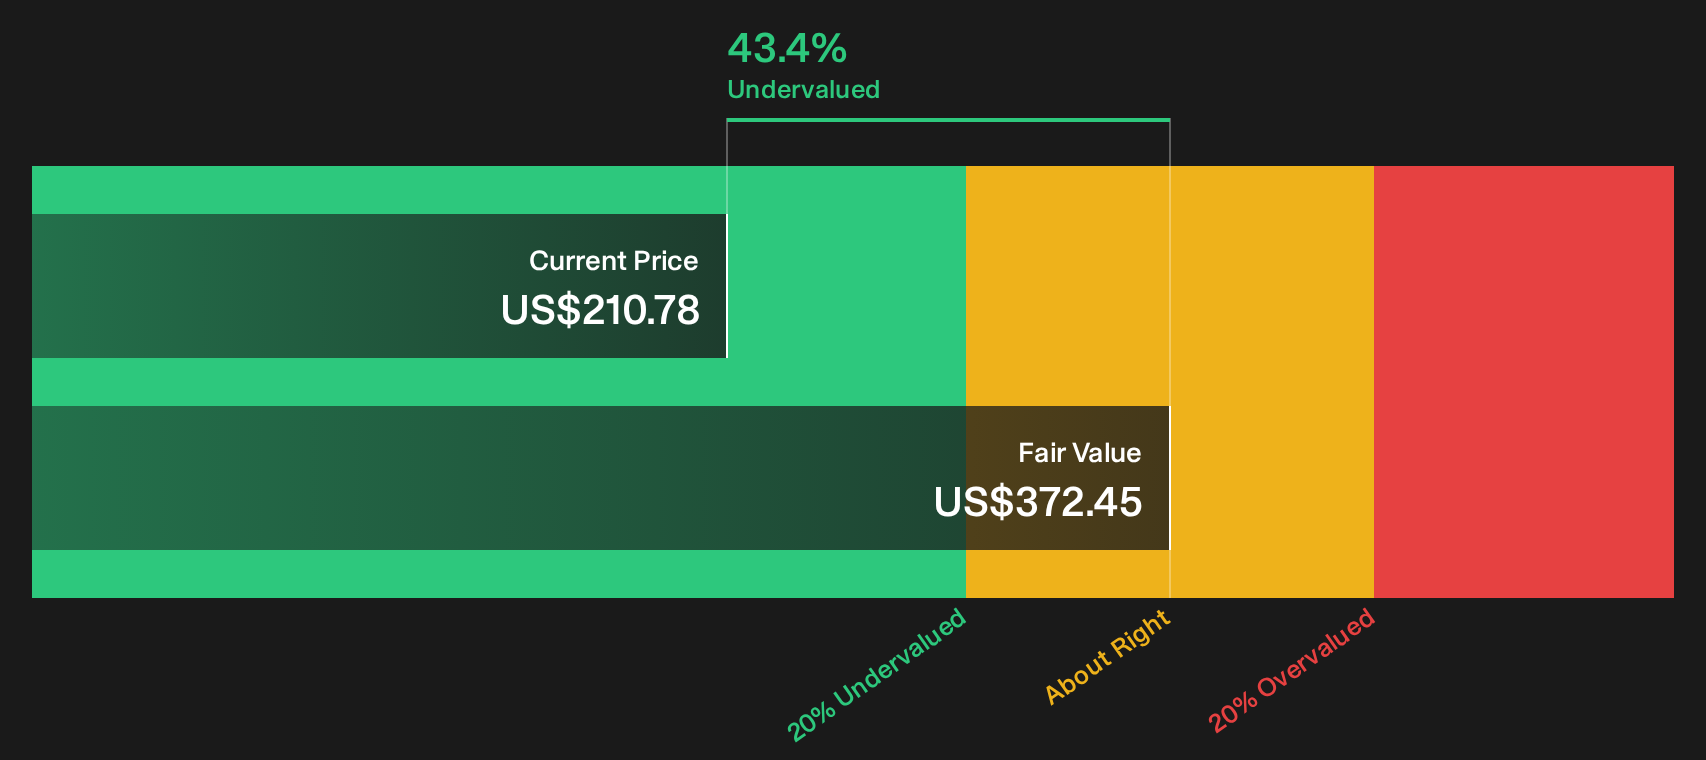
The Simply Wall St DCF model points to Chevron trading at a 43.4% discount to an estimated future cash flow value of $372.45, which frames the stock as undervalued on a cash flow basis. Yet the current P/E of 15.2x sits above the US Oil and Gas industry at 10.5x and above peer averages at 13.5x, even though the fair ratio is 19.9x. That mix of a discounted DCF and a richer earnings multiple raises a live question for investors: Is the market underpricing long term cash generation, or already paying up for near term earnings power.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Chevron can be confusing, especially with both risks and rewards in play. Use the full picture to sharpen your own take with 3 key rewards and 1 important warning sign.
Looking for more Chevron sized investment ideas?
If Chevron has sharpened your thinking, do not stop here. Broaden your watchlist today so you are not chasing the crowd after the next move breaks.
- Target stronger value by scanning companies with robust fundamentals using the 33 high quality undervalued stocks.
- Stack potential income streams by reviewing a curated set of higher yielding opportunities with the 6 dividend fortresses.
- Prioritise resilience by focusing on businesses with healthier finances through the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com