


EN
Why Church & Dwight (CHD) Is Back In The Spotlight
Church & Dwight (CHD) has just wrapped a busy October, pairing stronger third quarter earnings with higher full year EPS guidance and a fresh US$1b share repurchase authorization.
The stronger third quarter earnings, higher full year EPS guidance and fresh US$1b buyback have supported momentum in Church & Dwight’s shares, with a 30 day share price return of 13.45% and a year to date share price gain of 34.69% at a last close of US$111.31.
Scan how Church & Dwight’s earnings beat and buyback story compares with other high quality household and consumer stocks using our hand picked 33 high quality undervalued stocks
After a 34.69% gain this year and a price now slightly above the average analyst target, the question for Church & Dwight is simple. Has the recent earnings beat and buyback news already done most of the work, or is there still clear upside left in the valuation?
Most Popular Narrative: 2% Overvalued
On the analyst consensus Narrative on Simply Wall St, Church & Dwight screens as slightly overvalued, with a fair value estimate of $108.84 versus the latest share price of $111.31, even after factoring in the earnings beat, raised guidance and new buyback.
The numbers imply the Church & Dwight share price reflects a market that remains cautious on growth and margin durability despite the company raising its 2026 organic sales, EPS and cash from operations guidance and continuing to target its evergreen model.
See why 15 investors see Church & Dwight as 2% overvalued.
Result: Fair Value of $108.84 (OVERVALUED)
Still, the narrative around Church & Dwight can change quickly if vitamin gummies and multivitamins continue to struggle or if higher SG&A ratios persist for longer.
Find out about the key risks to this Church & Dwight narrative.
Another View: Church & Dwight Through The SWS DCF Lens
Analyst targets suggest Church & Dwight is about 2% above a fair value of $108.84, yet the SWS DCF model paints a different picture. On that cash flow view, the stock at $111.31 sits roughly 17% below an estimated value of $133.81, which raises a tougher question: Is the market putting too much weight on near term growth worries and not enough on the long term cash engine?
To understand how those cash flows are modeled and stress test the inputs against your own assumptions, take a closer look at the SWS DCF model output for Church & Dwight using Look into how the SWS DCF model arrives at its fair value.
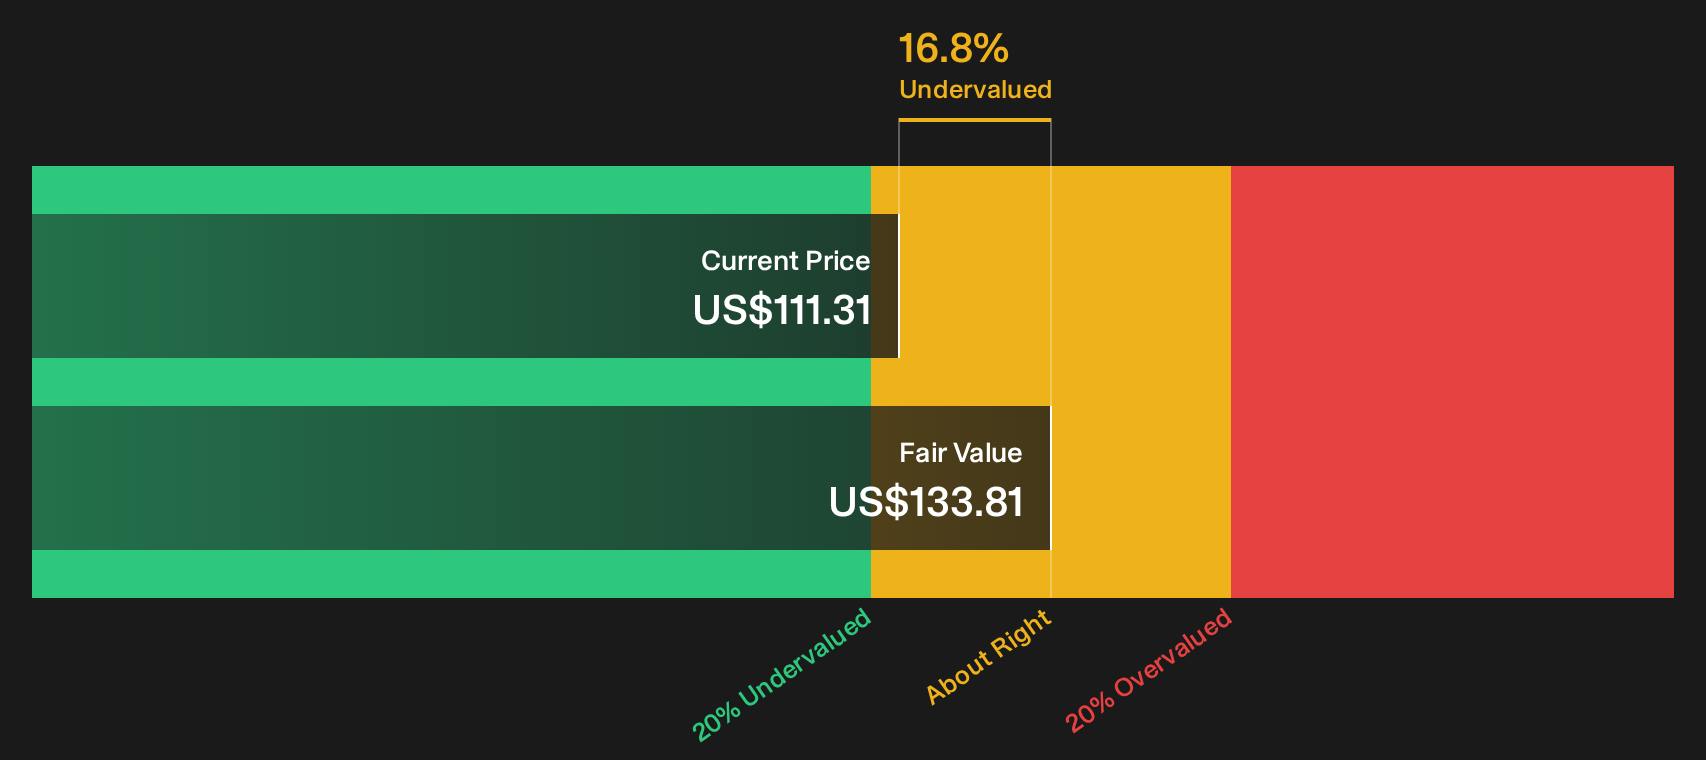
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Church & Dwight for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The debate around Church & Dwight’s valuation is clear enough, so the next move is on you to decide quickly where you stand. To see what investors are optimistic about right now, review the company’s 2 key rewards
Looking for more ideas beyond Church & Dwight?
If you only stop at Church & Dwight, you could miss other compelling setups. Put a few more smart contenders on your radar before the next move.
- Chase potential re-rating opportunities by scanning a curated pool of high quality undervalued ideas with the 33 high quality undervalued stocks.
- Stack your watchlist with resilient balance sheets by running the list of solid balance sheet and fundamentals (25 results) and focusing on businesses built to absorb shocks.
- Look for possible future standouts by combing through the 19 high quality undiscovered gems and seeing which stories may warrant a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com