


EN
AECOM (ACM) And The Case For A Rebound On Its Infrastructure Backlog
AECOM (ACM) has drawn investor attention after its recent share move, with the stock closing at $70.21. Short-term performance contrasts with weaker year-to-date and 1-year total returns.
The recent 1 day share price return of 5.2% and 1 month share price return of 18.4% suggest short term momentum is building for AECOM, even though the year to date share price return is down 27.2% and the 1 year total shareholder return has fallen 45.4%.
Scan how AECOM compares with peers by reviewing a curated set of infrastructure plays in the 42 power grid technology and infrastructure stocks that are also exposed to large transportation, energy, and public works spending cycles.
After a sharp short term rebound yet deep double digit declines over the past year, AECOM now trades well below the average analyst price target and an even lower intrinsic value estimate. Where does fair value really sit in that gap?
Most Popular Narrative: 22% Undervalued
AECOM last traded at $70.21, while the most followed narrative pegs fair value at $90.00, creating a sizeable valuation gap according to that framework. According to Andrei_Niculescu, an investor in the Simply Wall St Community who wrote the narrative, the key issue is how much of Q3’s damage is truly permanent.
AECOM's Q3 tells a story of two businesses at once: a headline quarter hit by a $337 million project charge, and an underlying infrastructure business that is still winning work at a record pace. The distinction is important.
See why 4 investors see AECOM as 22% undervalued.
Result: Fair Value of $90.00 (UNDERVALUED)
Still, AECOM’s narrative depends on the Construction Management charge remaining isolated and on that US$27.8b backlog converting to profitable work as planned.
Find out about the key risks to this AECOM narrative.
Another View On AECOM’s Valuation
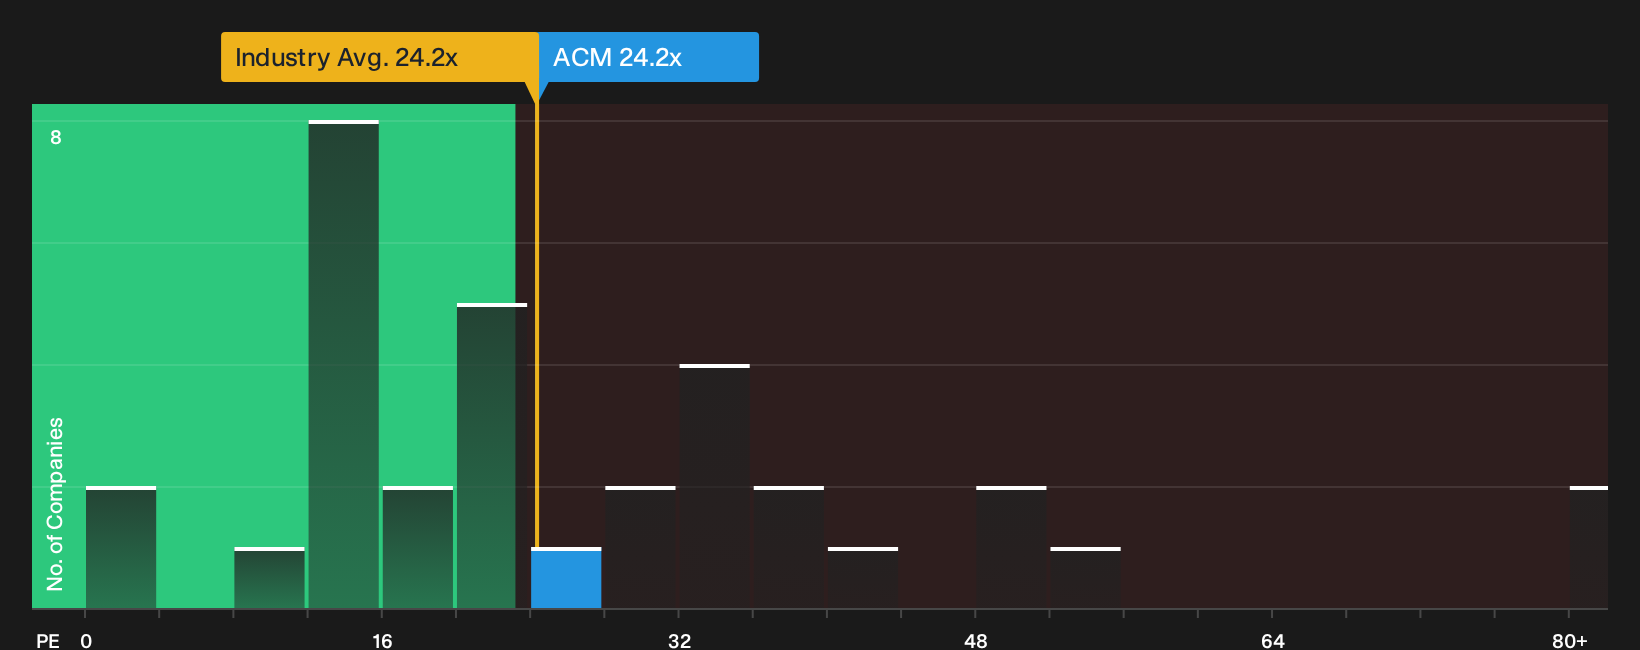
The narrative pegs AECOM at $90.00 per share, yet the P/E picture tells a different story. The stock trades on 24.2x earnings, which is higher than the peer average of 22.6x and equal to the broader US Construction group on 24.2x. The fair ratio sits at 33.1x. The current discount to that level may appeal to some investors, but it also raises a clear question about how much valuation risk they are comfortable taking if sentiment turns.
For a closer look at how that earnings multiple compares with what the fair ratio suggests the market could eventually move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around AECOM's recent move make this a good moment to look directly at the numbers and decide where you stand. If you want a concise view of both the concerns and the upside before you act, start with the 2 key rewards and 2 important warning signs.
Looking for more AECOM sized investment ideas?
If you only stop at AECOM, you risk missing opportunities that might suit your goals even better, so give yourself options using the Simply Wall St screener.
- Target potential value plays that pair quality with attractive pricing through our 33 high quality undervalued stocks.
- Strengthen your income focus by screening for yield opportunities and payout consistency using the 6 dividend fortresses.
- Calm portfolio swings by filtering for businesses with sturdier finances via the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com