


EN
Is Qualys (QLYS) Overvalued Following Its Q3 Results And Raised EPS Guidance?
Qualys (QLYS) just put fresh numbers on the table, with Q3 2026 revenue of US$188.05 million and net income of US$57.17 million, giving investors new data to reassess the stock.
The latest jump in Qualys shares, with a 1-day share price return of 6.33% to US$202.46, comes on the back of Q3 results, raised full-year EPS guidance, and fresh partnerships that plug its TruRisk platform deeper into mobile, OT, IoT, and identity security. Over a longer stretch, momentum has been strong, with a year to date share price return of 54.54% and a 1-year total shareholder return of 33.21%, suggesting gains have been meaningful for investors who stayed in the story rather than trading around short-term swings.
Scan how Qualys fits into the wider cybersecurity opportunity set by reviewing a hand-picked 30 resilient stocks with low risk scores that pairs resilient balance sheets with consistent fundamentals.
The latest jump in Qualys now raises a sharper question. Are investors finally catching up with the TruRisk driven business progress just reported, or has sentiment simply sprinted ahead of what the current numbers justify?
Most Popular Narrative: 8% Overvalued
On the Simply Wall St analyst consensus Narrative, Qualys screens as overvalued, with a fair value of $187.59 against the last close at $202.46, which places more weight on cash flow and earnings forecasts than on recent price strength.
The current numbers, including mid-40s adjusted EBITDA margins, low-40s free cash flow margins, and ongoing share repurchases, imply the share price already prices in Qualys as a high-margin, fairly valued, AI and platform-led security compounder rather than a turnaround story.
See why 48 investors see Qualys as 8% overvalued.
Result: Fair Value of $187.59 (OVERVALUED)
Still, the narrative around Qualys can crack if AI security rivals outpace its platform or if new modules fail to offset pressure in the core offerings.
Find out about the key risks to this Qualys narrative.
Another View: Qualys Through The Earnings Lens
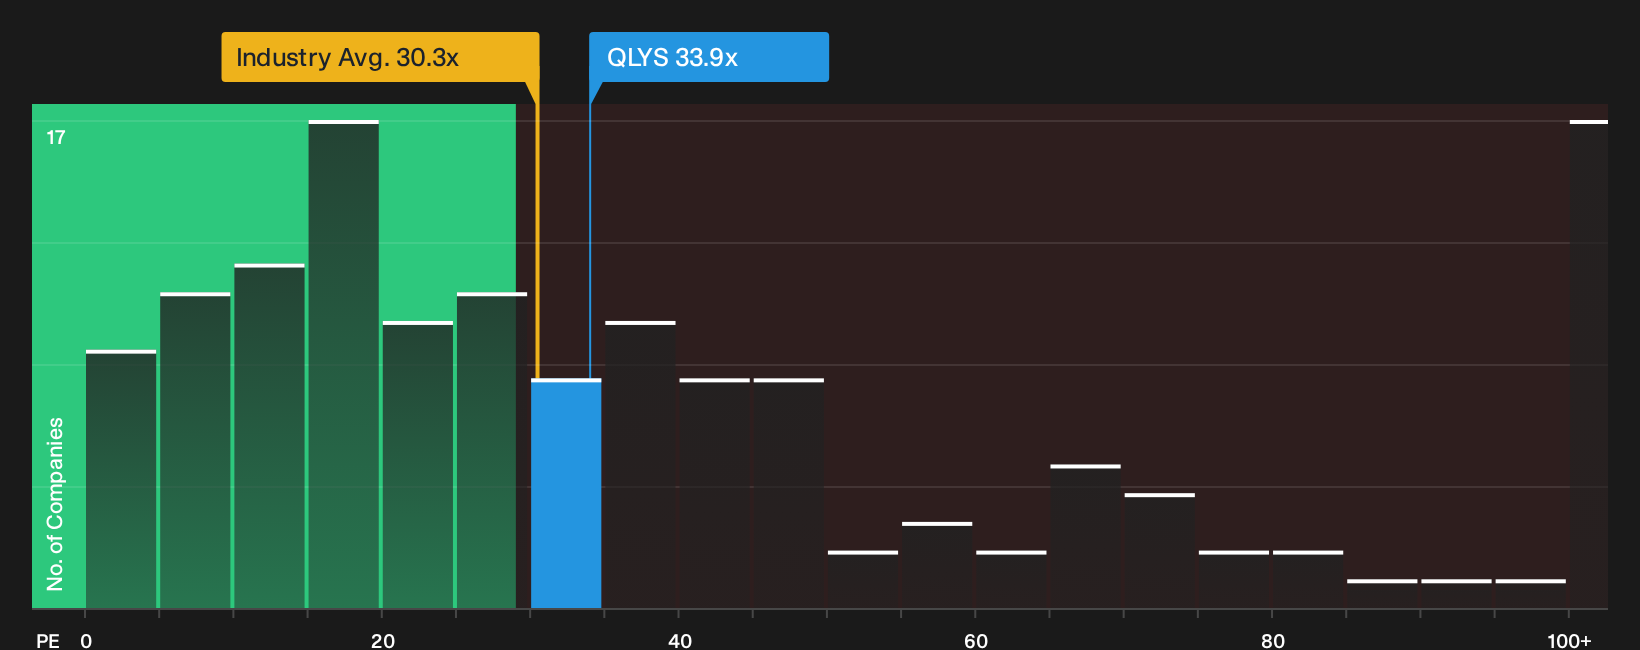
There is a twist once valuation shifts from fair value estimates to simple earnings multiples. Qualys trades on a P/E of 33.9x, which is lower than peers at 36.1x, yet higher than its own fair ratio of 26.1x. That mix points to upside on quality, but also real valuation risk if sentiment cools.
Before leaning on that earnings multiple too heavily, it is worth seeing how the detailed valuation stack fits together in practice, including what the fair ratio implies for where the market could drift over time, in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Qualys in this piece has tilted toward caution, so consider acting promptly and stress test that view against your own work using the 3 key rewards.
Looking for more investment ideas beyond Qualys?
If the Qualys story has sharpened your thinking, do not stop here. Broader opportunity often appears where few people are currently looking.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (25 results) that filters for financially robust businesses.
- Spot potential mispricings early and compare them with Qualys by scanning the 33 high quality undervalued stocks built around quality and valuation discipline.
- Hunt for under-followed opportunities that the crowd might be ignoring by working through a focused 19 high quality undiscovered gems list.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com