


EN
Kiniksa Stock In Focus After Stronger Earnings Per Share
- Kiniksa Pharmaceuticals International reported third quarter 2026 results, with basic earnings per share from continuing operations of US$0.61 and diluted earnings per share of US$0.56, compared with US$0.25 and US$0.23, respectively, a year earlier.
- Across the first nine months of 2026, the business reported basic earnings per share from continuing operations of US$1.23 and diluted earnings per share of US$1.14, highlighting how current profitability levels influence the way investors assess its ARCALYST-focused model and pipeline funding capacity.
- We will now look at how Kiniksa Pharmaceuticals International's sharply higher quarterly earnings per share may influence the broader investment narrative.
Kiniksa Pharmaceuticals International Investment Narrative Recap
To own Kiniksa Pharmaceuticals International, you need to be comfortable with a story that is still heavily tied to ARCALYST while management works to build out a broader cardiovascular and immunology platform. The latest quarterly earnings per share figures suggest the current business model is producing solid profitability, which can help support continued investment in KPL-387 and KPL-116.
In the short term, the key catalyst remains execution in recurrent pericarditis, including continued ARCALYST uptake and payer support, as described in the analyst consensus Narrative on Simply Wall St. The biggest operational risk is still product concentration, since any change in prescribing patterns, competition, or reimbursement could quickly weaken that earnings base.
The recent third quarter and nine-month earnings announcement is central here. Basic earnings per share from continuing operations of US$0.61 for the quarter and US$1.23 year to date, with diluted earnings per share of US$0.56 and US$1.14, indicate that Kiniksa Pharmaceuticals International is currently funding its pipeline from internal profitability rather than relying solely on external capital.
That has implications for potential catalysts. Continued earnings strength gives the business more room to progress KPL-387 through the Phase 2/3 program in recurrent pericarditis and advance earlier-stage assets without putting as much pressure on balance sheet flexibility. The same report also highlights that any setback in ARCALYST demand or pricing would feed directly into this earnings stream, so execution on that franchise remains the key swing factor.
Kiniksa Pharmaceuticals International is being modeled to reach US$1.4b in revenue and US$237.3 million in earnings by 2029. This assumes revenue growth of 19.7% per year and an earnings increase of about US$156.6 million from current earnings of US$80.7 million.
Uncover why Kiniksa Pharmaceuticals International's fair value indicates a 5% potential upside to its current price that could narrow quickly.
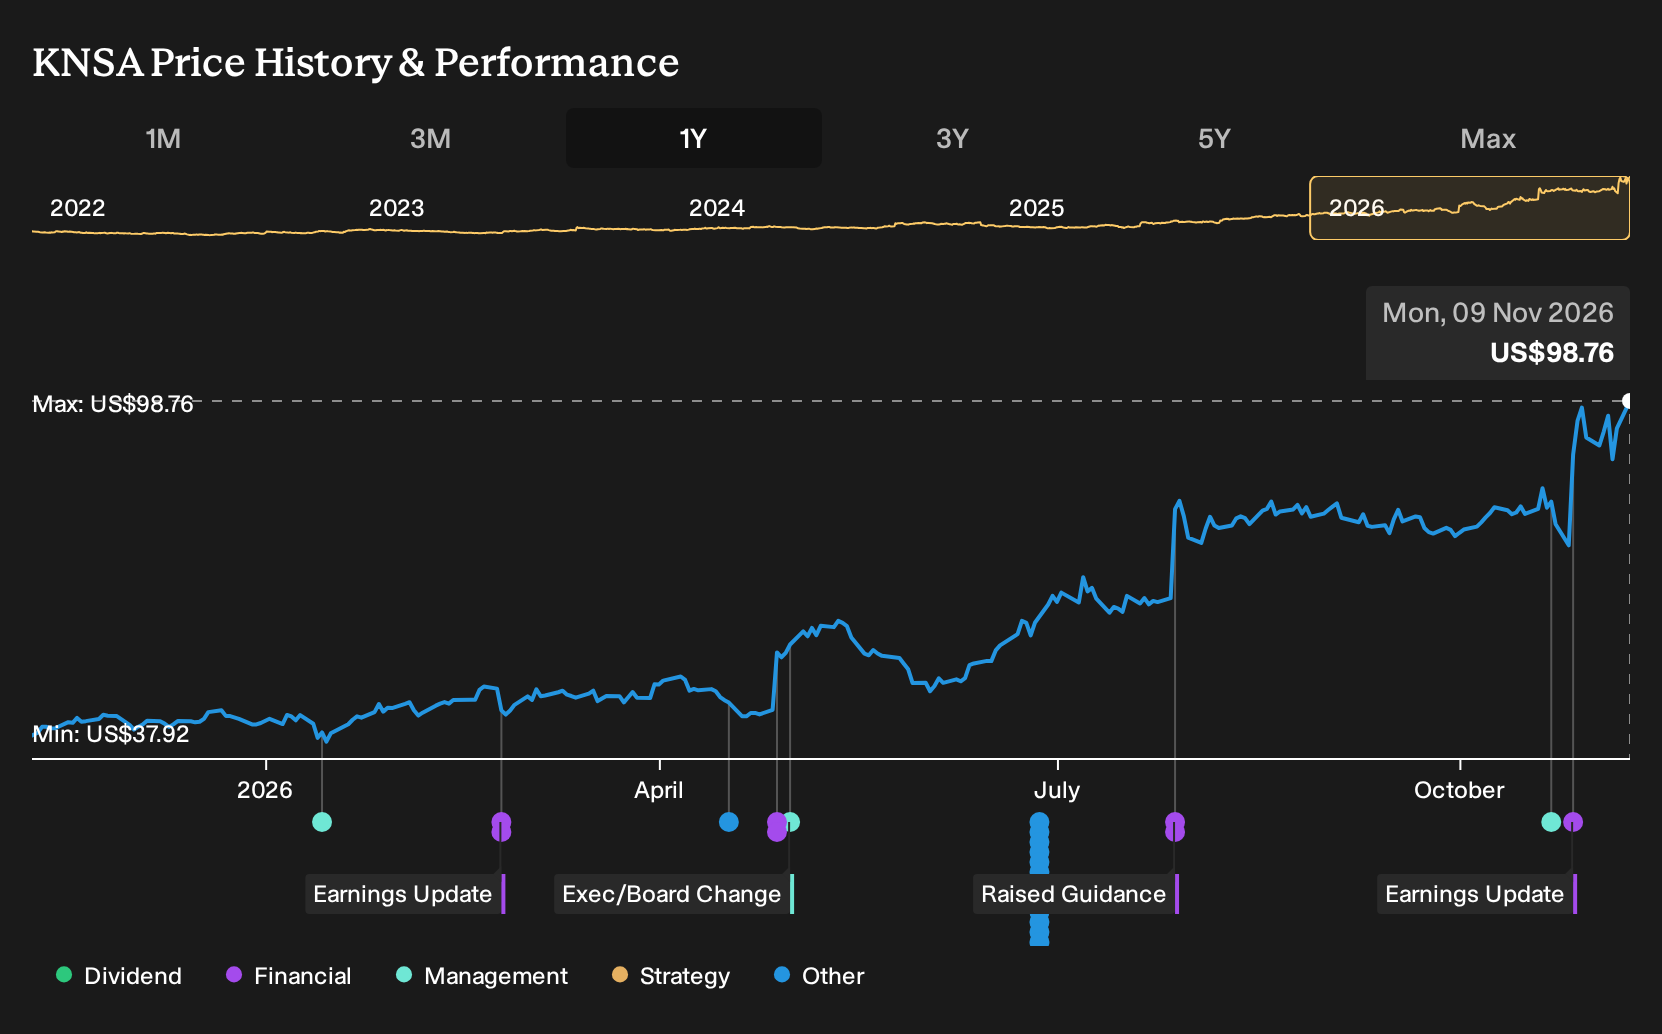
Exploring Other Perspectives
One alternate view on Kiniksa Pharmaceuticals International focuses less on upside from ARCALYST and more on the risk that momentum cools. The lowest analysts were pencilling in revenue growth of 18.2% a year and earnings of about US$171.0 million by 2029, compared with US$109.6 million today, before this earnings surprise. That more cautious script could shift if recent results change how you and those analysts think about durability of demand and the pipeline.
Explore 4 other Kiniksa Pharmaceuticals International fair value estimates, including one that suggests it could be worth just $98.00.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Kiniksa Pharmaceuticals International research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kiniksa Pharmaceuticals International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kiniksa Pharmaceuticals International's overall financial health at a glance.
Looking for more investment ideas beyond Kiniksa Pharmaceuticals International?
If the Kiniksa Pharmaceuticals International story has sharpened your interest in earnings quality and risk, you can use the Simply Wall St Screener to look for other stocks that fit your style instead of waiting for the next headline to appear in your feed.
- For investors who care most about financial resilience and funding flexibility, start with a list of solid balance sheet and fundamentals (25 results) that can support long run reinvestment and potential shocks.
- If capital preservation is your first priority, consider a 30 resilient stocks with low risk scores that scores well on volatility and fundamental risk checks.
- Those looking for under the radar opportunities can scan a 19 high quality undiscovered gems that combine quality fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com