


EN
Nordson (NDSN) Could Be 7% Undervalued After New Smart Factory Jetting System Launch
Nordson (NDSN) drew fresh attention after its Nordson EFD unit introduced the PICO Pµlse XP HV jetting system for high viscosity materials, highlighting the group’s focus on smart factory compatible, precision dispensing solutions.
The PICO Pµlse XP HV launch hit as Nordson’s share price jumped 4.51% on the day to US$323.84, even though the 7 day and 30 day share price returns are slightly negative. At the same time, a 34.36% year to date share price return and 39.66% 1 year total shareholder return suggest momentum has been building over a longer stretch as investors reassess both growth potential and risk around its automation focused portfolio.
Scan beyond Nordson and see which industrial and automation focused peers are also drawing interest in our curated 91 robotics and automation stocks for precision manufacturing plays.
The sharp move in Nordson after the PICO Pµlse XP HV news raises a simple tension: Is this just the market catching up to the story, or has most of the upside already been priced in ahead of current valuation metrics?
Most Popular Narrative: 7% Undervalued
On the analyst consensus Narrative on Simply Wall St, Nordson screens as modestly undervalued, with a fair value of $349.71 against the last close at $323.84. That view leans heavily on the mix of advanced technology and recurring revenue.
Acceleration in advanced technology solutions, with over half of Nordson’s portfolio now tied to semiconductor, electronics and medical customers and ATS segment organic sales up 31% in Q3 FY2026 on strong demand and new systems such as the ASYMTEK Vantage XL, points to further support for revenue and earnings growth from higher value equipment and related software over time.
See why 15 investors see Nordson as 7% undervalued.
Result: Fair Value of $349.71 (UNDERVALUED)
Still, if Nordson’s higher exposure to semiconductor and medical demand lifts investor expectations, or if its strong cash generation drives a richer P/E, this underpriced story can flip quickly.
Find out about the key risks to this Nordson narrative.
Another View: Nordson Looks Expensive On Earnings
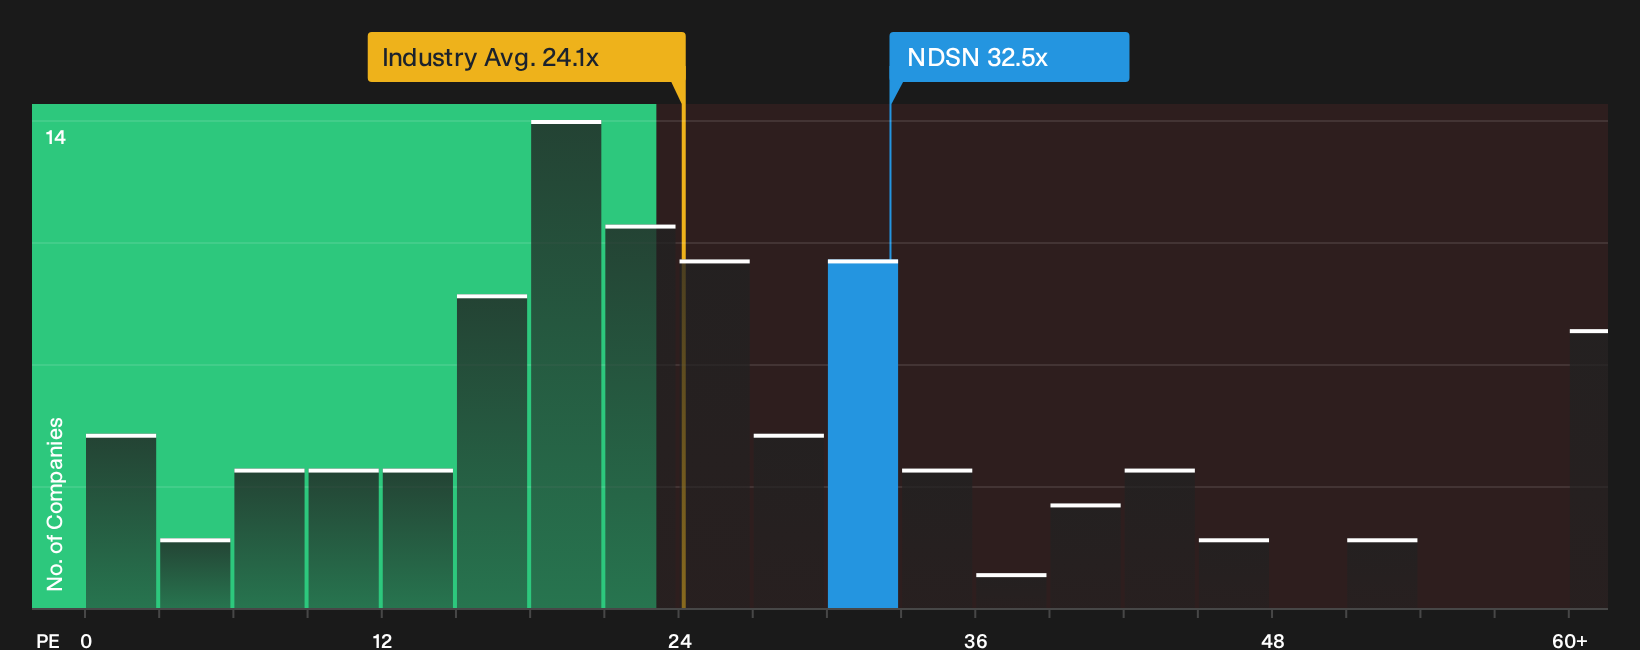
The first take presents Nordson as modestly undervalued based on analyst fair value estimates. A simple earnings multiple offers a different perspective. The stock trades on a P/E of 32.5x, compared with 23.2x for the US Machinery industry, 24.8x for peers, and a fair ratio of 23.2x that the market could lean toward over time.
That kind of premium can benefit investors if profit growth remains ahead of the pack. However, it also raises the risk that any change in expectations could affect the share price more than the broader sector. The question is simple: does the quality of Nordson’s business truly justify paying such a high earnings multiple?
See what the numbers indicate about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Nordson can be confusing, so move quickly, review the underlying data for yourself, and size up the balance of 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Nordson?
If Nordson has sharpened your focus on quality and pricing power, do not stop here. Broaden your watchlist with a few targeted idea lists built from hard data.
- Tap into potential mispricings by scanning a curated pool of quality companies that still look attractively valued through our 33 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies with higher yields in our focused 6 dividend fortresses that screens for payouts backed by fundamentals.
- Dial back portfolio stress by hunting for sturdier businesses in the 30 resilient stocks with low risk scores that filters for resilience across key risk indicators.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com