


EN
International Petroleum (TSX:IPCO) Stock Looks Stretched Despite Recent Pullback
International Petroleum has delivered striking longer term gains for shareholders, yet the recent pullback and rich earnings multiple have put the focus squarely on what investors are paying for each dollar of profit today. With that share price history in mind, the key issue now is how well the current market value lines up with the company’s earnings power.
- Over the past 5 years, International Petroleum has returned about 409.6%, which raises the question of how much of that performance is already reflected in the earnings multiple investors accept now.
- Recent production ramp up at the Blackrod project and continued share repurchases can support expectations for stronger earnings per share, which affects how investors might think about a higher P/E level.
- The analysts covering International Petroleum have run their own numbers. See what analysts think International Petroleum's shares could be worth.
The issue now is whether International Petroleum's recent earnings justify the price implied by its current P/E ratio.
If you are weighing International Petroleum's rich P/E against its track record, it can help to compare it with 6 high quality undervalued stocks that the same framework highlights.
Does International Petroleum Look Pricey on Earnings?
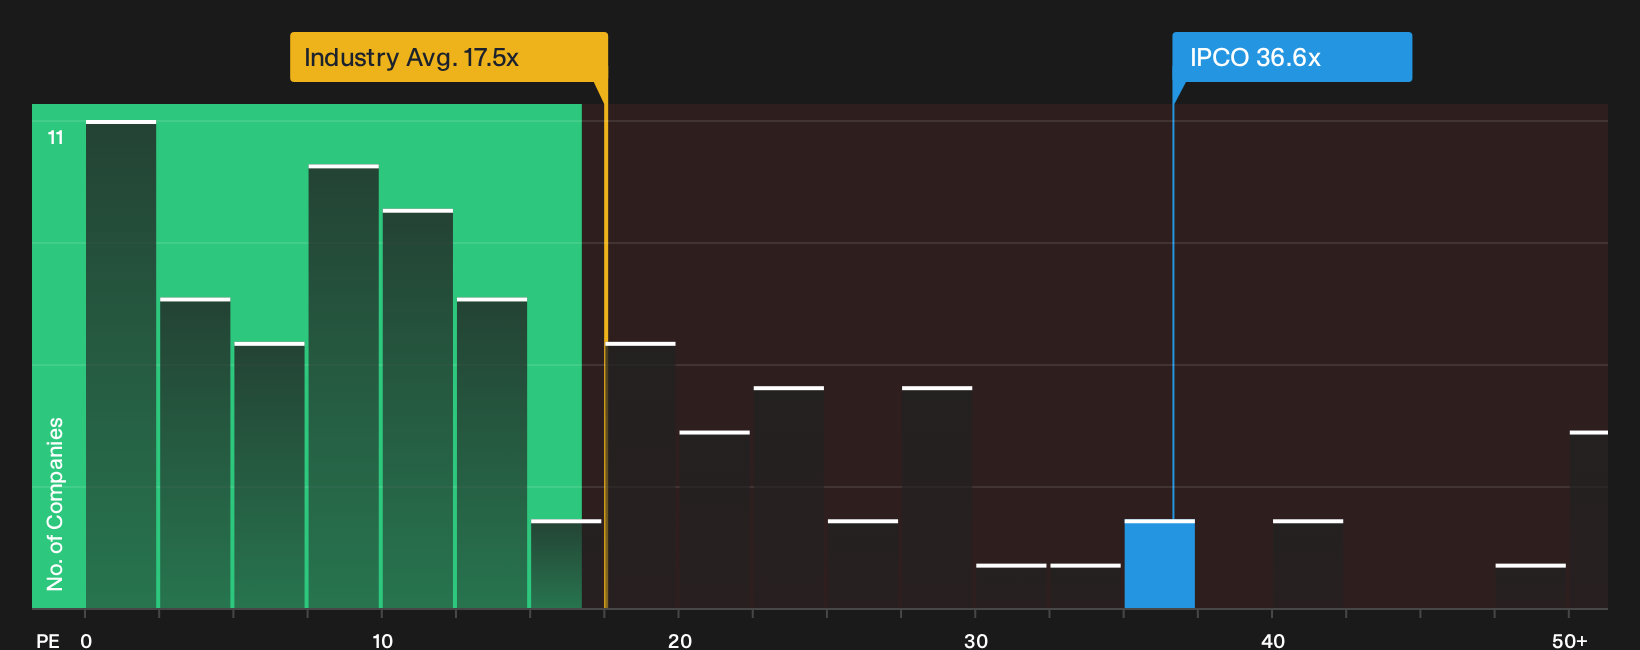
The P/E lens suits International Petroleum because earnings matter directly for a resource producer that is actively investing and buying back shares. On this measure, the stock trades on roughly 36.6x earnings, which is materially above the Oil and Gas industry average of about 17.5x and ahead of peers near 22.7x. That premium suggests the market is willing to pay a higher price for each dollar of International Petroleum's profit than it does for the typical sector player.
Because the recent Blackrod ramp up and share repurchases have lifted expectations, the current P/E also screens well above the level suggested by a more tailored fair multiple that factors in the business profile and risk. The gap points to a valuation that appears overvalued on this framework, even after the recent share price pullback mentioned in the Q3 2026 update. For investors, the question is whether International Petroleum's earnings path and capital returns ultimately justify paying such a premium for the stock today. Explore the numbers behind International Petroleum's P/E valuation.
The International Petroleum Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where that P/E puzzle for International Petroleum leaves off by spelling out what kind of future earnings path, margin profile and risk picture would need to play out for the current share price to prove either conservative or stretched. Each scenario connects a specific number to a clear view on how International Petroleum's growth, profitability and uncertainty might evolve, which gives you something concrete to revisit as fresh information arrives on the Community page.
One of the top narratives on International Petroleum: 16% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The current valuation implies the share price already reflects a fair outcome for International Petroleum, with Blackrod Phase 1, ongoing free cash flow from 2026 and the established share buyback program largely priced in…"
Discover why this Narrative puts International Petroleum at 16% undervalued.
International Petroleum's valuation still leaves one powerful unknown
Numbers only tell part of the story for International Petroleum. The people setting capital priorities, and the way they are rewarded, can strongly influence how those figures evolve over time. See who runs International Petroleum and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com