


EN
DENSO (TSE:6902) Could Be 44% Below Fair Value After Buyback And Dividend Lift
DENSO (TSE:6902) drew fresh attention after unveiling a share repurchase plan of up to 100,000,000 shares for ¥200,000 million, paired with higher dividends and updated full year earnings guidance.
These shareholder friendly moves arrive after a choppy stretch for DENSO, with the 1-year total shareholder return down 3.22% and the 3-year total shareholder return down 9.40%. This comes despite a recent 30-day share price return of 5.75%, which hints at improving short term momentum.
Spot opportunities beyond DENSO's buyback story by scanning a curated set of shareholder focused companies in the 22 high quality undervalued stocks. These companies pair solid fundamentals with potential mispricing.Shareholders now face a split screen. One side sees DENSO committing serious cash to buybacks and dividends; the other points to muted multi year returns. Which story does the valuation back up next?
Preferred Price-to-Earnings of 11.2x: Is it justified?
DENSO trades on a P/E of 11.2x against a last close of ¥1,931, which points to a valuation that looks restrained compared with several reference points.
The P/E ratio compares the current share price with earnings per share. For an auto components group like DENSO, it gives a quick read on how much investors are paying for each unit of profit in a sector where capital spending and profit cycles can be uneven.
On peers, the picture is mixed. DENSO screens as good value when set against its own estimated fair P/E of 12.3x, and it also looks inexpensive versus the peer average of 14.6x. At the same time, the stock trades at a richer level than the broader JP Auto Components industry average of 9.1x. This suggests that the market is already assigning the business a premium over the wider group and that it could still adjust closer to the fair ratio level.
Explore the SWS fair ratio for DENSO.
Result: Price-to-Earnings of 11.2x (UNDERVALUED)
Still, the recent share price slide since the start of the year and patchy multiyear returns leave DENSO exposed if sentiment on auto components weakens.
Find out about the key risks to this DENSO narrative.
Another view on DENSO's value
The P/E discussion paints DENSO as modestly priced, yet the SWS DCF model tells a different story. At ¥1,931 against an estimated future cash flow value of ¥3,468.97, the shares screen as significantly undervalued. Which signal do you trust more, the earnings multiple or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
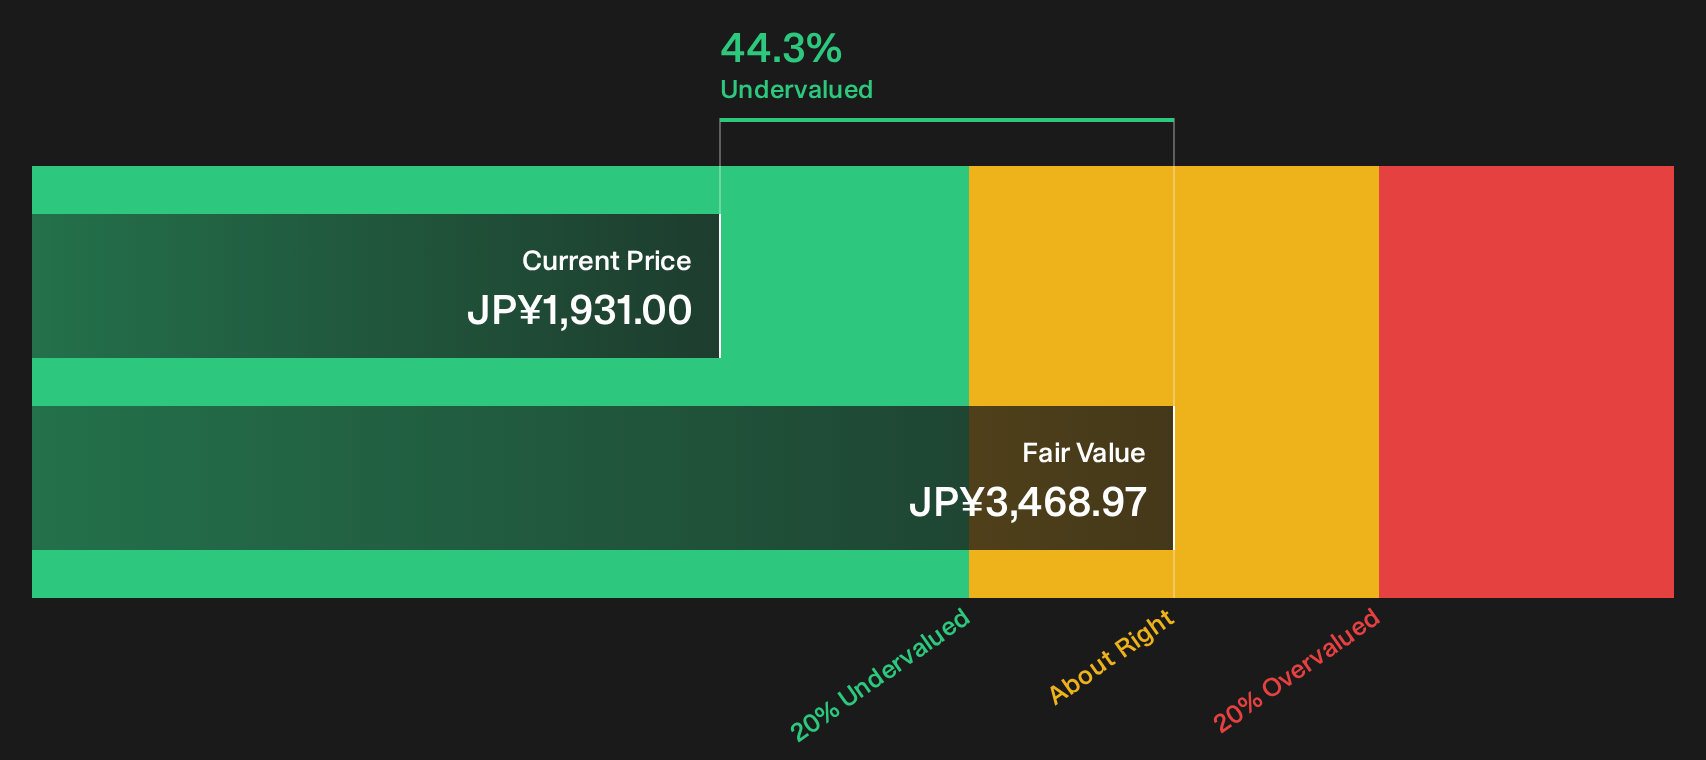
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DENSO for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 22 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on DENSO's value case can make the story feel murky, so review the numbers yourself and decide how convincing the upside looks. To see what the optimism is anchored to, take a closer look at the 4 key rewards
Looking for more investment ideas beyond DENSO?
If DENSO has sharpened your focus on value, do not stop here. Broader opportunity often sits in plain sight if you know where to look.
Use the Simply Wall Street Screener to quickly filter for different types of stocks that might fit your next move instead of relying on headlines alone.
- Target potential upside by scanning a curated pool of quality companies that look mispriced through 22 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses with sturdy finances and fundamentals via the list of solid balance sheet and fundamentals (23 results).
- Hunt for lesser known opportunities before the crowd notices them by checking the 76 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com