


EN
Precigen (PGEN) Earnings Turnaround Puts Its Valuation Back In Focus
Precigen (PGEN) is back in focus after its 2026 third quarter report showed revenue of US$74.15 million and net income of US$35.77 million, reversing last year’s loss.
Precigen’s share price has been volatile, with a 1-day share price return of 5.82% after the Q3 release. However, it is down 39.44% over 30 days and 31.05% over 90 days, while the 3-year total shareholder return of about 7x signals longer term momentum that short term weakness has not fully erased.
See how Precigen’s sharp earnings swing compares with other biotech stories on the move by checking our hand-picked 19 high quality undiscovered gems in the sector.
For Precigen, a sudden swing back to profit and a share price still under pressure set up a simple tension. Are you looking at a reset on fundamentals, or a sharp turn in sentiment that valuation now needs to unpack?
Most Popular Narrative: 65% Undervalued
Against a last close of $4.73, the analyst consensus Narrative on Simply Wall St anchors Precigen’s fair value at $13.65, implying a wide gap that hinges on how Papzimeos and the broader platform unfold under a 7.54% discount rate.
Rapid uptake of PAPZIMEOS in a sizable and previously underserved adult RRP population, combined with strong physician enthusiasm and broad label coverage, supports a multi year ramp in product revenue as pent up demand converts into treated patients.
Expanding indications, including the planned pediatric RRP trial and geographic expansion via the EMA marketing authorization application, create additional addressable markets that can extend the revenue growth curve and leverage existing commercial infrastructure.
See why 15 investors see Precigen as 65% undervalued.
Result: Fair Value of $13.65 (UNDERVALUED)
Still, the Precigen narrative leans heavily on PAPZIMEOS. As a result, slower RRP uptake or tougher payer discounts could quickly challenge those fair value assumptions.
Find out about the key risks to this Precigen narrative.
Another View On Precigen’s Valuation
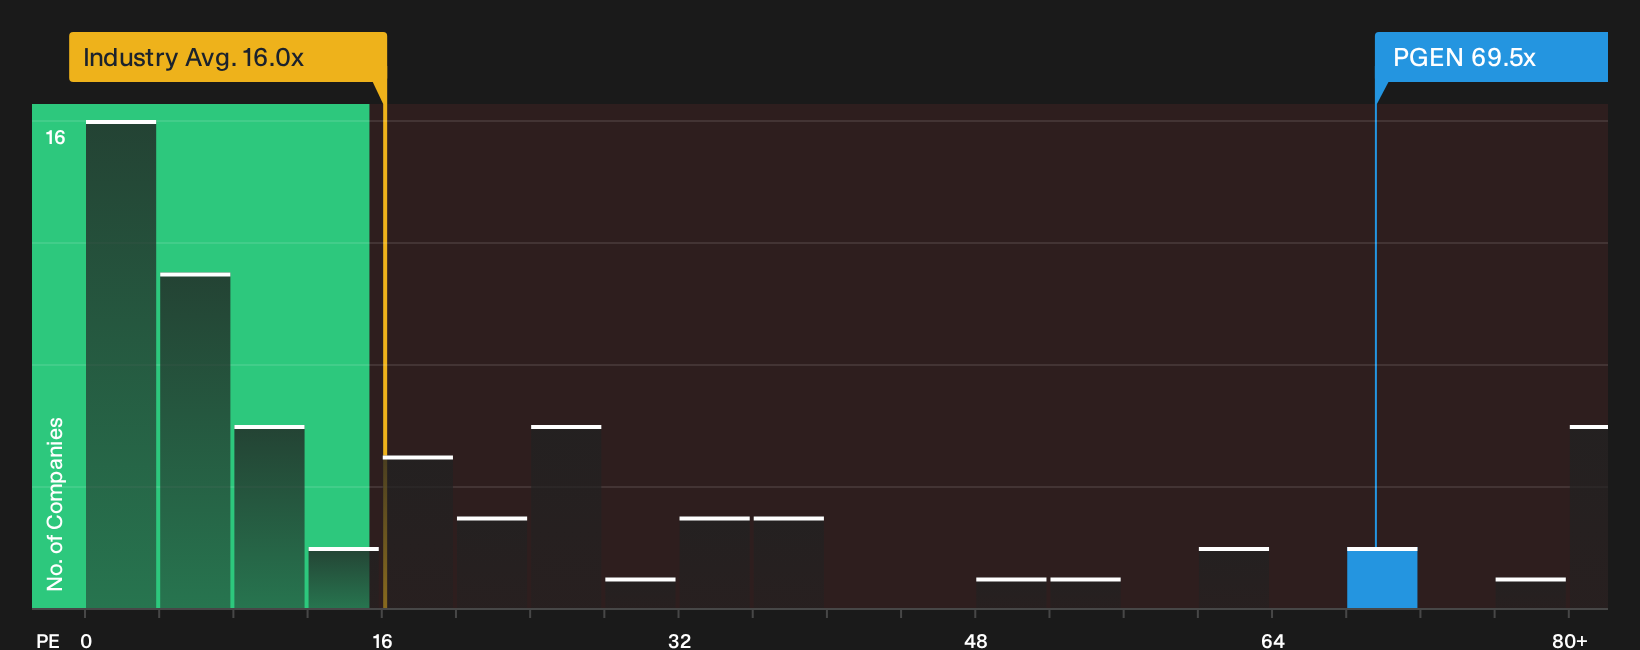
The first narrative leans on future earnings and a fair value estimate of $13.65. A simple P/E cross-check tells a different story. Precigen trades on a P/E of 69.5x, versus 16x for the wider US biotech group and a fair ratio of 33x, which points to a rich valuation that leaves less room for disappointment if execution slips.
For investors, the question is which signal carries more weight right now: the uplift implied by growth forecasts, or the premium multiple already embedded in today’s $4.73 price, and how comfortable you are with that gap if sentiment cools.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There are mixed views on Precigen so far, and both risk and reward are on the table. Consider acting promptly, review the underlying data carefully, and weigh the 3 key rewards and 5 important warning signs.
Looking for more investment ideas beyond Precigen?
If Precigen has your attention, do not stop there. Use the same discipline to scan for other opportunities that match your risk, income, and quality preferences.
- Target resilient performers by zeroing in on companies that score well on stability and fundamentals through our 30 resilient stocks with low risk scores.
- Hunt for mispriced quality by checking a curated 33 high quality undervalued stocks that blend stronger balance sheets with healthier cash flows.
- Build a watchlist of tomorrow’s potential breakouts by scanning a focused 19 high quality undiscovered gems that the broader market may not be paying attention to yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com