


EN
Rhythm Pharmaceuticals (RYTM) Could Be 15% Undervalued On Third Quarter Earnings
Rhythm Pharmaceuticals (RYTM) moved into focus after reporting third quarter 2026 results, with revenue of US$92.13 million and a net loss of US$41.37 million from continuing operations.
The earnings release appears to have reset expectations around Rhythm Pharmaceuticals, with the share price up 21.94% over the past week and a 25.51% 1 month share price return. The 1 year total shareholder return of 16.71% sits against a much larger 3 year total shareholder return of almost 3x that level, hinting that recent momentum is rebuilding after a pause rather than starting from scratch.
Scan other rare disease plays that show similar momentum and balance-sheet resilience using our hand picked list of solid balance sheet and fundamentals (25 results) alongside Rhythm Pharmaceuticals.
Rhythm Pharmaceuticals now trades at US$113.94, while analyst targets cluster around US$140 and one intrinsic estimate points to a much lower level. Which reference point deserves more weight as the valuation work starts?
Most Popular Narrative: 15% Undervalued
Rhythm Pharmaceuticals is framed as undervalued in the leading narrative, with a fair value of $134 versus the recent close at $113.94. This puts the discussion squarely on how durable its rare disease opportunity set really is. According to peter_4mgsy, an investor in the Simply Wall St Community who authored the narrative, the investment case leans heavily on how far IMCIVREE and follow on assets can extend across MC4R driven obesity disorders.
Rhythm Pharmaceuticals is a high-growth commercial-stage company targeting orphan neuroendocrine disorders linked to MC4R pathway dysfunction (genetic obesity). Having expanded from one disorder to multiple approved indications, the company has additional opportunities ahead to expand its portfolio. I rate RYTM a BUY, driven by expected double-digit revenue growth, a broader targeted-obesity portfolio, and stronger-than-expected patient uptake.
See why 5 investors see Rhythm Pharmaceuticals as 15% undervalued.
Result: Fair Value of $134 (UNDERVALUED)
Still, the Rhythm Pharmaceuticals story can wobble if IMCIVREE uptake slows, or if clinical trial setbacks change how investors view the rare obesity pipeline.
Find out about the key risks to this Rhythm Pharmaceuticals narrative.
Another View: Rhythm Pharmaceuticals Looks Expensive On Sales
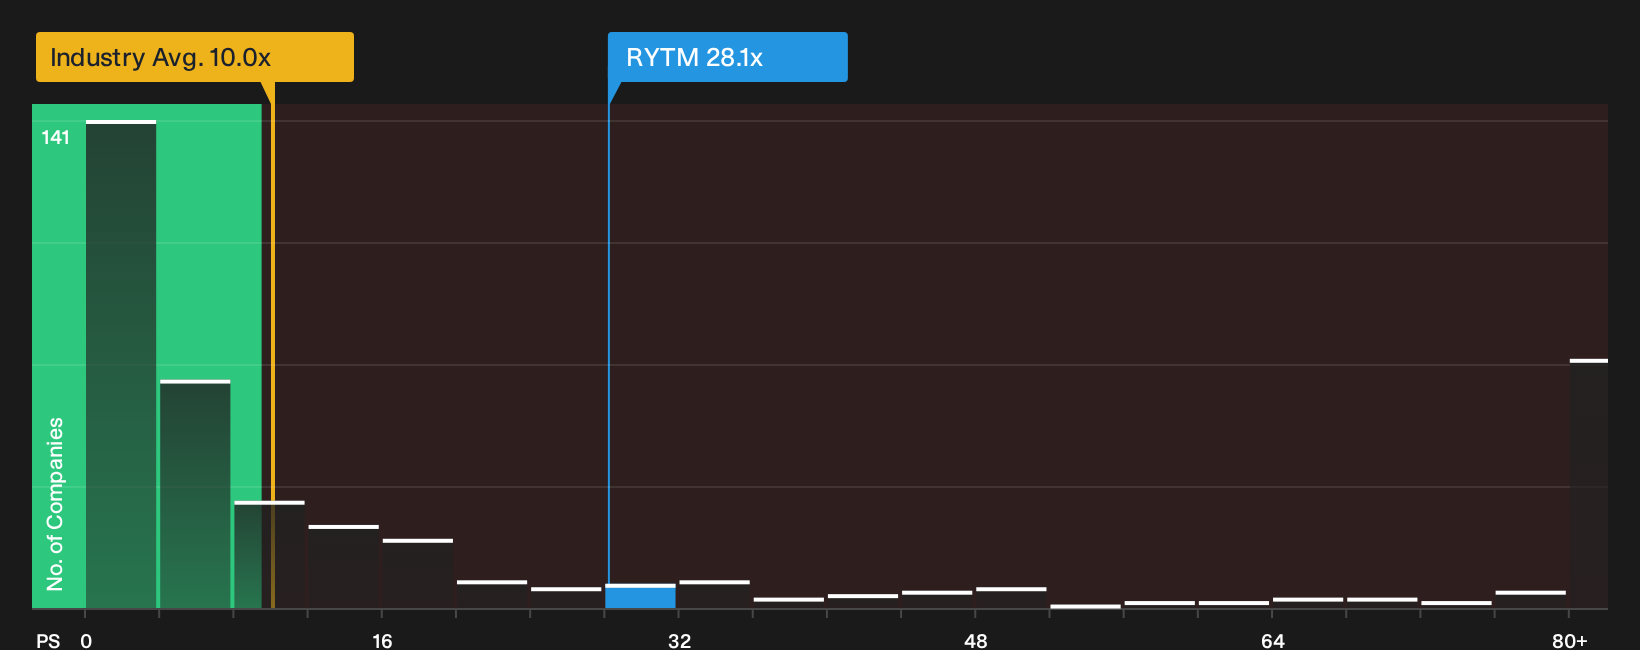
The fair value story around Rhythm Pharmaceuticals shifts once you look at the simple P/S number instead of cash flows. The stock trades on a P/S of 28.1x, while the US Biotechs industry averages 9.7x and peers sit around 8.9x. The fair ratio sits even lower at 16.1x.
That kind of gap suggests investors are paying a heavy premium on current revenue, which adds valuation risk if forecasts or sentiment change. It raises a practical question for you as a shareholder: Is that premium level of optimism really the anchor you want to use for your own valuation work?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Optimistic or cautious after all this, the fastest way to cut through the noise is to review the numbers directly and stress test your own thesis. To see what investors currently view as the upside case, start with the 3 key rewards.
Looking for more Rhythm Pharmaceuticals style investment ideas?
If you stop with Rhythm Pharmaceuticals alone, you may miss other opportunities with similar traits, so broaden your watchlist using focused screeners that surface clear, data backed ideas.
- Spot potential mispricing early by reviewing companies that screen as 33 high quality undervalued stocks based on strong fundamentals and supportive balance sheet metrics.
- Prioritise resilience by checking businesses that score well on stability using the 30 resilient stocks with low risk scores to filter out weaker profiles before they hit your shortlist.
- Get ahead of the crowd by tracking future contenders through the 19 high quality undiscovered gems before they appear on everyone else's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com