


EN
How Investors Are Reacting To PulteGroup (PHM) Earnings Estimate Cuts
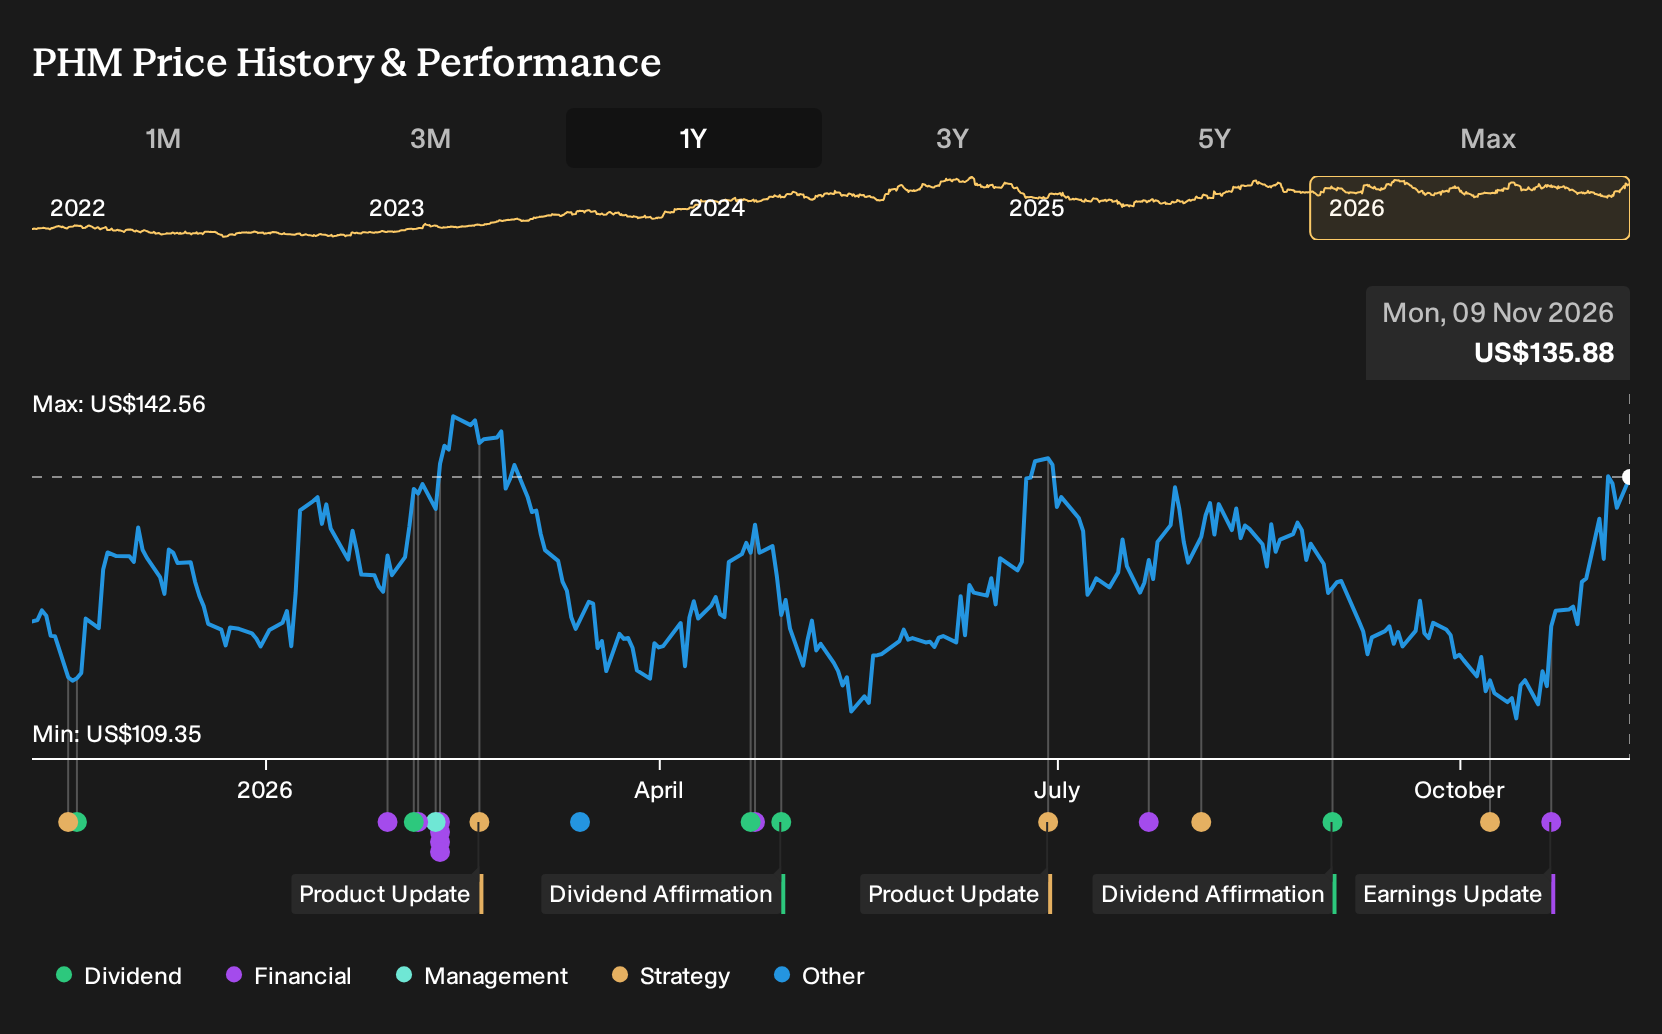
- PulteGroup recently faced downward revisions to earnings and revenue estimates for the current and next fiscal years, signaling pressure on demand, pricing, or costs in its core homebuilding operations.
- The gap between weaker estimates and PulteGroup's long run track record of strong compounded returns highlights how quickly sentiment can shift when forward fundamentals look less certain.
- We will now assess how PulteGroup's weaker earnings outlook could reshape its investment narrative, which has been built around margins, mix, and execution.
PulteGroup Investment Narrative Recap
To own PulteGroup, you need to be comfortable with a homebuilder that leans heavily on mix, margins and disciplined land use rather than fast top line expansion. The analyst consensus Narrative on Simply Wall St assumes the business keeps shifting toward build to order and higher priced communities, which could support earnings quality even if headline growth stays modest.
The recent cuts to earnings and revenue estimates highlight how sensitive the story is to homebuyer demand, incentives and regional pricing. The key near term swing factor remains the balance between affordability incentives and gross margin protection. The biggest risk is that weak Western markets and sustained incentives keep pressuring profitability longer than expected.
Among recent developments, the Zacks commentary on PulteGroup assigning a Rank #4 and pointing to a 10.4% expected EPS decline this quarter is most relevant. It links directly to the concern that softer home sale revenues, already seen in 2026, could combine with incentives and regional softness to weigh on near term earnings power.
For you as a shareholder, the question is how that more cautious near term outlook sits against the longer term catalysts in the analyst consensus Narrative on Simply Wall St, such as the build to order mix, large option controlled land bank and cost discipline. If execution on those pillars holds, sentiment around short term estimate cuts may matter less than the durability of margins and returns over several years.
PulteGroup Forecast Assumptions In Focus
PulteGroup's forward story hinges on fairly modest top line expansion and a measured lift in profitability rather than a surge in volumes. Analysts are penciling in revenue growth of 2.0% a year over the next 3 years, which points to a slow build in sales rather than a big reset in scale. Profit margins are modeled to edge up from 11.2% today to 11.4% in 3 years, so the frame is about small improvements in efficiency and mix instead of a step change in returns.
On earnings, the consensus points to profit of US$1.9b by 2029 compared with US$1.8b today. That is an increase of roughly US$0.1b in absolute terms, with analysts expecting this to translate into earnings per share of US$11.69 by around October 2029. The relatively tight gap between current and projected profit underlines that the market is not baking in a large earnings increase, which leaves sentiment more exposed if housing conditions weaken again or incentives stay heavier for longer than analysts currently build into their models.
Valuation work ties these operating forecasts to a higher implied P/E multiple over time. To reach the analyst targets, PulteGroup would need to trade at about 14.4x those 2029 earnings compared with 12.6x today and above the current 13.1x for the broader US Consumer Durables peer group. That kind of rerating usually depends on investors staying confident that the mix shift toward active adult and move up buyers, the build to order focus and the cost discipline can sustain the modeled margins through different parts of the housing cycle.
PulteGroup's narrative projects revenues of US$17.0b and earnings of US$1.9b by 2029, based on analysts expecting 2.0% yearly revenue growth and an earnings increase of about US$0.1b from US$1.8b today.
Uncover why PulteGroup's fair value aligns with its current price.
Exploring Other Perspectives
One alternate view on PulteGroup leans heavily on its cash generation. The most optimistic analysts were projecting revenue of about US$18.0b and earnings near US$2.2b by 2029 before this earnings reset. That is a much brighter story than today’s estimate cuts, and it shows how sharply opinions can differ. Treat this as a cue to compare several narratives and decide which assumptions feel realistic to you, knowing both sets of forecasts were built before the latest news.
Explore 4 other PulteGroup fair value estimates, including one that suggests as much as 22% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your PulteGroup research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for PulteGroup. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PulteGroup's overall financial health at a glance.
Looking for more PulteGroup style investment ideas?
If the PulteGroup story has sharpened your sense of what you want from a business, use that filter across the broader market. The Simply Wall St Screener can help you quickly surface stocks that match the mix of quality, resilience and valuation you care about most.
- For investors who want income that can potentially hold up through different parts of the cycle, review a curated set of 6 dividend fortresses that combine higher yields with solid underlying businesses.
- If capital preservation ranks high on your checklist, narrow the field to companies screened as 30 resilient stocks with low risk scores and see which balance sheets and earnings profiles look more robust to you.
- When you want to cast the net wider for quality beyond the usual large caps, scan through 19 high quality undiscovered gems that pair strong fundamentals with less crowded investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com