


EN
Woodward (WWD) Rallies As Investors Revisit Whether The Stock Is Fully Valued
Woodward (WWD) is back on investor watchlists after a recent price move, with the shares closing at US$332.91. The shift has traders reassessing how the aerospace and industrial supplier is currently valued.
Recent trading has shifted the tone around Woodward, with a 1-day share price return of 4.92% and a 7-day share price gain of 4.17%. However, the 90-day share price return is down 6.64%, while the 1-year total shareholder return is 23.08%, which hints at longer term optimism despite some shorter term volatility.
Capture this shift in Woodward sentiment by scanning a curated set of resilient industrial and aerospace peers through the 30 resilient stocks with low risk scores.Woodward now trades only slightly below one valuation estimate while sitting at a much steeper discount to analyst targets. Is the market being sensibly cautious, or is it too slow to adjust to the latest move?
Most Popular Narrative: 22% Undervalued
Woodward is trading at $332.91 against an analyst consensus fair value of about $424.67, and the analyst consensus Narrative on Simply Wall St links that gap to a mix of margin expectations, capital returns and sector de rating.
Current numbers, including raised 2026 EPS guidance, high 20% plus segment margins, and about $700 million of planned capital returns, indicate that the market assigns significant value to Woodward while still leaving room if the business continues to outperform earlier margin and cash generation ambitions.
See why 13 investors see Woodward as 22% undervalued.
The Narrative framework rests on an 8.13% discount rate, analyst forecasts for revenue to reach $5.3b and earnings of $835.5m by 2029, and an implied future P/E of 36.4x that sits above the current US Aerospace & Defense industry level of 34.4x. It also builds in a modest decline in shares outstanding of 1.37% per year and a profit margin profile moving from 13.2% to 15.7%, which together help explain why the inferred upside to the $424.67 fair value is larger than the 2% gap to the $339.73 future cash flow estimate in the SWS DCF model.
Investors weighing Woodward at today’s price are effectively being asked to decide how comfortable they are with those embedded assumptions on growth, margins and valuation multiples, and whether the sector wide reset in aerospace P/E ratios justifies leaning more on the DCF based view or on the higher analyst target. Result: Fair Value of $424.67 (UNDERVALUED)
Still, Woodward’s thesis could be tested if large factory projects run into cost or productivity issues, or if commercial aerospace aftermarket growth settles below analyst expectations.
Find out about the key risks to this Woodward narrative.
Another View: Woodward’s P/E Sends A Different Signal
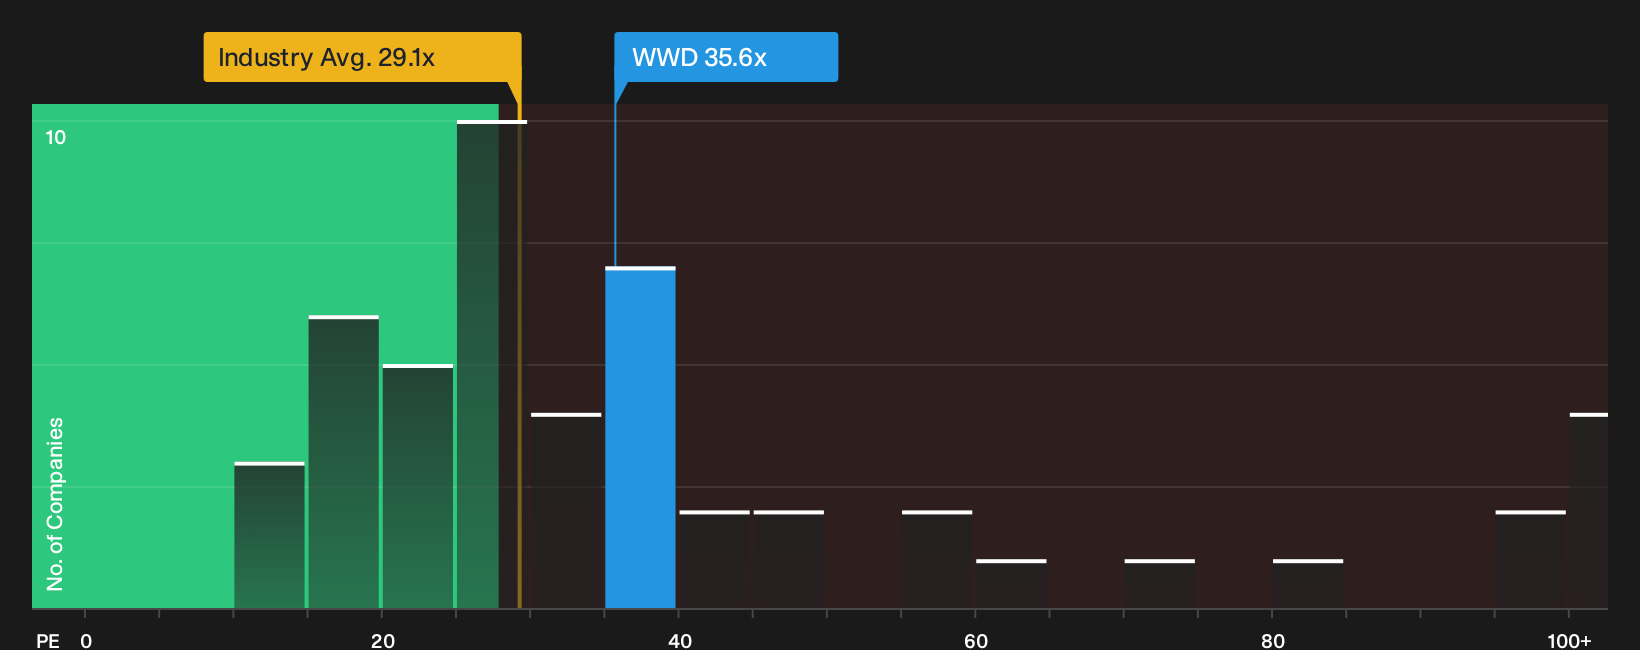
While the Narrative and SWS DCF work suggest Woodward is modestly undervalued, the P/E snapshot tells a different story. The stock trades on 35.6x earnings compared with a fair ratio of 27x, the US Aerospace & Defense group on 27.2x, and peers at 29.5x. That rich premium raises a simple question for investors: Is the current price baking in too much good news already, or is this the kind of quality that can sustain a higher multiple over time?
For a closer look at how those earnings multiples stack up against what the numbers imply as a fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Woodward in this piece leans optimistic, yet pricing and expectations are finely balanced. It pays to check the details yourself and move quickly while the data is fresh. To see what optimistic investors are focusing on, review the 4 key rewards.
Looking for more investment ideas beyond Woodward?
Do not stop with Woodward. Fresh ideas often come from comparing it to other high quality businesses that match your risk tolerance and income goals.
- Target resilient quality by scanning a 30 resilient stocks with low risk scores that keeps potential downside front of mind while you look for steadier compounders.
- Hunt for value by reviewing a 33 high quality undervalued stocks that filters for strong fundamentals paired with prices that still look reasonable.
- Boost your income focus by checking a 6 dividend fortresses that narrows in on higher yielding payouts backed by solid financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com