


EN
How Higher Dividends Will Impact Darden Restaurants Stock Investors
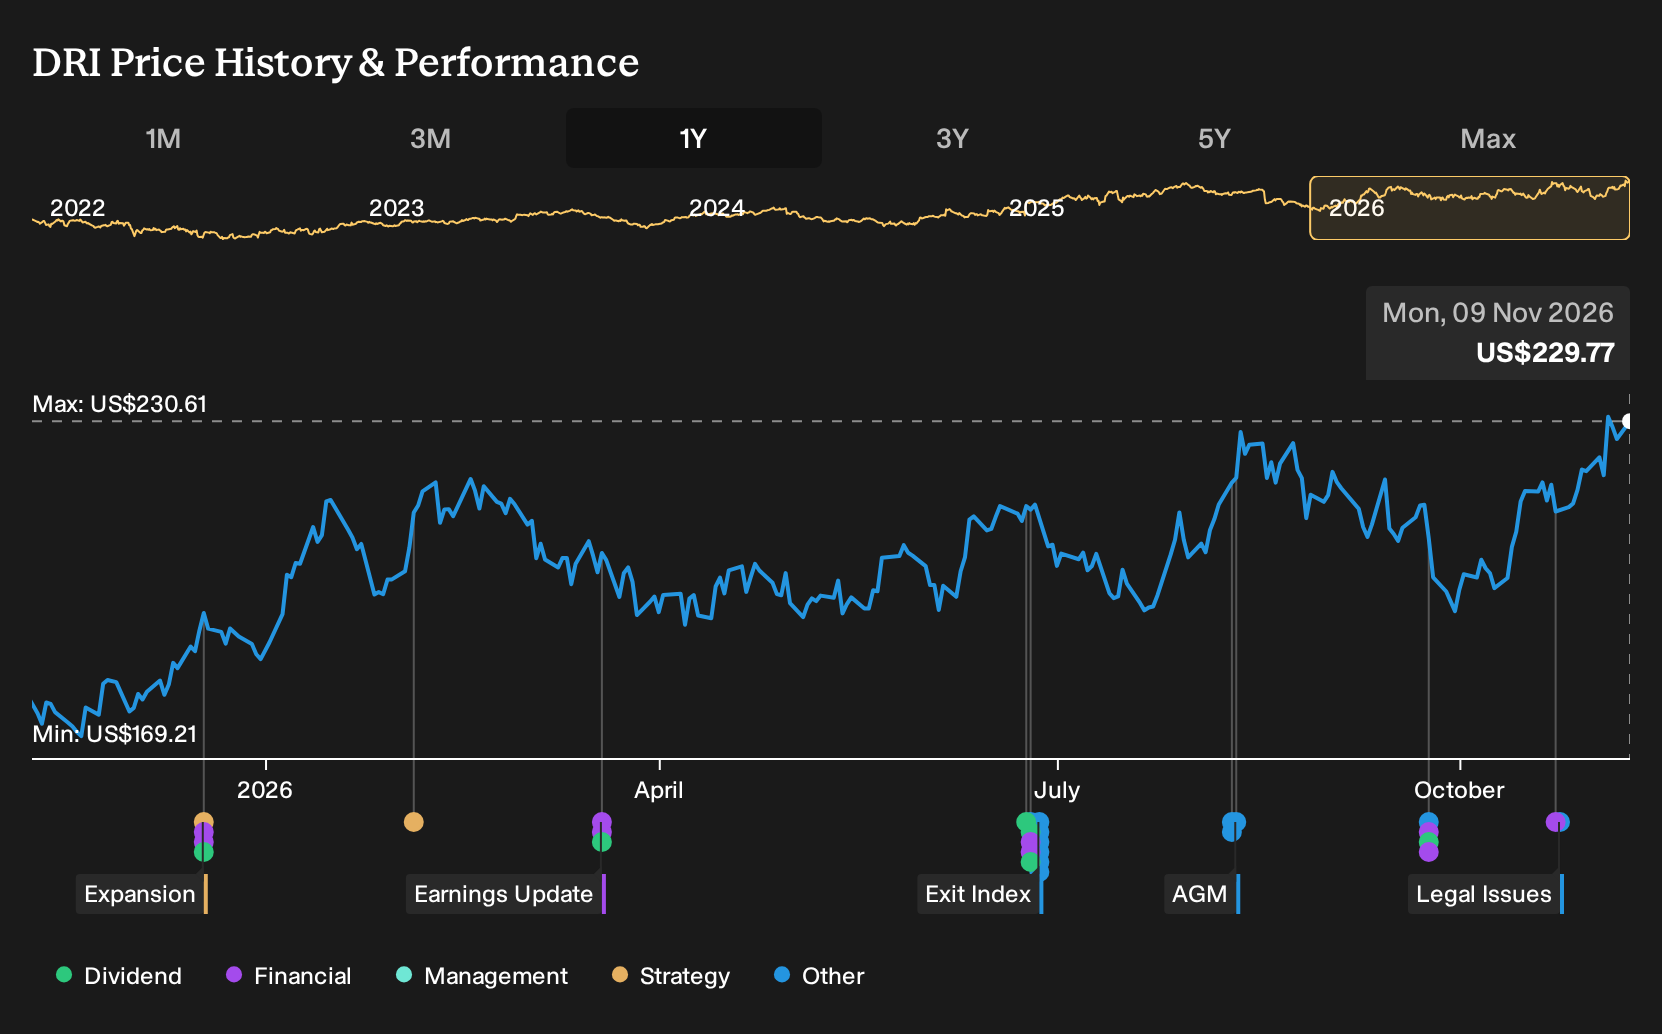
- Darden Restaurants recently raised its quarterly dividend by 8% to $1.62 per share, with the payout aligned to roughly 58% of guided earnings and backed by free cash flow from its restaurant operations.
- The decision to prioritize cash distributions and potentially trim share buybacks if required highlights how Darden Restaurants is managing capital allocation around recurring cash generation rather than relying on more variable repurchase activity.
- We will now look at how Darden Restaurants' higher dividend commitment might influence the broader investment narrative built around its cash flows.
Scan income-focused opportunities that are similar to Darden Restaurants' dividend profile by reviewing our hand picked list of 6 dividend fortresses
Darden Restaurants Investment Narrative Recap
Darden Restaurants asks you to believe that casual dining traffic, pricing and brand mix can support steady earnings while new units and concepts do more of the heavy lifting. The higher dividend signals that management is comfortable tying more of that profit stream to regular cash payouts. The short term swing factor still sits with same restaurant sales, especially at Olive Garden, which the analyst consensus Narrative on Simply Wall St frames as a key driver.
The biggest operational risk right now is that guest counts across casual dining, and especially Olive Garden weekday lunches, stay soft enough to pressure margins. The dividend lift does not change that core issue in a material way. It mainly sharpens the trade off. If traffic disappoints or input costs stay sticky, there is less room to lean on buybacks or incremental debt without squeezing flexibility.
The fresh dividend move links directly to one of the major themes in the analyst consensus Narrative on Simply Wall St. That view leans on Darden Restaurants using its diversified portfolio, measured pricing and new store openings to keep earnings resilient. A payout near 58% of guided profit, funded by free cash flow, fits a story where cash generation is expected to remain solid but not explosive.
For catalysts, your attention still goes first to execution at Olive Garden, LongHorn and the newer formats rather than to capital returns. Uber Direct at Olive Garden, continued unit growth and the roll out of smaller Yard House boxes all speak to how the group is trying to support sales density and margins. The richer dividend simply means that any stumble on those operational projects might now show up faster in choices around buybacks or leverage.
Darden Restaurants is tied to analyst assumptions that revenues reach US$15.6b and earnings land at US$1.5b by 2029, implying 5.3% yearly revenue growth and an earnings increase of about US$300m from current earnings of US$1.2b.
Uncover why Darden Restaurants' fair value suggests it is currently priced roughly in line with its current value.
Exploring Other Perspectives
One alternate view says the real swing factor for Darden Restaurants is not the richer dividend, but whether new restaurant spending actually earns its keep. The most cautious analysts previously pencilled in only about US$15.5b of revenue and US$1.4b of earnings by 2029, which reflects a more pessimistic story. These expectations came before this dividend increase, so you may see those forecasts shift. That is why it can help to compare several narratives before deciding how this latest payout move fits your own outlook.
Explore 2 other Darden Restaurants fair value estimates, including one that suggests as much as 9% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Darden Restaurants research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Darden Restaurants. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Darden Restaurants' overall financial health at a glance.
Looking for more investment ideas beyond Darden Restaurants?
Once you have a handle on Darden Restaurants and its dividend commitment, it can help to widen the lens and compare it with other businesses that match the kind of income, quality or risk profile you prefer. The Simply Wall St Screener lets you scan groups of stocks quickly so you can focus your time on the handful that truly merit deeper work.
- If income resilience is a priority, consider building a watchlist around companies described as 6 dividend fortresses and see which ones align with your yield and payout preferences.
- For investors who want a balance of quality and valuation, you can filter for 33 high quality undervalued stocks that combine healthy fundamentals with more modest pricing.
- If capital preservation ranks higher for you than chasing maximum upside, narrow the field to 30 resilient stocks with low risk scores and compare their metrics with what you see at Darden Restaurants.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com