


EN
Is Lowered Sales Guidance Altering The Investment Case For CONMED (CNMD)?
- CONMED reported third quarter 2026 sales of US$335.56 million and net income of US$19.8 million, with basic and diluted EPS from continuing operations at US$0.66, and modestly adjusted full year 2026 net sales guidance to a US$1.36b to US$1.366b range.
- Profitability moved ahead of the prior year period even as both quarterly and nine month sales were slightly lower, which highlights how CONMED’s current story is leaning heavily on margin execution rather than on top line expansion alone.
- The focus now turns to how CONMED’s improved earnings but slightly reduced full year sales outlook may reshape the broader investment narrative.
CONMED Investment Narrative Recap
To own CONMED, you need to be comfortable with a story that leans on margin work and product mix, not rapid top line expansion. The third quarter showed that trade off clearly, with earnings stepping up while sales for both the quarter and nine months were slightly lower. For now, the most important short term catalyst is continued execution in higher margin platforms like AirSeal, Buffalo Filter and BioBrace, which underpins the analyst consensus Narrative on Simply Wall St.
The biggest near term risk remains sluggish organic growth, especially in U.S. orthopedics, combined with a balance sheet that carries meaningful debt and higher interest costs. The modest tweak to 2026 net sales guidance looks manageable in that context and does not materially change the near term story, although it keeps the spotlight on whether management can convert its focus on premium product lines into steadier mid single digit revenue growth.
The updated 2026 net sales outlook to a US$1.36b to US$1.366b range is the announcement that matters most here. It grounds expectations for what the current product portfolio can realistically deliver while CONMED prioritizes margin and cash generation. For an investor, that range helps frame whether the current operating plan lines up with the earnings and revenue path implied in external forecasts.
That guidance bracket, sitting only slightly refined versus the prior range, ties directly into the catalysts around minimally invasive surgery, smoke free operating rooms and biologic soft tissue repair adoption. If uptake of AirSeal, Buffalo Filter and BioBrace tracks the adoption curves analysts are watching, the guidance looks like a reasonable bar to measure execution against. If procedure volumes or product traction weaken, pressure on both that sales band and the margin story would likely build.
CONMED's narrative projects US$1.6b revenue and US$179.7 million earnings by 2029. That path assumes 4.2% yearly revenue growth and an earnings increase of about US$123.2 million from US$56.5 million today.
Uncover why CONMED's fair value indicates a 12% potential downside to its current price, which leaves little room for error.
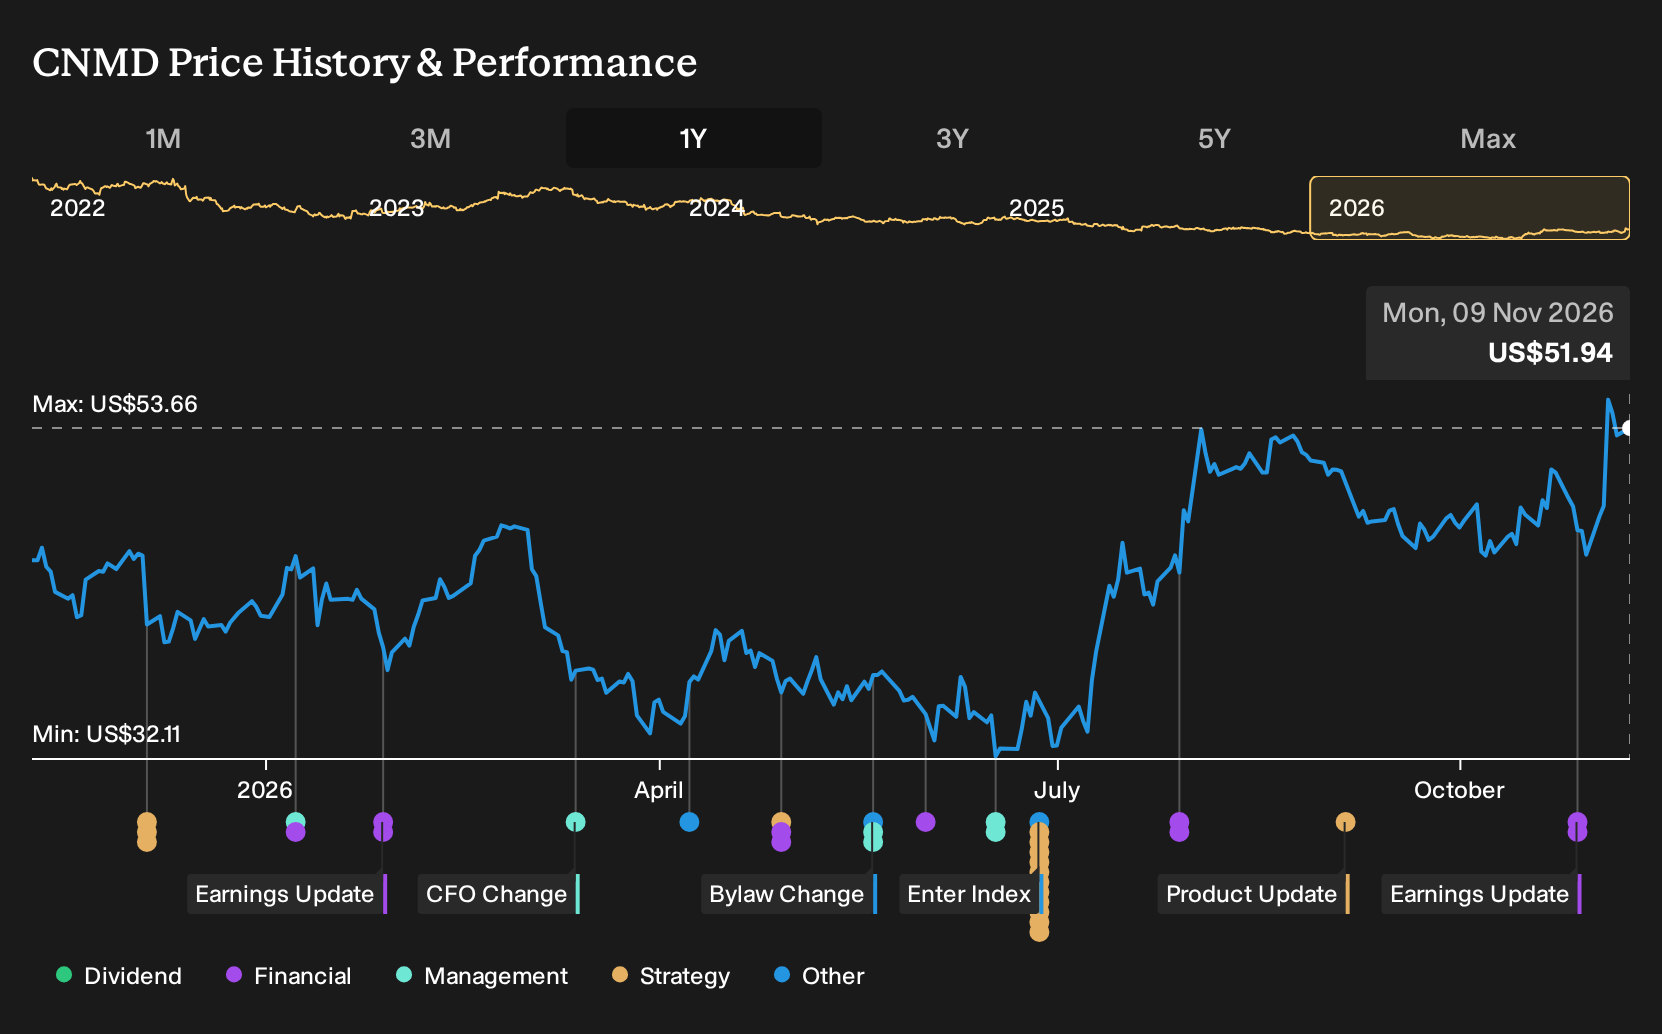
Exploring Other Perspectives
Some bullish analysts focus less on the trimmed sales outlook and more on CONMED’s capital plans. Before this earnings update, they were working off forecasts of about US$1.6b in revenue and US$171.8 million in earnings by 2029. That is a more optimistic storyline, and it could shift as new results land.
Explore 3 other CONMED fair value estimates, including one that suggests as much as 109% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CONMED research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CONMED. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CONMED's overall financial health at a glance.
Looking For More Investment Ideas Beyond CONMED?
Once you have a view on CONMED, it can help to compare that thesis with other stocks that share some of the same qualities you care about, whether that is value, resilience, or balance sheet strength. The Simply Wall St Screener lets you stack those filters side by side and see which companies fit your checklist in minutes.
- If you care about price discipline and potential mispricing, start by scanning a 33 high quality undervalued stocks that match quality and valuation filters in one place.
- If your priority is capital strength and staying power, look through a list of solid balance sheet and fundamentals (25 results) to compare leverage, liquidity and fundamental resilience.
- If you want steadier income on top of capital returns, focus on a 6 dividend fortresses that combine higher yields with more durable business profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com