


EN
Sanmina (SANM) Jumped, But What Is Behind The Latest Attention?
Why Sanmina’s Latest Earnings Matter For Shareholders
Sanmina (SANM) just released fourth quarter and full year results for the period ended October 3, 2026, with higher reported sales, net income and earnings per share compared with the prior year.
The latest report landed alongside sharp market swings for Sanmina. The company recorded a 1-day share price return of 11.11% to US$149.64 after a 30-day share price decline of 31.20%. Its 1-year total shareholder return is down 14.21%, while the return over five years stands at 270.67%.
Scan Sanmina’s earnings surprise against a curated field of hardware and manufacturing peers by reviewing our hand picked list of solid balance sheet and fundamentals (25 results) that have recently delivered resilient results.
Sanmina just delivered strong full year figures after a steep 30 day share price slide and a sharp single day rebound. Is the recent jump a blip in a larger reset, or the start of fresh upside as valuation adjusts?
Most Popular Narrative: 40% Undervalued
On the analyst consensus Narrative on Simply Wall St, Sanmina’s fair value sits at $250 against a last close of $149.64. This frames this earnings jump inside a much larger valuation gap built on detailed revenue and earnings forecasts that also factor in risk.
Sanmina is expanding vertical integration in areas such as metal fabrication for AI racks, high technology PCBs, transformers and liquid cooling and test capabilities. This is intended to capture a larger share of each AI and cloud rack build and support higher gross margin and operating margin over time.
See why 20 investors see Sanmina as 40% undervalued.
Result: Fair Value of $250 (UNDERVALUED)
Still, the bullish Sanmina story can unravel quickly if AI rack demand softens against its US$2.2b inventory build, or if governance concerns resurface.
Find out about the key risks to this Sanmina narrative.
Another View On Sanmina’s Valuation
The Simply Wall St DCF model lands in a very different place to the $250 analyst fair value, with an estimate of future cash flow value around $42.82 per share. That points to Sanmina trading well above this cash flow based figure and raises the question of which lens you trust more.
For a closer look at how that cash flow view is built, take a moment with the Look into how the SWS DCF model arrives at its fair value..
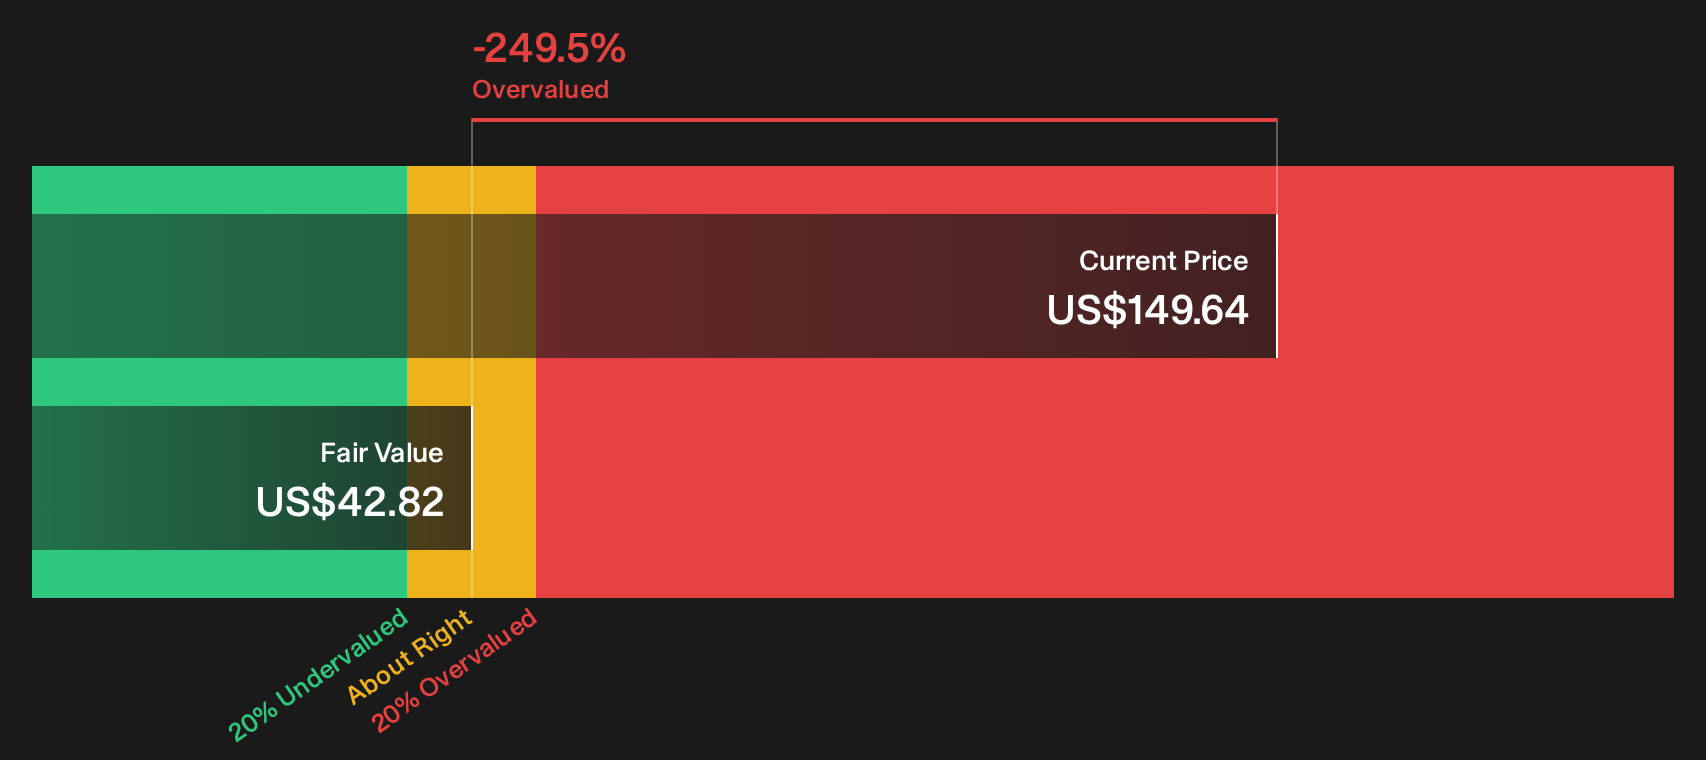
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sanmina for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed feelings about Sanmina after these results is a rational place to be. Consider reviewing the underlying data promptly and weighing the company’s 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Sanmina?
If Sanmina has sharpened your focus on opportunity versus risk, do not stop here. Broadening your watchlist now can help you spot the next mispriced setup early.
- Target potential mispricings by scanning a curated pool of quality stocks using the 33 high quality undervalued stocks.
- Prioritise resilience and sleep better at night by reviewing companies highlighted in the 30 resilient stocks with low risk scores.
- Get ahead of the crowd by researching under followed opportunities surfaced in our 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com