


EN
European Travel Stocks Investors Are Watching As Peace Talks Return
Peace talks between Russia and Ukraine are back on the table, and markets are starting to imagine what a cooler geopolitical climate could mean for travel, leisure and consumer spending across Europe. If risk appetite returns and energy worries ease, the companies most tied to tourism and discretionary budgets may see investor attention shift fast. This article walks through three European stocks linked to that de-escalation story and explains how each could be positioned if the news flow keeps improving.
The three stocks below are a starting sample. The full screen pulled up 14 more European travel and consumer discretionary companies whose stories around de-escalation and spending resilience are just as compelling.
To size up the wider opportunity set and identify which businesses match your own risk and return preferences, head straight into the European Travel and Consumer Discretionary Beneficiaries of Ukraine-Russia De-escalation screener to filter, analyze and focus on potential high conviction ideas.
International Consolidated Airlines Group (LSE:IAG)
Overview: International Consolidated Airlines Group is a major European airline group whose passenger, cargo and loyalty businesses are tightly linked to tourism trends and travel demand across key long haul and regional routes.
Market Cap: £19.6b
For a theme built around European travel recovering as geopolitical risk cools, International Consolidated Airlines Group sits near the middle of the story. The analyst consensus Narrative on Simply Wall St highlights one earnings engine that is less exposed to fuel swings and flight disruptions than the core flying business.
"Capital light growth in Loyalty and Holidays, where operating profit was £469m in 2025 with an 18% margin and further profit growth in H1 2026, provides a high margin earnings stream that can lift group profitability and smooth cash flow relative to the core airline business."
What happens to that high margin engine if a single cost pressure or demand shift changes how easily IAG can hold its pricing power?
If that pricing power question is front of mind, the full narrative for International Consolidated Airlines Group maps how loyalty cash flows, fuel costs and demand swings could be decoupling beneath the surface.

Ryanair Holdings (ISE:RYA)
Overview: Ryanair Holdings runs a large low cost airline focused on short haul European leisure routes, closely linked to discretionary travel budgets.
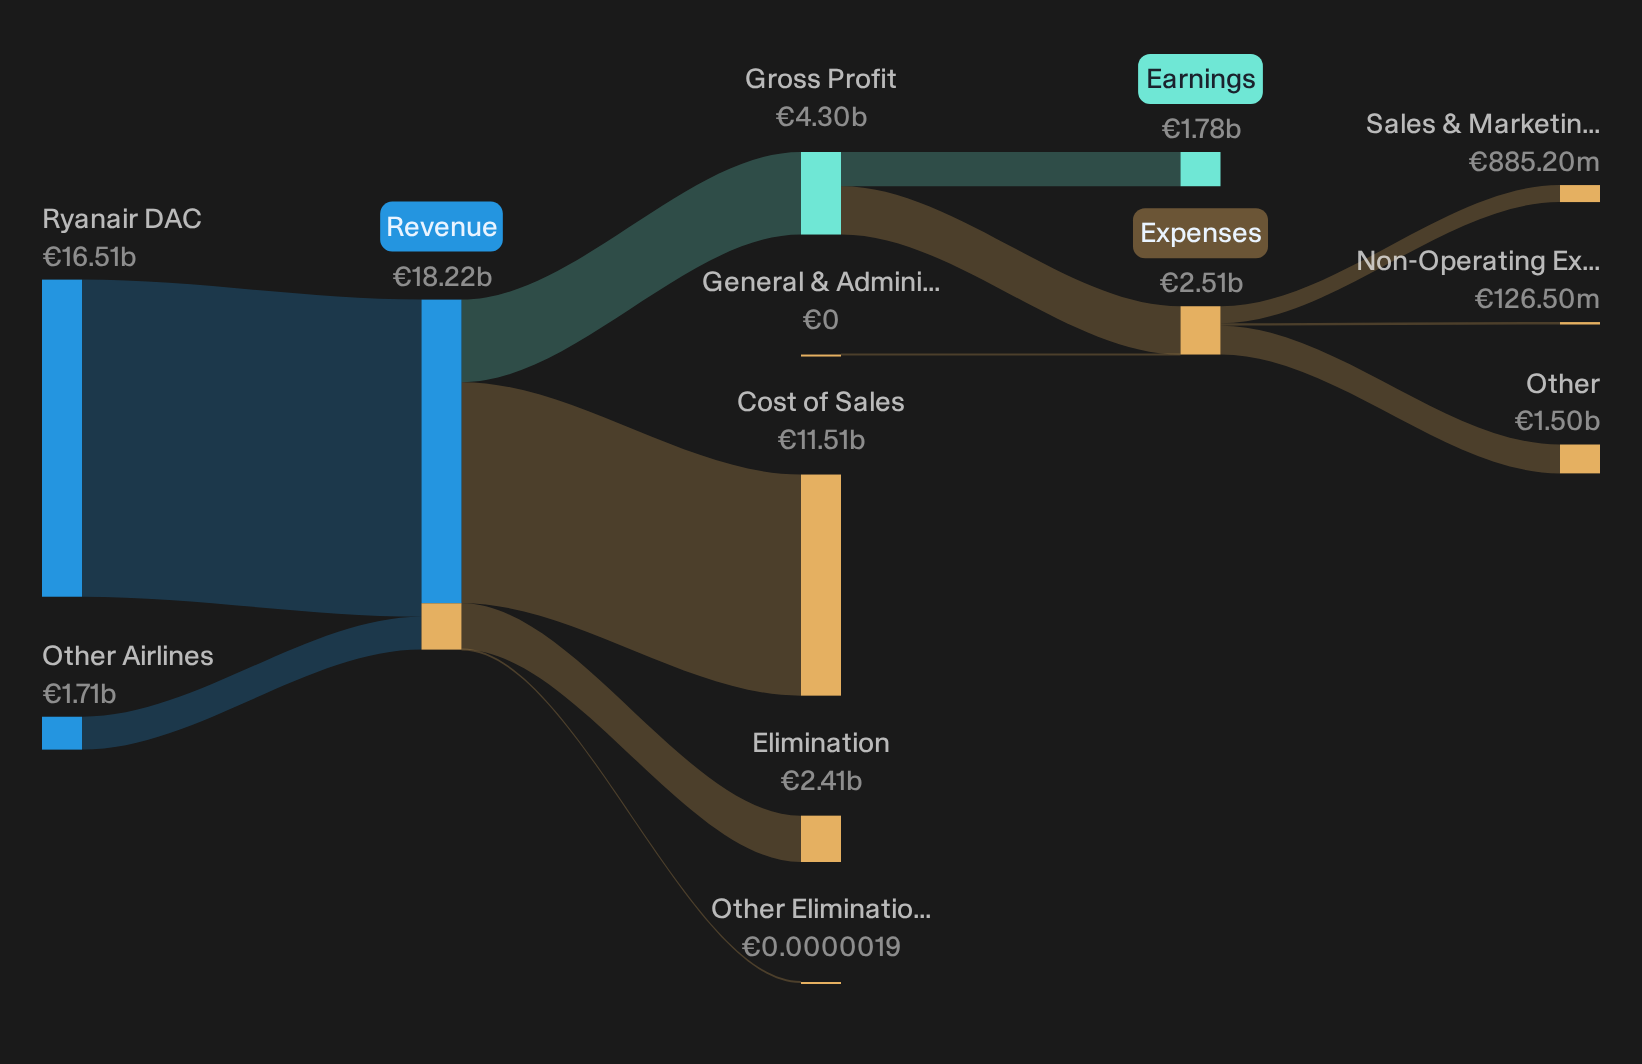
Operations: The group generates about €16.5b from Ryanair DAC and €1.7b from Other Airlines, with smaller eliminations adjusting intra-group activity.
Market Cap: €27.7b
For a theme built around European travel potentially benefiting from lower geopolitical risk and cheaper energy, Ryanair Holdings is a pure-play volume carrier that many investors watch closely. The analyst consensus Narrative on Simply Wall St highlights one operational lever tied directly to that context.
"Completion of the 210 Gamechanger program by early 2026 and the phased introduction of MAX 10 aircraft from 2027 will increase seats per flight while cutting fuel burn per flight."
The key question is what happens if pressure on fares or costs changes just as this capacity and efficiency plan reaches full speed.
If that timing risk is what you are weighing, the full narrative for Ryanair Holdings explains how Ryanair Holdings could balance accelerating capacity, pricing power and any demand wobble.
Norwegian Air Shuttle (OB:NAS)
Overview: Norwegian Air Shuttle runs a Nordic-focused airline network with international routes, where passenger demand is closely tied to European travel confidence and fuel costs.
Operations: Norwegian Air Shuttle generates about NOK 30.9b from the Norwegian segment and NOK 8.1b from Widerøe, with minor segment adjustments.
Market Cap: NOK 14.0b
Norwegian Air Shuttle links the de-escalation theme directly to people getting back on planes across the Nordics and wider Europe. The analyst consensus Narrative on Simply Wall St frames that story around a multi-year push to lift profitability rather than just chase volume.
"Program X is still rolling through Norwegian Air Shuttle with NOK 321 million delivered in the latest quarter and a stated goal of more than NOK 1.25b in profitability improvement by 2026."
The real swing factor is how one still-evolving cost pressure ultimately shapes the gap between headline passenger growth and lasting margin strength.
That cost pressure is only half the story, and the full narrative for Norwegian Air Shuttle shows how Norwegian Air Shuttle could turn Program X savings into accelerating cash generation and resilience.

Seeking Alternatives Before The Crowd?
Fresh opportunities move fast. Breakout themes, flying momentum and quietly dropping valuations rarely stay under the radar for long. Scan curated ideas before the crowd and get in early.
- Spot cash rich companies that still trade like they are being ignored and comb through a curated 16 high quality undervalued stocks while it matters.
- Ride structural demand in electricity, data and electrification and scan a focused group of 42 power grid technology and infrastructure stocks before that story is fully priced in.
- Zero in on businesses compounding quietly in the background and sift through a hand picked set of 5 high quality undiscovered gems before attention floods in.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com