


EN
What’s Behind Sabra Health Care REIT (SBRA) Stock’s Latest Move?
How the latest earnings, guidance and dividend shape the Sabra Health Care REIT story
Sabra Health Care REIT (SBRA) just paired its third quarter earnings release with refreshed full year earnings guidance and a confirmed quarterly dividend, giving investors a compact snapshot of current fundamentals.
The mix of updated profit expectations and a set dividend timeline matters because it links reported profitability to actual cash distributions, which is central for anyone looking at real estate investment trusts for income.
Recent trading has leaned in Sabra Health Care REIT’s favor, with the share price up 13.24% over the past month and 12.11% year to date to US$21.47. A 19.53% one year total shareholder return and very large 5 year total shareholder return suggest longer term holders have already seen substantial value creation as the latest earnings, guidance and dividend reset investor expectations around both growth prospects and income risk.
Capitalize on Sabra Health Care REIT’s fresh earnings, guidance and dividend signal by comparing it with a curated 6 dividend fortresses that balance income potential with fundamental strength.After that run, Sabra Health Care REIT now asks a harder question: Does the updated earnings range and steady dividend still leave enough upside to justify taking on the current risk?
Most Popular Narrative: 6% Undervalued
Sabra Health Care REIT’s fair value in the analyst consensus Narrative on Simply Wall St sits at $22.79 versus the latest close at $21.47. This frames the recent earnings and dividend update against a modest implied discount and a clear set of operational goals.
Continued shift of Sabra Health Care REIT’s investment pipeline toward managed senior housing, with over 95% of more than US$1b of active opportunities tied to SHOP assets and 21 assets added year over year, can keep raising private pay exposure and support future revenue and cash NOI growth.
See why 8 investors see Sabra Health Care REIT as 6% undervalued.
Result: Fair Value of $22.79 (UNDERVALUED)
Still, Sabra Health Care REIT carries real tension points, including operator transition risk in assets like Avamere and pressure from funding a SHOP heavy pipeline alongside loan loss reserves.
Find out about the key risks to this Sabra Health Care REIT narrative.
Another view on Sabra Health Care REIT’s valuation
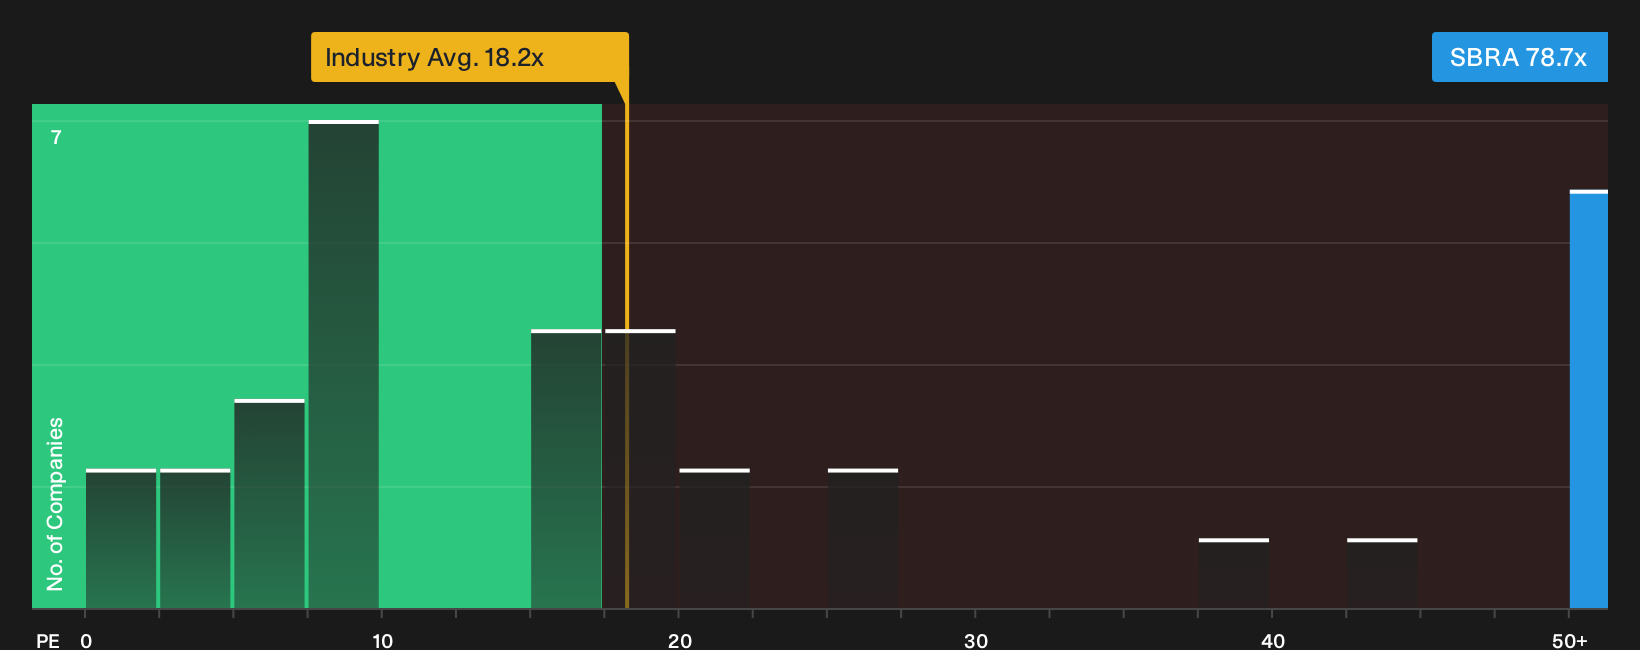
That 6% gap to the $22.79 fair value is only one angle. On earnings, Sabra Health Care REIT trades at a P/E of 78.7x, which is richer than both its 50.2x fair ratio and the 51.5x peer average and well above the 18.2x global Health Care REITs level. If sentiment cools or expectations ease, how quickly could that premium compress?
Before leaning too hard on any single yardstick, it helps to review what the numbers imply across different earnings scenarios over time. From there, investors can consider whether today’s multiple feels more like a cushion or a tightrope. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals in the Sabra Health Care REIT story, with both risk flags and clear positives in play, mean you are better off reviewing the details yourself now and deciding where you land. To weigh both sides without shortcuts, start with the headline 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Sabra Health Care REIT?
If Sabra Health Care REIT has your attention, do not stop here. Fresh opportunities often show up where fewer people are looking.
Use the Simply Wall St screener to pressure test your current thinking, explore new perspectives, and check whether you are overlooking potentially better risk and reward trade-offs.
- Target robust businesses that pair earnings power with balance sheet resilience by reviewing a curated list of solid balance sheet and fundamentals (25 results).
- Search for potential mispricings by scanning a focused 33 high quality undervalued stocks before capital moves elsewhere.
- Identify income ideas that still start with quality fundamentals by running your filters against a hand picked 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com