


EN
RXO (RXO) Could Be 6% Undervalued Following Third Quarter Profit Turn
RXO earnings spark fresh attention from investors
RXO (RXO) drew fresh attention after reporting third quarter results on October 29, 2026, with sales of US$1,871 million and net income of US$3 million, compared with a loss a year earlier.
RXO’s third quarter profit arrived after a powerful share price run, with the 90 day share price return of 29.98% and year to date share price return of 117.45%. The 1 year total shareholder return of 142.36% points to momentum that has been building rather than fading.
Scan other transportation plays showing similar earnings momentum with a curated list of 19 high quality undiscovered gems that combine solid fundamentals with relatively under-the-radar share price interest.
RXO trades only modestly below analyst targets after a sharp run, so the real question is whether that small discount reflects lingering caution or a mispriced recovery story.
Most popular RXO narrative: 6% undervalued
RXO last closed at $27.92, compared with a fair value estimate of $29.83 in the analyst consensus Narrative on Simply Wall St, which builds that view from analyst forecasts for revenue, earnings and margins.
RXO's relentless investment in AI-powered, proprietary digital freight-matching technology is rapidly boosting employee productivity (up 45% in two years) and driving operating leverage. As digital adoption accelerates in logistics, this is described as setting up sustainable margin and EBITDA growth, making the current valuation disconnect notable.
See why 4 investors see RXO as 6% undervalued.
The Narrative links that fair value to a discount rate of 8.39%, analyst forecasts for revenue of about $8.0b and projected earnings of $276.9m by 2029, along with an assumed P/E of 23x on those future earnings. It also highlights that RXO is currently loss making on a trailing basis, with reported net income of an $88m loss against revenue of $6.54b, so the valuation hinges on the business reaching and sustaining those forecast profit margins.
Analysts in the Narrative treat the current analyst target of $29.83 as only modestly above the latest share price, which they interpret as the stock being roughly in line with their modeled value. The 6.4% discount to that fair value leaves some room for investors who agree with the revenue and earnings path described, without implying a large gap between price and those fundamentals.
Result: Fair Value of $29.83 (UNDERVALUED)
Still, RXO’s heavy exposure to the automotive sector, along with ongoing softness in freight demand, could undermine the earnings path that current analyst narratives assume.
Find out about the key risks to this RXO narrative.
Another view on RXO’s value
The analyst Narrative paints RXO as about 6% undervalued versus a $29.83 fair value, yet the SWS DCF model points the other way. On that cash flow view, RXO at $27.92 trades above an estimated future cash flow value of $20.08, which implies an overvalued signal instead.
Two models, two stories. The key question for you is which set of assumptions on future profitability feels more realistic for RXO, and what that says about your required margin of safety.
Look into how the SWS DCF model arrives at its fair value.
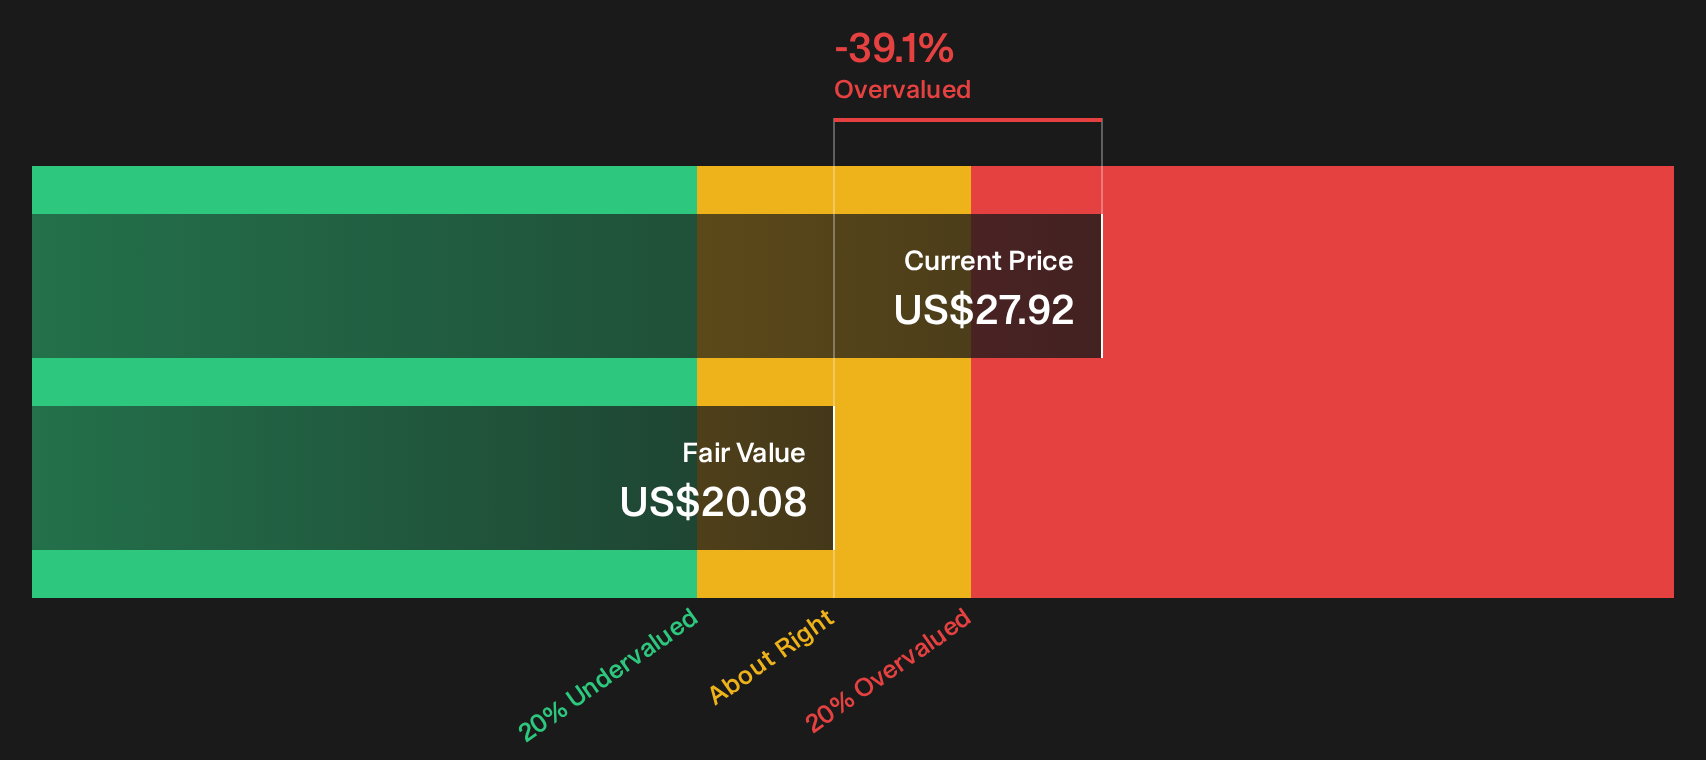
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out RXO for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on RXO so far, or a clear story hiding in plain sight? Act while the data is fresh and examine the bullish and bearish angles yourself with 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond RXO?
If RXO has sharpened your focus, do not stop there. Broader idea hunting across sectors can help you stress test your thinking and refine your watchlist.
- Target steady compounding potential by reviewing 33 high quality undervalued stocks that pair solid fundamentals with prices that sit below many investors’ radars.
- Prioritise staying power over thrills by scanning 30 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- Strengthen the core of your portfolio by checking the list of solid balance sheet and fundamentals (25 results) before the next wave of buyers starts paying attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com