


EN
How Investors May Respond To D.R. Horton (DHI) Dividend Hike And 2027 Guidance
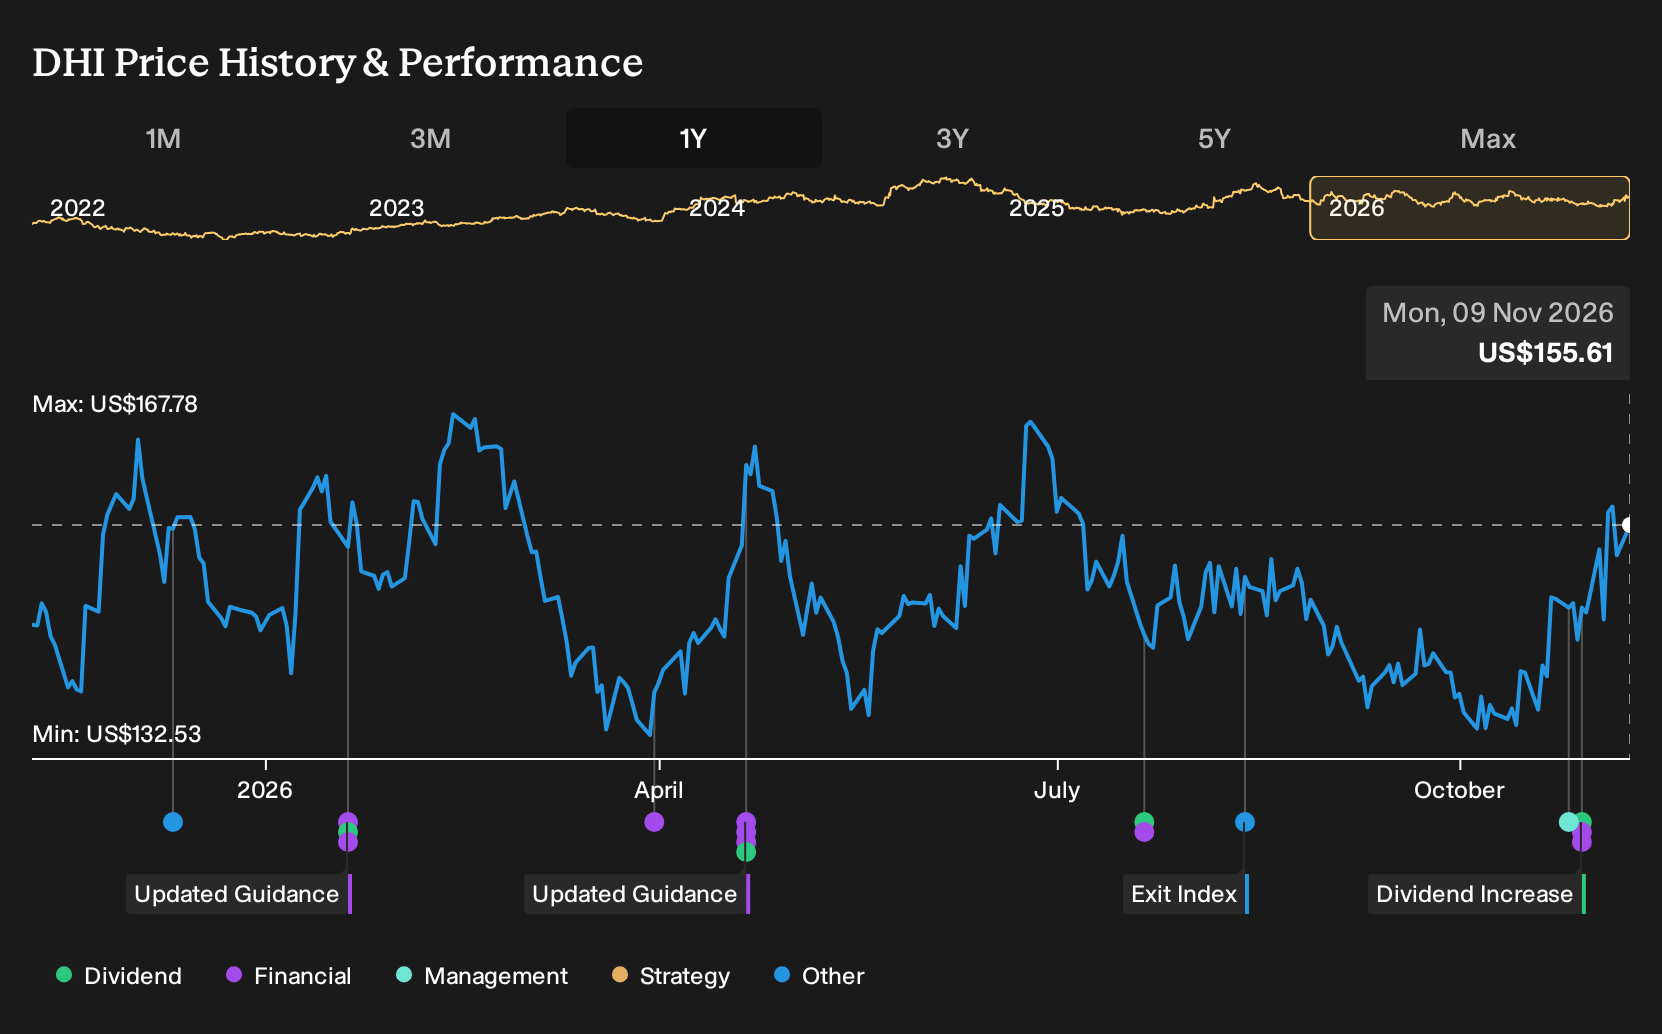
- D.R. Horton reported quarterly and full year results for the period ended September 30, 2026, issued fiscal 2027 consolidated revenue guidance of US$30b to US$32b, and raised its quarterly dividend to US$0.50 per share, payable on November 19, 2026 to holders on November 12.
- The combination of slightly lower recent sales and earnings, new multibillion-dollar revenue guidance, and an 11% dividend lift gives investors a clearer picture of how D.R. Horton is balancing current profitability, future scale, and ongoing cash returns.
- The focus now turns to how D.R. Horton’s investment narrative around affordability and capital-efficient growth aligns with this higher dividend commitment.
Scan how D.R. Horton’s guidance and higher payout compare with other potential income opportunities by reviewing our curated list of 6 dividend fortresses.
D.R. Horton Investment Narrative Recap
Owning D.R. Horton means believing its focus on affordability, capital light land use and build efficiency can offset pressure from incentives, land inflation and legal costs. Quarterly and full year results showed softer sales and earnings, so the near term story hinges on how effectively management protects homebuilding margins while keeping volumes attractive for buyers.
The analyst consensus narrative on Simply Wall St highlights affordability and cycle time gains as key supports for earnings, which still matters after this update. The new fiscal 2027 revenue outlook and recent trends do not radically change the near term catalyst, execution on incentives and cost control, or the main risk, sustained margin pressure.
The 11% dividend increase to US$0.50 per share is the clearest new signal to focus on. It ties directly into whether D.R. Horton can keep generating enough cash from its lot light model, Forestar partnerships and rental activity to fund higher payouts while still investing in land control and construction efficiency.
A higher dividend raises the bar for capital allocation. If incentives around 10% of home revenue persist or lot costs keep rising, that payout competes with legal expenses, technology investment such as the Scaffold software, and any flexibility to respond to weaker demand. As a result, execution on margins and cash generation becomes even more important to monitor.
D.R. Horton's current analyst narrative points to forecast revenue of US$43.9b and earnings of US$3.4b by 2029, based on an assumed 9.9% yearly increase in revenue and an earnings uplift of about US$0.5b from US$2.9b today.
Uncover why D.R. Horton's fair value indicates a 4% potential downside to its current price, suggesting a premium that may not hold.
Exploring Other Perspectives
One alternate angle on D.R. Horton leans heavily on cash returns as the main catalyst. The most optimistic analysts were penciling in about US$44.0b of revenue and US$4.8b of earnings by 2029, assuming rising margins and sizeable buybacks. You may see those projections differently once this guidance and dividend move are reflected in updated views.
Explore 3 other D.R. Horton fair value estimates, including one that suggests it could be worth as much as $150.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your D.R. Horton research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for D.R. Horton. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate D.R. Horton's overall financial health at a glance.
Looking For More Investment Ideas Beyond D.R. Horton?
If this update on D.R. Horton has sharpened your view on income, value and risk, it can help to line that thinking up against a broader set of stocks using the Simply Wall St Screener.
- For investors who want income without ignoring quality, review a focused set of companies that currently look like potential 6 dividend fortresses.
- If capital preservation is front of mind, scan a basket of companies that currently screen as 30 resilient stocks with low risk scores.
- When you are hunting for fresh ideas backed by fundamentals rather than headlines, filter for 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com