


EN
ExlService Holdings (EXLS) Could Be 56% Below Fair Value On OpenAI Deal And Higher Guidance
What the OpenAI partnership and fresh guidance mean for ExlService Holdings
ExlService Holdings (EXLS) is moving into the spotlight after being named an OpenAI Select Partner and pairing that announcement with fresh third quarter results and higher full year 2026 revenue guidance.
This combination links ExlService Holdings directly to one of the highest profile AI platforms while also giving investors new earnings per share data and an updated revenue range to assess the stock.
Recent trading has started to reflect this, with ExlService Holdings posting a 17.78% 1 month share price return and a 24.15% 3 month share price return. Longer term momentum remains in place through a 61.86% 3 year total shareholder return and a 58.94% 5 year total shareholder return.
Scan beyond ExlService Holdings and see how other AI driven operators with momentum and scale stack up using our curated list of 42 profitable AI stocks that aren't just burning cash.
ExlService Holdings now has stronger AI credentials and updated 2026 guidance on the table. After this sharp share price move, is that business strength already fully reflected in what you are paying per share?
Most Popular Narrative: 135% Overvalued
Set against ExlService Holdings' last close at $43.33, the most followed narrative argues for a fair value of $18.40 per share using a 6.35% discount rate.
Offshore analytics and managed-operations provider that runs mission-critical claims, underwriting, payment-integrity and finance workflows for large insurers, healthcare payers and banks, and is repositioning that base into data and AI-led delivery. Roughly 53% of revenue is recurring, embedded operations protected by 12 to 30 months of transition friction, which is enough to make permanent capital loss unlikely at a low entry price. It is not enough to underwrite compounding: five years of mix shift into AI-led work has produced no gross margin expansion, contracts are terminable without cause, and the AI work is re-won through pilots rather than inherited. The thesis is therefore a price thesis, not a quality thesis
See why 3 investors see ExlService Holdings as 135% overvalued.
Result: Fair Value of $18.40 (OVERVALUED)
Still, two pressure points could upend this bearish view: how ExlService Holdings converts its OpenAI work into pricing power and the resilience of its long contracts.
Find out about the key risks to this ExlService Holdings narrative.
Another View: Cash Flows Point to Undervaluation
The narrative calling ExlService Holdings 135% overvalued on an $18.40 fair value runs into a very different conclusion from our DCF model. On that framework, EXLS at $43.33 trades about 56.4% below an estimate of future cash flow value of $99.38, which frames the stock as undervalued instead.
Two models, two opposing signals. As an investor, which set of assumptions about ExlService Holdings' earnings durability and reinvestment do you find more convincing?
Look into how the SWS DCF model arrives at its fair value.
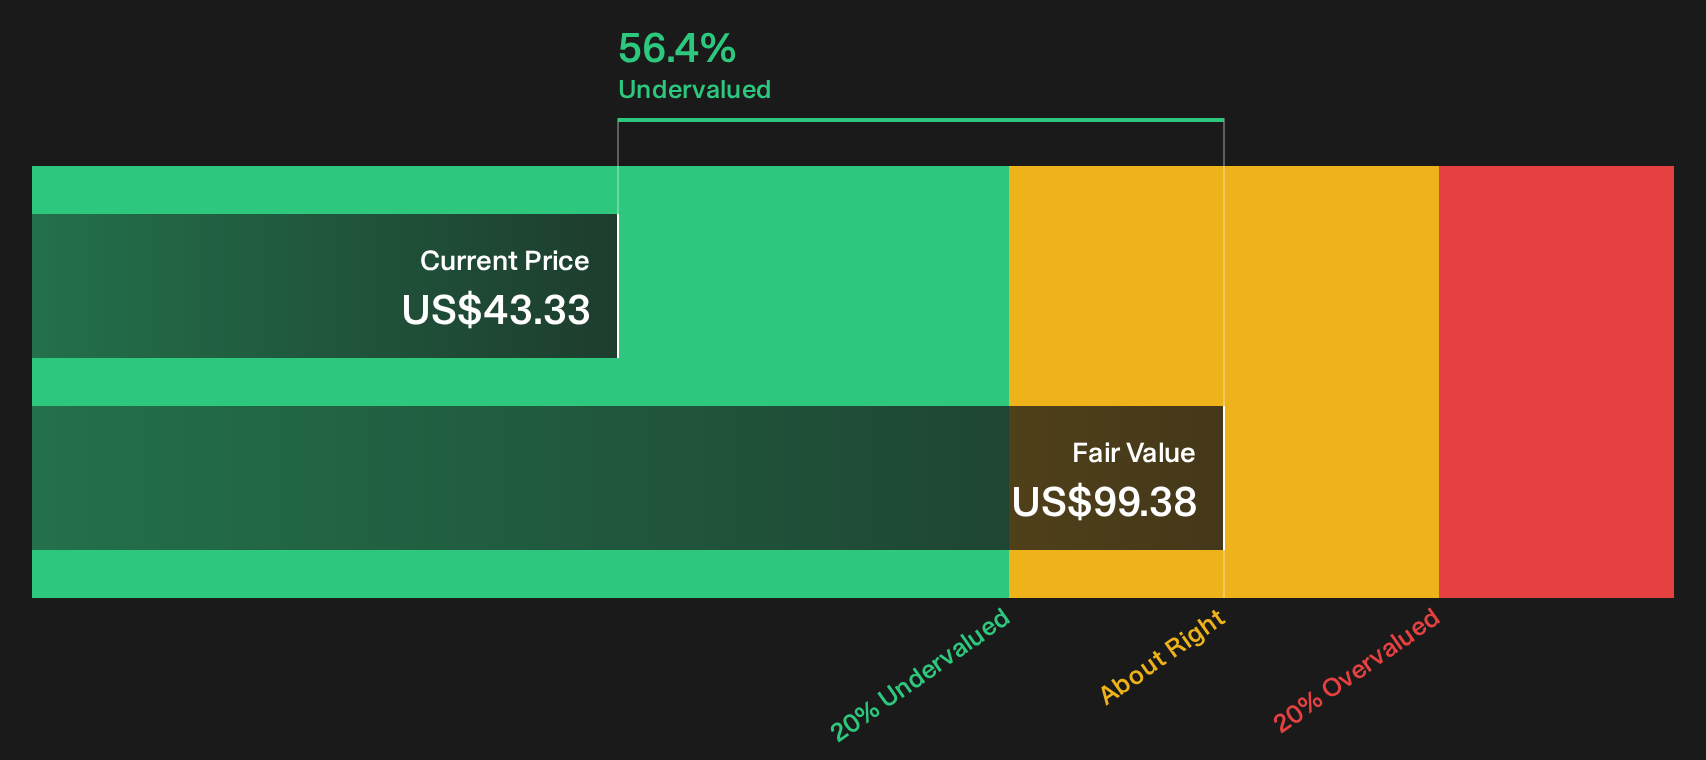
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ExlService Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on ExlService Holdings so far, or a clear signal waiting in the numbers you care about most. Act while the OpenAI story and fresh guidance are front of mind, and pressure test the upside by reviewing the 3 key rewards
Looking for more investment ideas beyond ExlService Holdings?
Do not stop with ExlService Holdings. Use fresh screeners to spot other opportunities quickly, compare quality, and pressure test where you want your next dollar working.
- Target reliable income streams by reviewing companies that qualify as 6 dividend fortresses.
- Hunt for mispriced opportunities by checking the 33 high quality undervalued stocks that align with your return and risk expectations.
- Prioritise capital protection first and sift through 30 resilient stocks with low risk scores that aim to keep volatility in check while you stay invested.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com