


EN
LCI Industries (LCII) Stock Looks About Right After Its 29% Jump
LCI Industries has rallied over the past month, even as the share price is still down over the year, which naturally raises a question for anyone looking at the stock today. Is the current valuation supported by what the business is earning right now, or is recent enthusiasm running ahead of its profit profile?
- The share price has gained about 29.1% over the past month, which puts fresh attention on whether that move is in line with the earnings that underpin LCI Industries.
- The planned all stock merger with Patrick Industries, along with the board's decision to reaffirm that deal after a cash proposal at US$101 per share, can reshape expectations for future profitability and the way investors weigh its earnings against the Fair Ratio benchmark.
- The analysts covering LCI Industries have run their own numbers. See what analysts think LCI Industries's shares could be worth.
The issue now is whether LCI Industries' current share price is justified by its earnings when set against this recent run and the evolving deal story.
If you want to test the same earnings question that hangs over LCI Industries against a wider set of stocks, run the numbers across 33 high quality undervalued stocks
.Is LCI Industries Fairly Priced on Earnings?
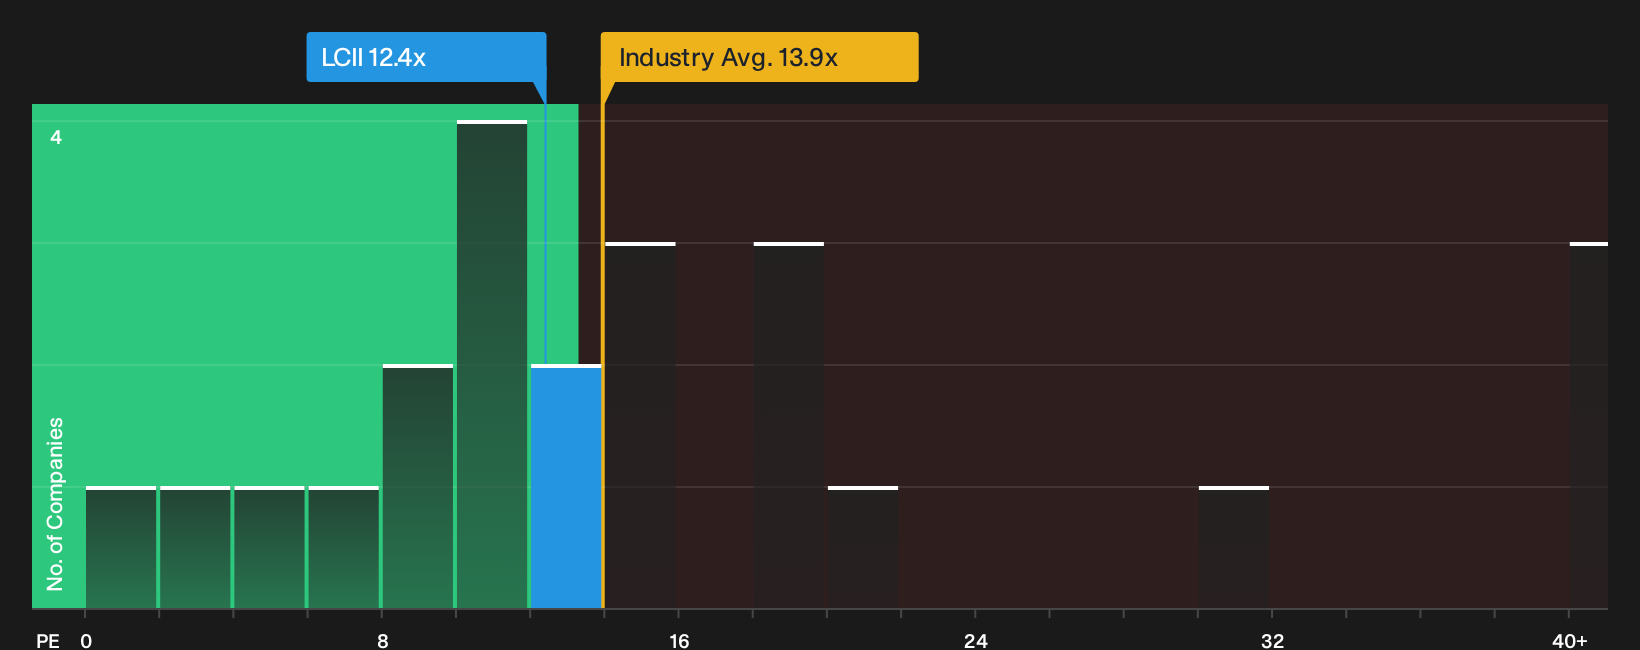
The P/E ratio works well for LCI Industries because the market is clearly focused on earnings as the merger story with Patrick Industries unfolds. On this measure, LCI trades at about 12.4x earnings, which is slightly below the Auto Components industry average of 15.4x and close to the peer group on roughly 12.8x.
Because the board reaffirmed the all stock merger despite a US$101 per share cash proposal, the key question is how much of that deal outlook is already reflected in this P/E level. The current multiple sits near the Fair Ratio, which is the earnings multiple you would typically expect given LCI Industries' size, margins, sector and risk profile. On this framework, the pricing on earnings does not screen as stretched or unusually cheap. Relative to both the sector and peers, the numbers suggest investors are paying a going rate for each dollar of profit, and you would need to weigh your view on the merger and earnings resilience to decide if that feels attractive. Explore the numbers behind LCI Industries's P/E valuation.
The LCI Industries Narrative: What Would Justify Today's Price?
Narratives pick up where this valuation puzzle leaves off for LCI Industries, explaining which potential paths for revenue, margins and earnings would need to occur for the stock to be worth significantly more or less than it is today. They also set out the assumptions behind each fair value view in a way you can track against future results. These scenarios are available on Simply Wall St's Community page and give you a structured way to compare your expectations with the market's implied outlook.
LCI Industries splits opinion, with one camp seeing meaningful upside while the other leans toward caution on RV exposure and the Patrick merger.
Bull case: 12% undervalued
The analyst consensus Narrative on Simply Wall St highlights what could go right if diversification and self help actions keep working.
"The current valuation implies the share price already reflects ongoing RV cyclicality risks but underappreciates the earnings power the company could reach if diversification, aftermarket growth, and self help margin gains are sustained…"
Discover why this Narrative puts LCI Industries at 12% undervalued.
Bear case: 26% overvalued
The bearish analyst Narrative on Simply Wall St focuses on RV cycle risk and questions how much the Patrick deal can really add.
"Bearish analysts expect LCI Industries to see its core North American RV OEM business pressured as wholesale shipments remain below earlier 2026 expectations and as the mix shifts toward lower content single axle trailers…"
Explore why this Narrative puts LCI Industries at 26% overvalued.
One big missing piece for LCI Industries
Valuation only tells you what the market is paying today. The next question is how analysts currently see LCI Industries a few years down the road and how that lines up with this price. Explore where analysts expect LCI Industries to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com