


EN
Regal Rexnord (RRX) Could Be 22% Undervalued On Lowered Earnings Guidance
What Regal Rexnord’s Latest Earnings Signal For Investors
Regal Rexnord (RRX) just posted third quarter results that combined higher sales with a swing to a net loss, driven in part by a sizeable goodwill impairment charge.
Management also cut and tightened full year 2026 GAAP earnings guidance, a move that tends to reset expectations and can quickly reshape how investors weigh recent share price strength.
The goodwill hit and lower 2026 earnings guidance did not prevent Regal Rexnord’s share price from rallying, with a 1-day share price return of 6.93% and a year-to-date share price gain of 23.74%. The 1-year total shareholder return of 35.86% points to momentum that has extended beyond this quarter’s reaction.
Scan how Regal Rexnord compares to other industrial plays reacting to earnings resets by checking our curated list of 30 resilient stocks with low risk scores.
Regal Rexnord just rallied hard in the face of a goodwill hit and lower 2026 earnings guidance. Is that surge a starting gun for more upside, or a signal that most of the move is already spent?
Most Popular Narrative: 21.8% Undervalued
On the analyst consensus Narrative on Simply Wall St, Regal Rexnord’s fair value of $231.10 sits well above the last close at $180.78. This frames the latest earnings wobble against a model that leans on cash flow rather than short term headlines.
Accelerating project wins and order strength in Regal Rexnord's Automation & Motion Control and Industrial Powertrain Solutions segments, including double digit order growth and higher shippable backlog into 2027, are set to convert existing longer cycle and blanket orders into future revenue and support operating leverage.
See why 17 investors see Regal Rexnord as 22% undervalued.
Result: Fair Value of $231.10 (UNDERVALUED)
Still, rare earth magnet supply bottlenecks and persistent tariff or cost pressures could easily slow Regal Rexnord’s margin ambition and weaken the current undervalued thesis.
Find out about the key risks to this Regal Rexnord narrative.
Another View: Regal Rexnord Looks Expensive On Earnings
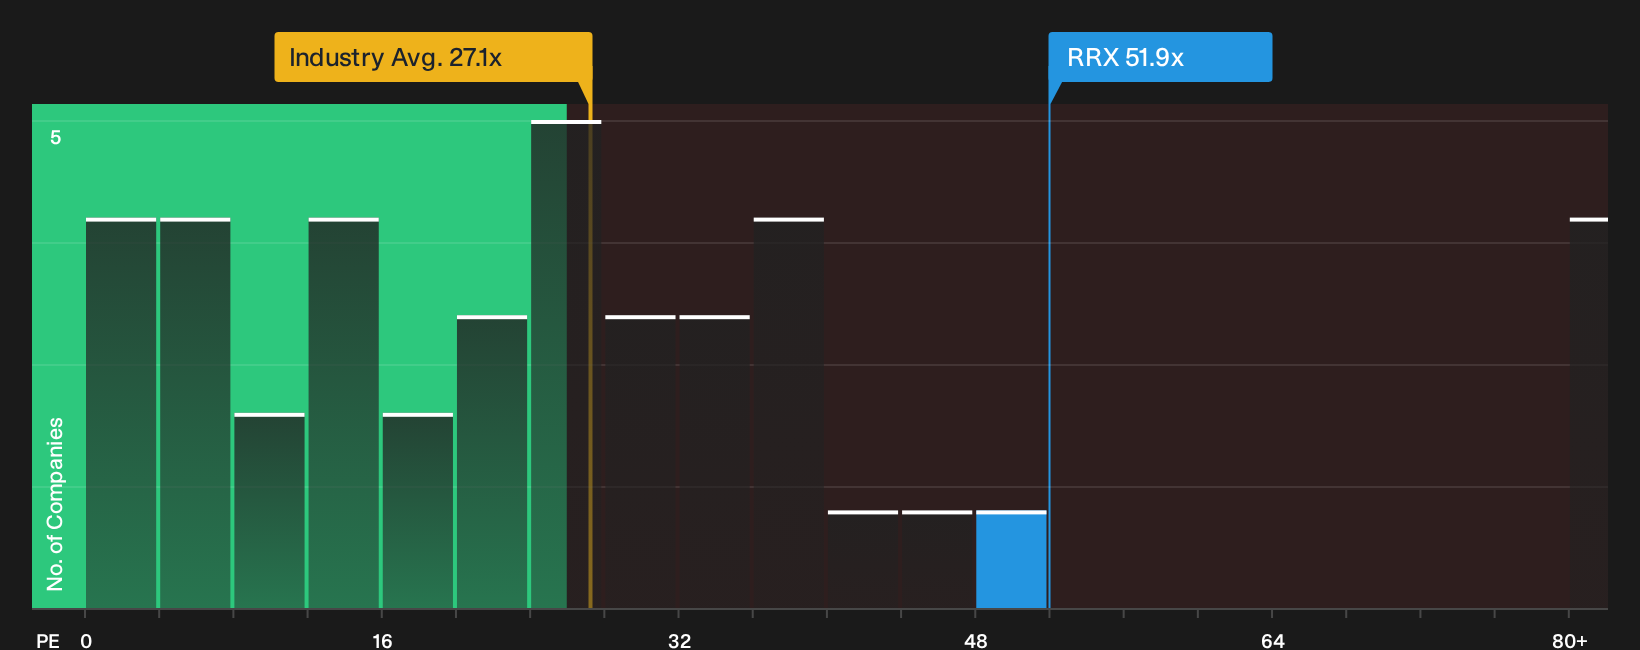
The earlier fair value work leans on future cash flows. On a simple P/E check, Regal Rexnord trades at 51.9x, which is much richer than both the US Electrical industry at 27.1x and peers at 28.4x, and also above its 36.3x fair ratio. Is the market overpaying for the growth story, or is the DCF lens seeing something this snapshot misses?
See what the numbers say about this price gap in our valuation breakdown by reviewing See what the numbers say about this price — find out in our valuation breakdown.
Then compare that earnings based view to how the stock stacks up visually versus its sector using
Next Steps
If this mix of optimism and caution around Regal Rexnord feels familiar, treat it as a prompt to move quickly and test the thesis against your own framework using 3 key rewards and 2 important warning signs.
Looking for more Regal Rexnord style investment ideas?
If Regal Rexnord has sharpened your sense for opportunity and risk, do not stop there. Broaden your watchlist with targeted ideas built from transparent data.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (25 results) that keep financial risk in check.
- Hunt for quality at a sensible price through the 33 high quality undervalued stocks that filters for fundamentals that still leave room for upside.
- Strengthen your income stream by reviewing the 6 dividend fortresses that focus on higher yielding payouts backed by underlying business strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com