


EN
Should Strong Q3 Earnings Require Action From Delek US Holdings (DK) Investors?
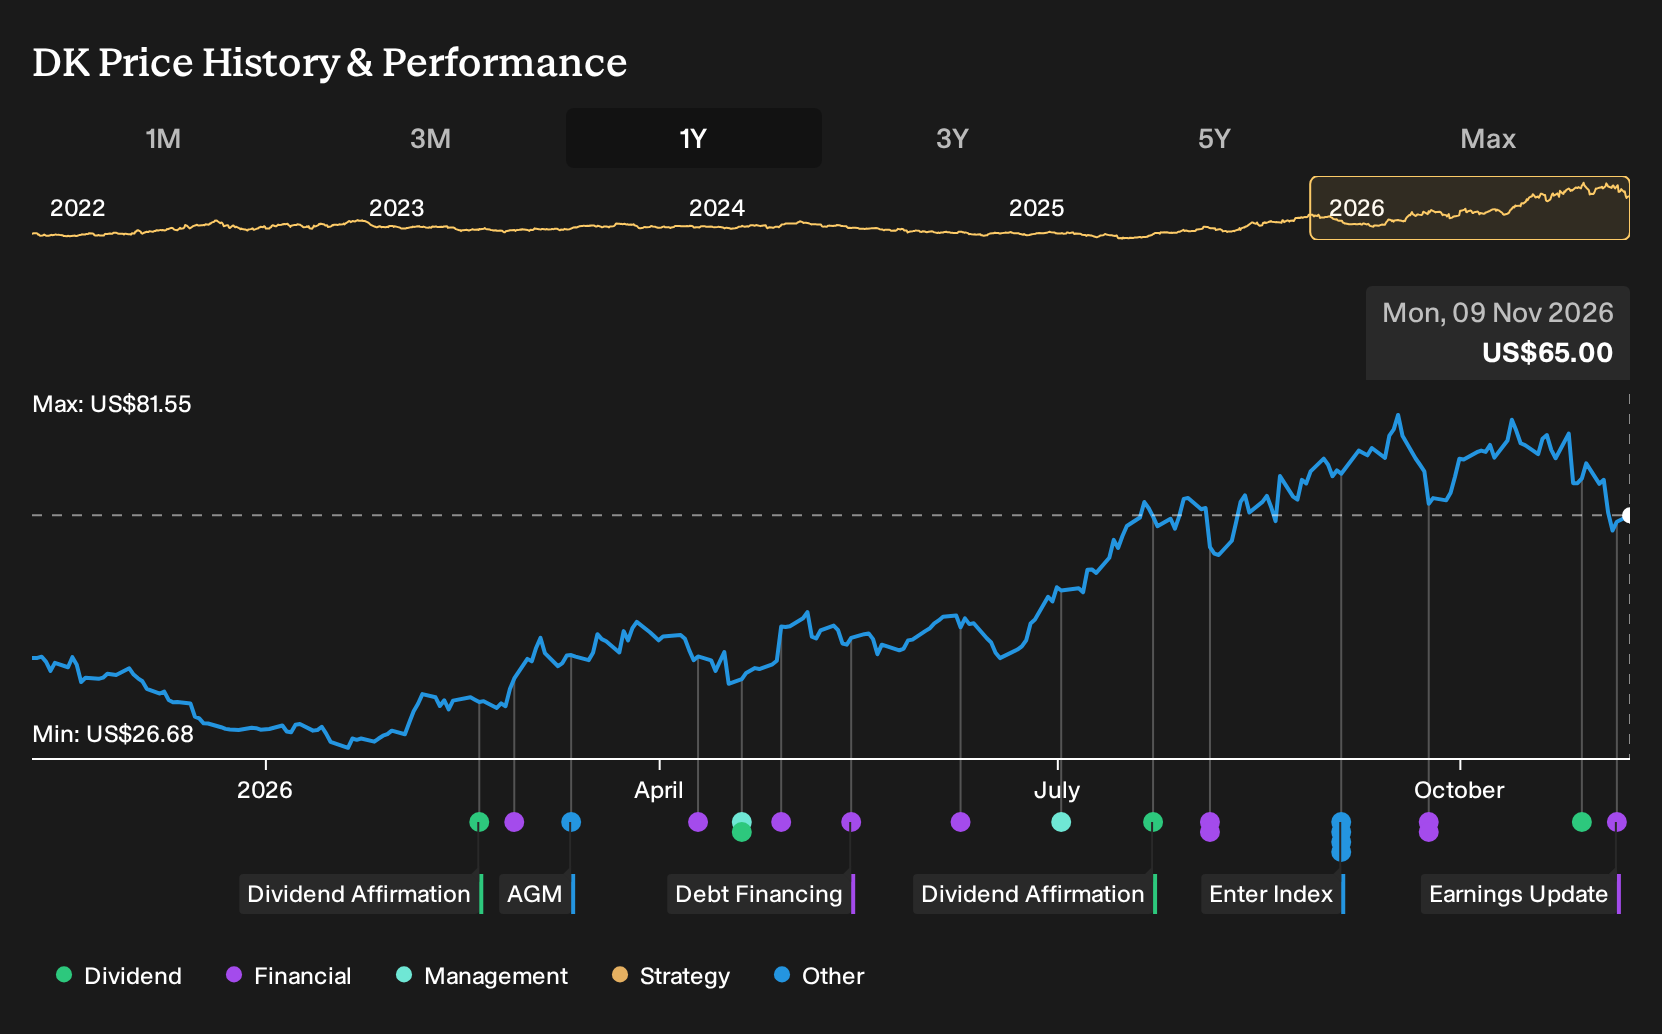
- Delek US Holdings reported Q3 2026 sales of US$4,392.1 million and net income of US$1,133.8 million, with basic earnings per share from continuing operations of US$18.55. The company also approved a higher quarterly dividend of US$0.30 per share for payment in November 2026.
- The swing from a nine month net loss in the prior year to net income of US$1,102 million in 2026, together with management’s focus on refinery optimization, debt reduction and share repurchases, points to a business model leaning heavily into cash generation and capital returns.
- We will now look at how Delek US Holdings' stronger Q3 profitability and raised optimization target could reshape the existing investment narrative.
Compare Delek US Holdings' earnings-driven run with a curated group of cash-generative refiners and energy plays in the 33 high quality undervalued stocks that may not fully reflect their fundamentals yet.
Delek US Holdings Investment Narrative Recap
To own Delek US Holdings, you need to believe the refining and logistics platform can keep turning strong quarters like Q3 2026 into resilient cash generation as conditions shift. The analyst consensus narrative on Simply Wall St leans on the Enterprise Optimization Plan, high distillate yields and Delek Logistics to support this. The most important short term catalyst remains continued refinery reliability and optimization delivery, with recent results reinforcing that thesis rather than changing it.
The biggest near term risk still sits in regulatory and demand pressure on traditional fuels. Small refinery exemptions and fuel standards matter because they shape compliance costs and future margins. Strong 2026 earnings and cash focus do not remove exposure to potential policy shifts or a long term decline in gasoline and diesel demand.
The most relevant recent move is the roughly 18% dividend increase to US$0.30 per share that Delek US Holdings plans to pay in November 2026. That decision leans on current profitability and the visibility from optimization benefits and expected cash inflows such as the small refinery exemption proceeds. It also ties into management’s comments about using stronger cash generation for shareholder returns.
For you as an investor, the higher dividend sits alongside debt reduction and share repurchases as proof that capital is being actively returned today. It also raises the bar for sustaining payouts if refining conditions or regulatory support soften. The announcement therefore connects directly to the key catalyst of consistent cash flow execution and to the risk that future earnings may not match this year’s level.
Analysts expect Delek US Holdings to generate about US$11.0b of revenue and US$107.7m of earnings by 2029, based on a forecast yearly revenue decline of 6.9% and an earnings decrease of roughly US$1.1b from current earnings of about US$1.2b.
Discover why Delek US Holdings' fair value suggests a 32% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One of the sharpest contrasts comes from how the most bearish analysts treat Renewable Fuel Standard costs at Delek US Holdings. Before this Q3 surge, they were working off revenue of about US$10.2b by 2029 and earnings near US$122.8m. That is a much harsher story. It shows how far opinions can stretch. Use this earnings surprise as a prompt to revisit those assumptions and test several viewpoints for yourself.
Explore 3 other Delek US Holdings fair value estimates, including one that suggests it could be worth just $85.29!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A useful starting point for your Delek US Holdings research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Delek US Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to review Delek US Holdings' overall financial position at a glance.
Looking For More Investment Ideas Beyond Delek US Holdings?
If Delek US Holdings has you thinking harder about cash generation, balance sheets, and income potential, use that momentum to scan a wider opportunity set with the Simply Wall St Screener before making your next move.
- If you care most about valuation and fundamentals lining up, check out a curated set of 33 high quality undervalued stocks that combine quality metrics with pricing that may still be catching up.
- If capital strength and resilience matter to you, start with a list of solid balance sheet and fundamentals (25 results) that can help you focus on businesses with room to handle shocks.
- If income is a priority, use the 6 dividend fortresses to zero in on companies offering higher yields with the potential to support regular payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com