


EN
What Applied Materials Buyers Were Betting On
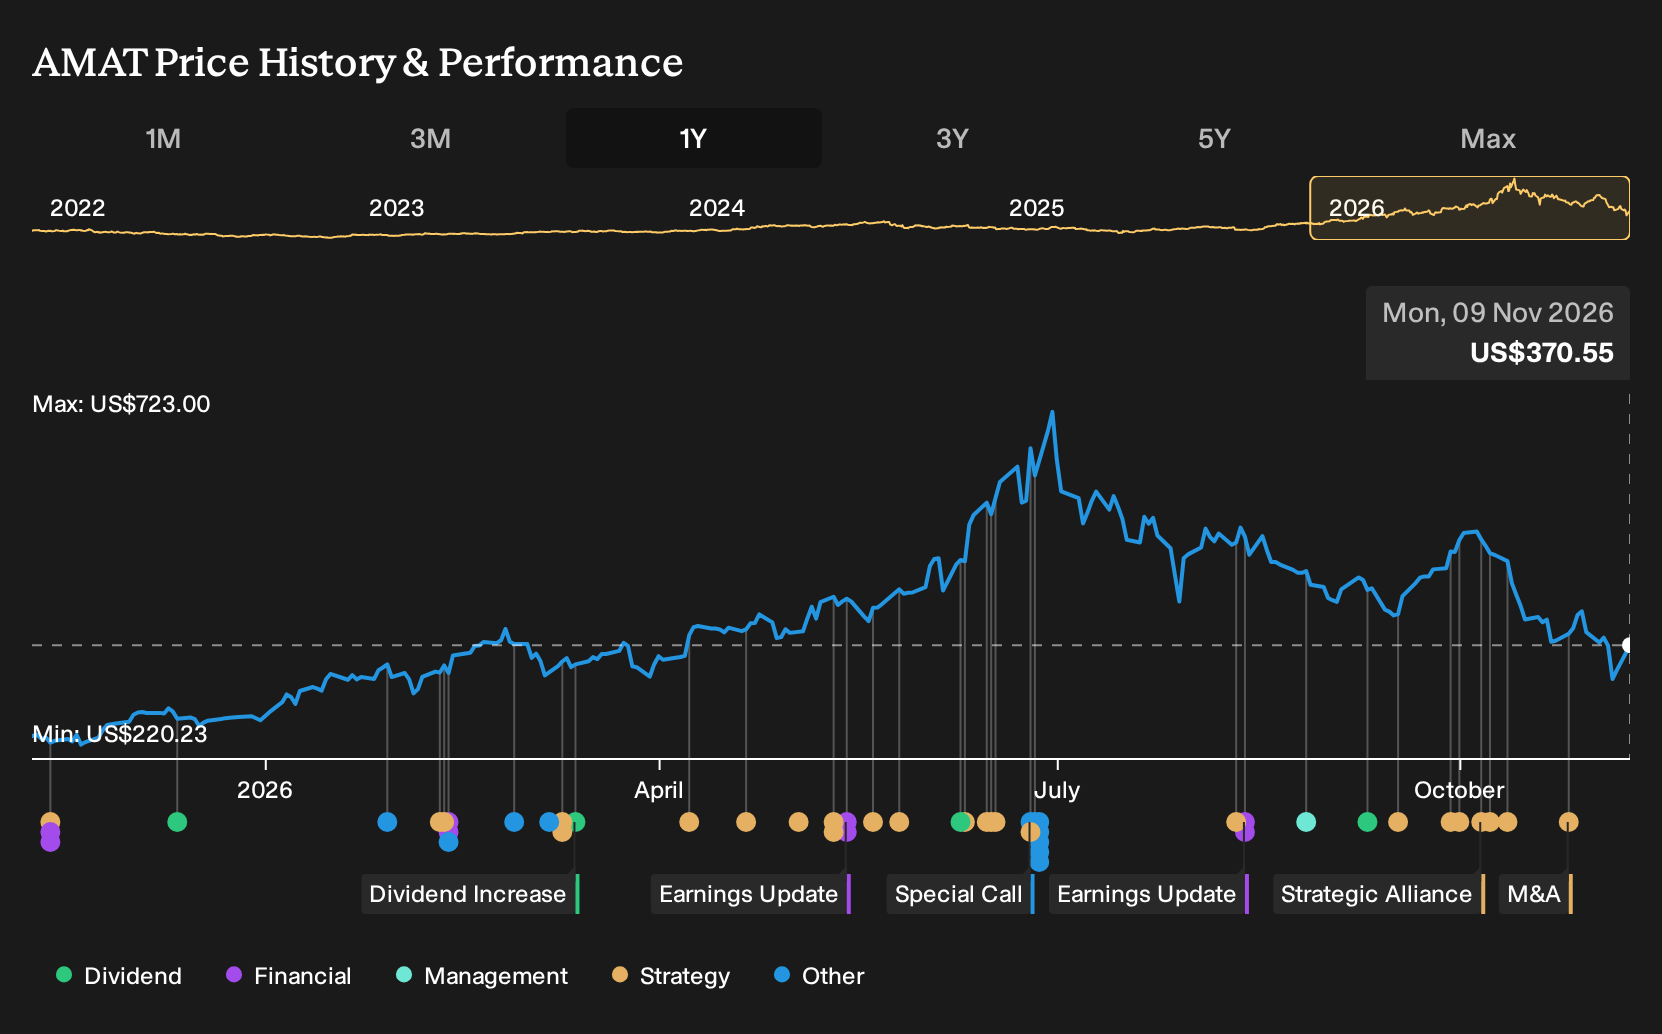
If Applied Materials sat on a watchlist instead of in your portfolio, the payoff may feel like it slipped through your fingers. Holding Applied Materials over the past year would have returned 58.5%, including dividends. That kind of move raises a sharp question. Before record AI headlines and big-ticket fab announcements started crowding the news, what early conviction in AI and IoT driven equipment demand, on record by late 2025, could have helped you treat this as a long-term capacity build story rather than just another cyclical chip-tools trade?
The move put Applied Materials in the middle of this trade. Scan 53 AI infrastructure stocks for other companies exposed to it.
The Two Applied Materials Stories Investors Were Arguing About
The shares cost US$230 at the start of the period, and anyone looking at Applied Materials then had to decide which of two very different stories felt more realistic.
On the optimistic side, the bullish case pointed to a Fair Value of US$250, a suggested destination price if its thesis played out, built on AI and IoT lifting demand for complex tools and a 7.8% annual revenue growth assumption.
The more cautious October 2025 view set Fair Value at US$195, again a model driven output, and flagged China export restrictions plus customer concentration as key risks despite a 4.3% revenue growth assumption.
What The Applied Materials Evidence Did To The Argument
Applied Materials delivered Q3 2026 revenue of US$9.12b and net income of US$2.54b, with net margin at 27.8% versus 24.4% a year earlier. That combination of higher sales, higher profit and a wider margin leaned toward the optimistic case that AI and advanced packaging could support stronger earnings power than cautious 2025 assumptions implied.
The key lesson is simple. When a story hinges on rising profitability, track the trio of revenue, absolute earnings and net margin in each report, and then compare them to the original thesis rather than to the latest share-price move.
What Applied Materials' Run Up 58% Already Assumes
Applied Materials trades at US$371 today after a 58.5% gain over the past year. The bullish analyst Narrative on Simply Wall St sees Fair Value above that level, tied to a view that current AI and advanced packaging demand still leaves room in the price.
The Narrative leans on Applied Materials extending its equipment and services position as customers build AI focused capacity. The key question for anyone paying today is whether record Semiconductor Systems and services momentum can keep converting into orders strong enough to support that higher figure.
"Bullish analysts expect Applied Materials to compound AI-driven demand in leading-edge wafer fab equipment and advanced packaging with growth in higher-value services, creating a business mix that they see as underappreciated by the market. The main thing that has to go right is that Applied Materials converts its record Semiconductor Systems and services momentum, including advanced packaging and Applied Global Services, into durable orders that justify the ongoing capacity build-out through 2028 and beyond."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Find Your Own Contrarian Opportunity
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 41% below our estimate - builds a broader base of low cost deposits and AI supported small business services.
- Company 2 - 40% below our estimate - handles local pay in and pay out flows for large merchants entering new channels.
- Company 3 - 21% below our estimate - shifts its mix toward higher margin stormwater products and wastewater management solutions.
Those are three of them. See the full list of 33 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com