


EN
Why NewPrinces Stock Looks Cheap On Earnings Compared With Peers
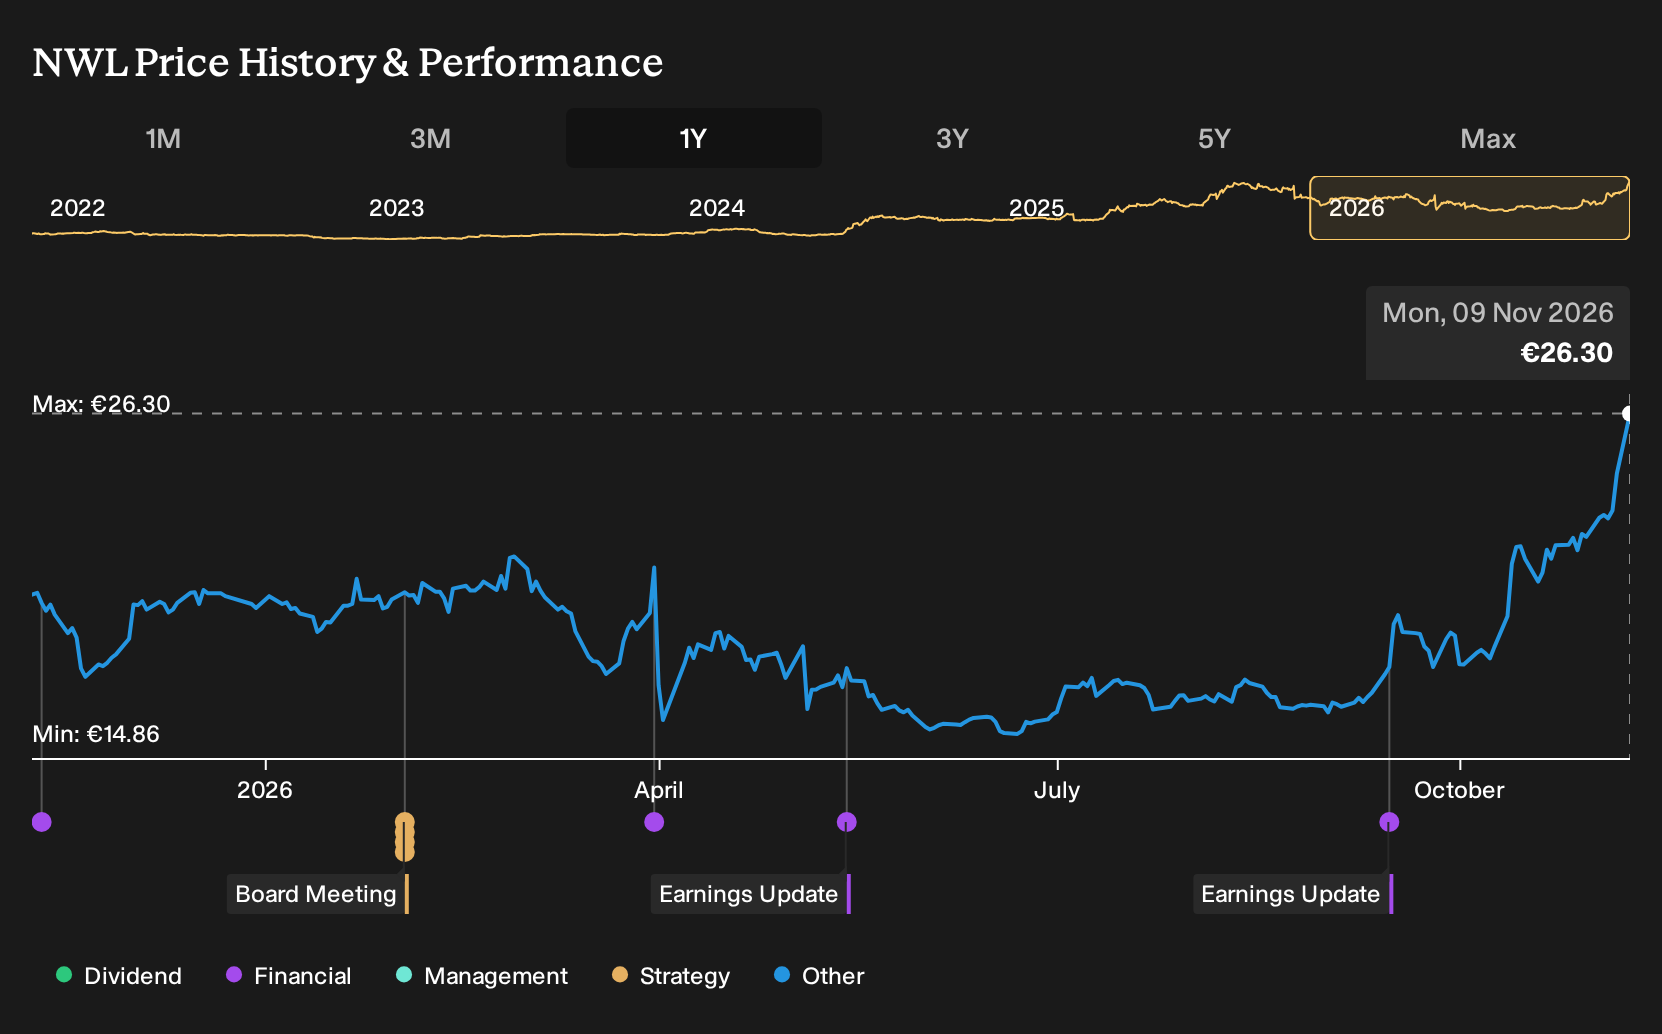
- Recent commentary on NewPrinces highlights that the group’s current earnings result in a P/E ratio that sits well below the wider industry, with at least one valuation model suggesting the stock price implies a cautious view of the business.
- The wide gap between NewPrinces’ earnings valuation and sector averages raises questions about whether investors are fully recognising the scale and integration potential of its multi-country food manufacturing platform.
- We will now look at how NewPrinces' consolidation-driven investment narrative could be affected by fresh focus on its comparatively low P/E.
Scan other undervalued ideas with similar earnings disconnects by checking our curated list of 209 high quality undervalued stocks alongside NewPrinces' valuation story.
NewPrinces Investment Narrative Recap
Owning NewPrinces means buying into a consolidation story in everyday food categories, as European_Hidden_Gem_Stocks, an investor in the Simply Wall St Community, puts it. The group has stitched together more than 30 plants across Europe, with recent deals like Princes, Carrefour Italia and Plasmon creating a large manufacturing platform. In the short term, the key issue remains execution on integration and efficiency rather than headline growth.
The recent focus on NewPrinces’ low P/E, despite a strong share price run, does not change that core thesis. It instead concentrates attention on whether current earnings, helped by large one off items, can transition into cleaner, repeatable profit as those acquisitions bed down.
The most relevant recent datapoint around this story is the gap between NewPrinces’ current P/E of 3.2x and the European food industry average of 14.3x, along with the estimate that the shares trade about 65.5% below a modelled future cash flow value of €76.23. That disconnect is feeding the current conversation about whether the rerating has run ahead of fundamentals.
At the same time, revenue is forecast to grow 6.2% a year while earnings are projected to decline about 19.9% annually over the next three years. This puts the quality of past 98.1% earnings growth under the microscope. For potential catalysts, the focus is likely on how management converts recent gross margin progress and one off boosted figures into steadier profitability without stretching a balance sheet that relies fully on higher risk borrowing.
In European_Hidden_Gem_Stocks’ view, NewPrinces reaches a fair value of €123.11 if revenue compounds at about 8.0% a year and the group settles into a 7.3% profit margin as the multi-country manufacturing platform matures and integration work flows through its income statement.
Uncover why NewPrinces' fair value indicates a 368% potential upside to its current price. This may represent a discount that could narrow quickly as sentiment shifts.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community stretch from €26.50 to €123.11 for NewPrinces, so private investors clearly disagree on what the shares are worth. Because these figures pre date the recent P/E spotlight, treat them as a starting point and explore several alternative viewpoints before forming your own stance.
Explore 2 other NewPrinces fair value estimates, including one that suggests potential upside of up to 368% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NewPrinces research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for NewPrinces. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NewPrinces' overall financial health at a glance.
Looking For More Investment Ideas Beyond NewPrinces?
If you want to stress test your thesis on NewPrinces, it helps to line it up against other opportunities that share similar traits or offer a very different risk profile. The Simply Wall St Screener can surface a wide range of listed businesses that match your preferences on valuation, balance sheet strength, income focus and more.
- If you are hunting for companies that combine quality fundamentals with what looks like a discounted valuation, scan through our hand picked 209 high quality undervalued stocks that might sit alongside NewPrinces in a value focused watchlist.
- For readers who care most about income resilience, filter for payout opportunities using a curated set of 222 dividend fortresses that emphasise both yield and staying power.
- When capital preservation is front of mind, narrow your search to a 202 resilient stocks with low risk scores so you can compare NewPrinces with businesses that score well on financial strength and volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com