


EN
How Positive Renal Denervation Data Will Impact Medtronic Stock (MDT)
- Medtronic reported past six month results from its SPYRAL AFFIRM post approval study, showing statistically significant blood pressure reductions with the Symplicity Spyral renal denervation system across diverse US patient groups and no increase in antihypertensive medications.
- The FDA has already cleared a labeling update for the Symplicity Spyral Multi Electrode Renal Denervation Catheter, adding data in isolated systolic hypertension, chronic kidney disease up to stage 3b, and type 2 diabetes. This broadens the real world clinical evidence base Medtronic can point to with physicians.
- Now the focus shifts to how Medtronic's broader investment narrative could be influenced by stronger SPYRAL AFFIRM renal denervation data.
Medtronic Investment Narrative Recap
To own Medtronic, you need to be comfortable with a large device maker that grows by rolling out new therapies while managing product complexity and recalls. According to LunaRodas, an investor in the Simply Wall St Community, the bigger narrative is about multiple product engines carrying mid single digit revenue expansion and steady earnings growth rather than rapid acceleration.
Recent FDA enforcement reports around the OmniaSecure defibrillator lead and CareLink SmartSync programmer keep product quality and regulatory execution in focus. These recalls look contained in volume but still lean into the key near term risk that quality issues distract management and absorb capital just as newer growth drivers such as cardiac ablation and renal denervation seek wider adoption.
The enforcement report tied to the OmniaSecure Model 3930M ventricular lead is probably the most relevant disclosure for investors watching Medtronic right now. It touches the cardiac rhythm management franchise that management previously highlighted as a flagship contributor with durable growth, so product reliability in this area matters for the broader story.
Here, the recall is voluntary and covers 717 leads that may be harder to fix during implantation, with the FDA classifying it as Class II. The operational question for shareholders is whether issues like this stay isolated events or start to weigh on cardiology growth, salesforce bandwidth, and regulatory scrutiny just as SPYRAL AFFIRM renal denervation data is trying to support a cleaner growth catalyst.
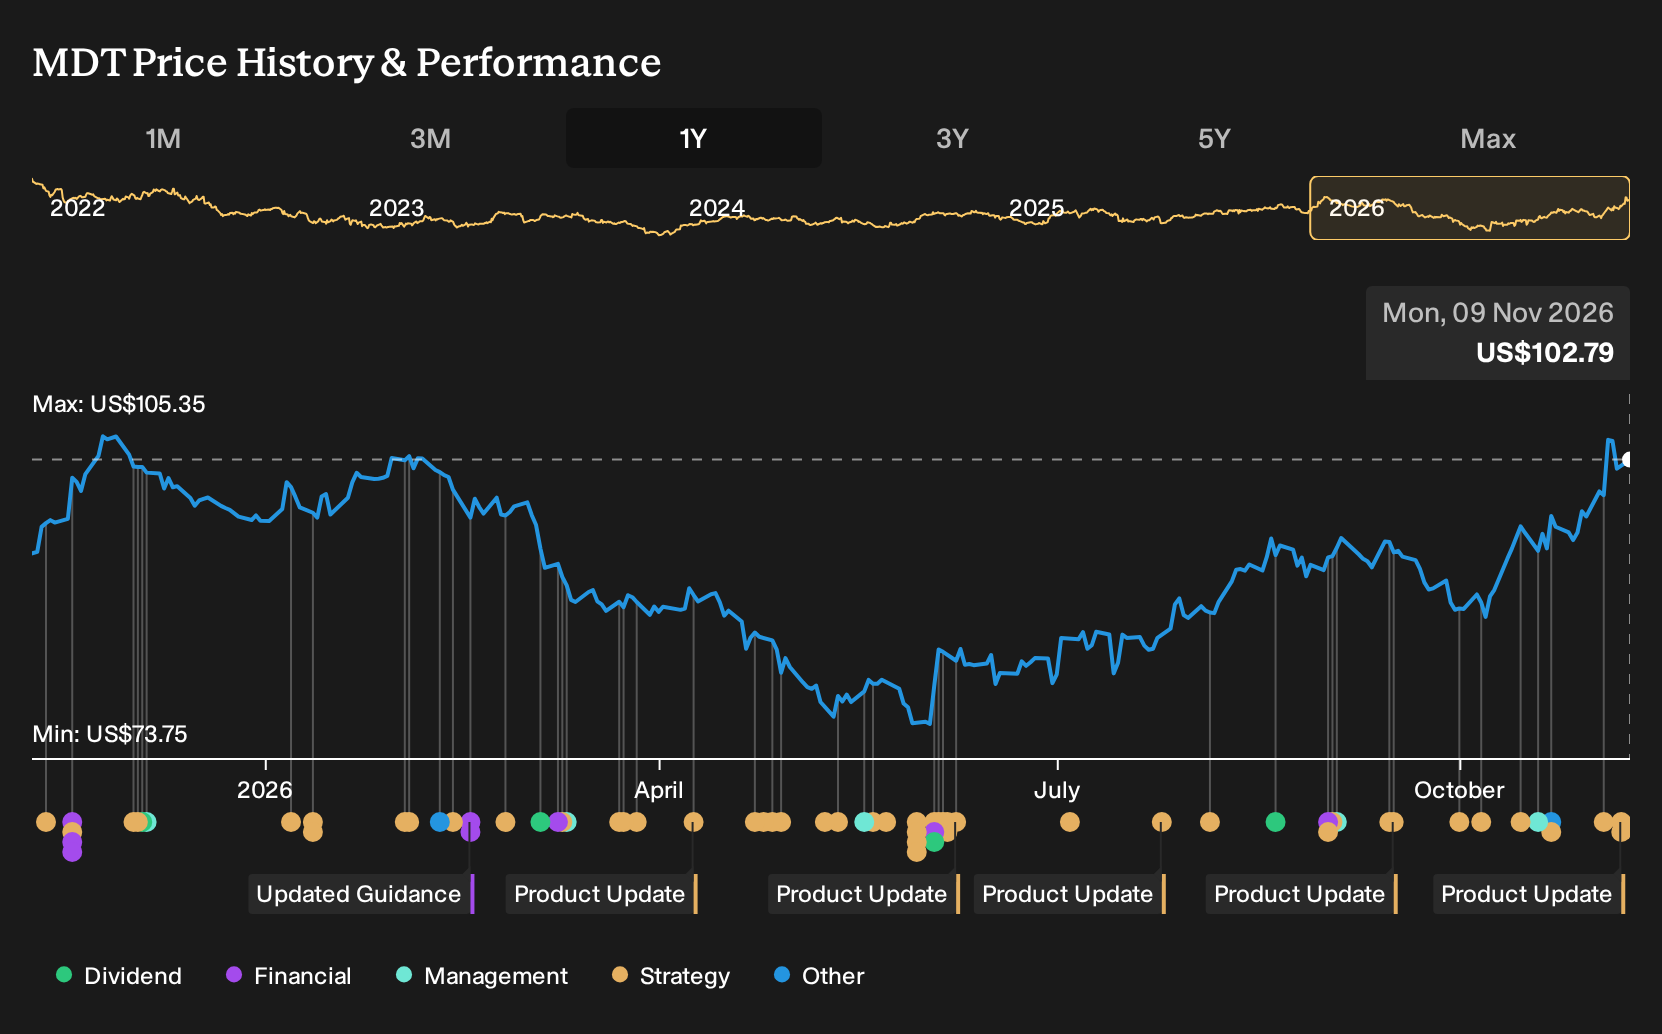
LunaRodas anchors the Medtronic fair value at US$115.38 mainly on the view that multiple product lines, including cardiac ablation, cranial and spinal technologies, pelvic health, and structural heart, are already carrying the growth workload today rather than sitting as distant optionality.
Uncover why Medtronic's fair value indicates a 12% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame renal denervation as the swing factor for Medtronic, not a side story. Before this recall and SPYRAL AFFIRM update, the highest forecasts were built on revenue climbing 6% a year and earnings reaching US$7.8b by about 2029. Those expectations could look either too cautious or too generous once this new information is fully digested, so treat them as one viewpoint and compare it with your own.
Explore 6 other Medtronic fair value estimates, including one that suggests as much as 12% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Medtronic research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Medtronic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Medtronic's overall financial health at a glance.
Looking for more investment ideas beyond Medtronic?
If Medtronic is just one position on your watchlist, it can help to line it up against other opportunities using the Simply Wall St Screener. That way you can compare quality, income potential, and balance sheet strength instead of viewing Medtronic in isolation.
- For investors hunting for quality on sale, start with companies that combine solid fundamentals with appealing valuations through the 33 high quality undervalued stocks.
- If steady income is a priority, scan for businesses offering higher yields and robust payout profiles by checking the 6 dividend fortresses.
- For a focus on resilience, look across companies with strong financial footing and clean balance sheets using the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com